NRI Property Buying in Dubai vs Noida: Rupee Math for 2026 Investors
Gross rent looks attractive, but net rupee yield tells the real story. See how a Noida flat stacks up against a Dubai apartment for NRI investors in 2026.
If you are an NRI or an Indian investor who earns in dollars, dirhams or pounds, the question that keeps coming back is simple: does a flat in Noida actually make sense against the Dubai apartment you have been eyeing? The answer depends less on headline prices and more on what lands in your Indian bank account after tax, after vacancy, after maintenance, and after the rupee does whatever it does that year. A flat that looks cheap on a listing portal can return less than a government bond once you account for all of that, and a Dubai unit with a juicy gross yield can disappoint once you convert, withhold and reinvest.
Over the last two years, a large number of NRIs have returned to Indian real estate, pulled by the Yamuna Expressway and Noida Extension corridors, the Jewar airport narrative, and a sense that the NCR market has finally repriced after a long stretch of flat values. At the same time, Dubai prices have touched multi-year highs, and many investors who sold there are now looking for the next place to park money. This article gives you a rupee-denominated framework to compare the two, a worked example, a comparison table, and a checklist you can take to your CA or your relationship manager. The primary question we will answer is how to think about an NRI property investment in Noida in 2026 without fooling yourself with gross numbers.
Key Takeaways
- Compare net rupee yield, not gross rent. Deduct property tax, society maintenance, vacancy, agent fees and the TDS you will not get back in full.
- Noida rental yields on a flat usually sit well below Dubai gross yields, so capital appreciation and exit liquidity carry most of the return case.
- Model the rupee two ways: flat, and depreciating 3 to 4 percent a year against your home currency. A deal that only works if the rupee stays put is a weak deal.
- Capital gains on Indian property for NRIs carry specific rules on holding period, indexation and TDS. Get the numbers from a CA before you sign an agreement to sell.
- Check RERA registration, the builder's escrow account status and the land title chain before any token amount changes hands. Most Noida regret stories start there.
NRI property investment Noida 2026: what the rupee math actually looks like
Start with a number that most investors skip: what the flat will earn you in rupees after everything comes out of the rent. Gross rent is the number on the listing. Net rent is what is left after you pay the costs that come with owning a flat in a society. In Noida, those costs include society maintenance charges that run roughly ₹2 to ₹4 per square foot per month in most mid-range projects, a property tax that is modest but needs annual payment, and brokerage that is typically one month's rent on a leave-and-license deal. Add an allowance for vacancy, which in Noida's rental market varies a great deal by micro-location and furnishing, and you have the first real layer of the calculation.
On the income side, rent from an Indian property is taxable in India under the head "income from house property." You get a standard deduction of 30 percent of the net annual value, and you can claim interest on the home loan if the property is let out, subject to the limits in the Income Tax Act. Rent is taxed at your slab rate, and because you are an NRI, the tenant is generally required to deduct TDS before paying you. The rate and mechanics depend on the nature of your residential status and the treaty position for your country of residence, so the exact tax you pay is something your CA should compute for your specific case rather than something you estimate from a blog post.
Here is the core formula to use on every comparison:
- Annual gross rent = monthly rent × 12 × (1 − vacancy allowance). Use 8 to 10 percent vacancy for a conservative Noida estimate.
- Less annual society maintenance, property tax, and agent fee (amortised over the lease).
- Less tax on the net rental income, after the 30 percent standard deduction and any interest you claim.
- Net rupee yield = the remainder ÷ current market value of the flat.
- Add expected annual capital appreciation in rupees to get a total rupee return. Be honest about this number. Base it on a 5 to 7 year history in that micro-market, not on the last twelve months.
- Then run the same model with a currency overlay: if you hold dirhams, dollars or pounds, convert the rupee return back to your home currency at a conservative rupee depreciation rate.
Done this way, a flat that shows a 4 percent gross yield often lands near 2 to 2.5 percent net in rupee terms, and sometimes lower in a year when the flat sits empty for three months. Dubai gross yields in the 5 to 7 percent range shrink too, but the net-to-gross gap is usually narrower because service charges are smaller and there is no comparable property tax drag. The comparison is therefore not as lopsided as headline numbers suggest, and it is more sensitive to exit timing and currency than most NRIs expect.
A worked example: a 2BHK in Noida Extension against a 1BR in Dubai Marina
Consider a case we have seen in various forms. A software consultant in Dallas, earning in US dollars, wants to deploy ₹1.2 crore of savings. Her two options are a 2BHK in a Noida Extension society, around 1,150 square feet, bought under construction, and a one-bedroom in a Dubai Marina tower, around 800 square feet, bought ready.
On the Noida side, assume a purchase price of ₹1.1 crore all-in with registration and stamp duty, monthly maintenance of ₹3,000 on a 1,150 square foot unit, and a rent of ₹28,000 a month for a furnished leave-and-license. With 9 percent vacancy, gross rent comes to about ₹3.06 lakh a year. Deduct maintenance of ₹36,000, property tax and agent fee of roughly ₹25,000, and you are at about ₹2.45 lakh before tax. After the 30 percent standard deduction and with no home loan interest claimed, taxable income is about ₹1.71 lakh. At her slab rate, tax comes to roughly ₹52,000, leaving a net of about ₹1.93 lakh. Net rupee yield on ₹1.1 crore is therefore around 1.75 percent. If the micro-market appreciates at 6 percent a year in rupees, total return is about 7.75 percent in rupee terms before currency.
On the Dubai side, assume a purchase price of AED 1.25 million, rent of AED 105,000 a year, service charge of AED 12 per square foot, and 7 percent vacancy. Gross rent after vacancy is about AED 97,650. Service charges and agent fees take out roughly AED 15,000, leaving AED 82,650, which is a net yield of about 6.6 percent on purchase price. Dubai has no income tax on rent for individuals, so the rupee-equivalent return in her hands is substantially higher on the rental line. Appreciation in Dubai has been volatile, so for the comparison we assume a more conservative 3 percent a year in dirhams.
Now the currency overlay, which is where most comparisons quietly break. She is a USD earner. A rupee that weakens 3 percent a year against the dollar erodes the Noida return by roughly the same margin, which pulls her effective dollar return down to a few percent. The dirham is pegged to the dollar, so the Dubai return does not get that drag. This is why the Dubai asset can look better even when its gross yield is no higher than Noida's gross yield in rupee terms. The honest conclusion for her is not that Dubai wins. It is that Noida needs a meaningful rupee appreciation scenario to match Dubai, and she should decide whether she is willing to take that bet.
Pro Tip: Most NRIs model the Indian property at today's exchange rate and forget that the rent they collect in rupees has to be converted back to their home currency every year. Run your model with the rupee at three different levels, a flat case, a 3 percent depreciation case and a 6 percent depreciation case. If the deal only clears in the flat case, you are speculating on the currency, not investing in the flat.
How do NRIs compare Dubai and Noida apartments on a like-for-like basis?
A like-for-like comparison means holding the investment horizon, the currency assumption and the tax treatment constant across both assets. Here is a summary using the example above, with the caveat that every figure is illustrative and depends on your own tax position and the specific unit you buy.
| Criterion | Noida Extension 2BHK | Dubai Marina 1BR | Dwarka / Gurugram 2BHK (for reference) |
|---|---|---|---|
| Purchase price (all-in) | ~₹1.1 crore | ~AED 1.25 million (~₹2.9 crore) | ~₹1.1 to ₹1.4 crore depending on micro-market |
| Gross rental yield (approx.) | 3 to 3.5% | 5.5 to 7% | 2.5 to 3.5% |
| Net rupee yield after costs and tax | ~1.5 to 2% | Higher, depends on your tax residency | ~1.5 to 2% |
| Currency exposure for USD earner | High, rupee-linked | Low, dirham pegged to USD | High, rupee-linked |
| Liquidity on exit | Moderate, deeper pool of Indian buyers | Moderate, mainly expat and foreign buyers | Moderate to good |
| Key compliance overhead | RERA, TDS, capital gains rules, FEMA reporting | Dubai land department registration, local tax filings | RERA, TDS, capital gains rules, FEMA reporting |
Two things stand out. First, the rupee-linked Indian option always carries currency risk that a dollar-earning investor has to price in deliberately. Second, the Indian option often gives you more emotional and practical comfort, because the legal system, the family network and the ability to visit regularly all make monitoring easier. Those are real benefits, and they belong in the decision, but they should not be mistaken for return.
What is the step-by-step process for an NRI to buy a Noida flat in 2026?
The process is less daunting than it looks, but the order matters. Doing the steps out of sequence is where most avoidable losses happen.
- Fix your residential status and tax position first. Whether you are an NRI, a PIO or an OCI holder changes what you can do and how income is taxed. Confirm it with your CA before you talk to any developer.
- Open the right bank channel. Payments should come from an NRE or NRO account, or from a foreign currency remittance, with the paperwork your bank requires. Keep every remittance receipt. You will need them later for FEMA compliance and for the capital gains computation.
- Verify RERA registration on the Uttar Pradesh RERA portal. Check the project's registration number, the sanctioned plan, the completion timeline and the builder's history of complaints. A project without RERA registration is a serious warning sign.
- Check the escrow account. Under RERA, a share of buyer payments must go into a designated escrow account for construction. Ask the developer to confirm the account arrangement in writing.
- Do the title search. Get the chain of title for the land, confirm there are no encumbrances, and check the approvals from the Noida authority or Greater Noida authority depending on which side of the expressway the project sits.
- Read the builder-buyer agreement line by line. Pay particular attention to possession timelines, delay compensation, the carpet area definition, parking allocation, and the clauses on cancellation and refund.
- Plan the payment schedule. Match your remittances to the construction-linked milestones. Do not pay large lump sums ahead of construction progress.
- Register the sale deed and pay stamp duty. Stamp duty and registration in Uttar Pradesh are significant costs. Budget for them explicitly in your all-in price.
- Set up the rental operation. Decide whether you will self-manage or use a property manager, and document the lease or leave-and-license in a way that protects your rights under local rent law.
- Calendar your reporting obligations. FEMA reporting for property acquisition, TDS certificates for rental income, and the capital gains computation when you eventually sell all need records. Keep a dated folder for each.
Common Mistake: Many NRIs pay the token amount and the first two installments in full, then discover that the project's approved plan has changed and the carpet area on paper is smaller than the sales brochure implied. Always request the sanctioned layout and compare the carpet area to the figure in your agreement before the second payment. A ten-minute check can save a lakh of rupees in disputes.
Which compliance requirements should Indian investors and NRIs not overlook?
Compliance is where experienced practitioners earn their fees, because the rules are technical and the penalties for missing a deadline are real. The main areas to track are the following.
- FEMA reporting. Acquisition of immovable property from abroad, and the eventual repatriation of sale proceeds, have specific reporting and documentation requirements. Work with a bank that handles NRI real estate routinely.
- TDS on rent and on sale. Tenants are generally required to deduct TDS on rent paid to an NRI. On sale, the buyer must deduct TDS on the consideration, and the rate depends on the holding period and the nature of the gain. Plan your cash flow around the fact that TDS is deducted before you receive the money.
- Capital gains. Gains on sale are taxed as short-term or long-term depending on the holding period, with indexation rules that have changed over recent budgets. Your CA should model the tax on sale before you commit to a holding plan.
- GST on under-construction property. Certain under-construction purchases attract GST, and the rate and the treatment of land components have been subject to change. Confirm the GST component in your payment schedule and ask whether it is included in the quoted price.
- Income tax return filing. Rental income must be declared in your Indian return, and the NRI filing obligations should be reviewed annually.
If your investment sits inside a broader business structure, for example a company or an LLP that holds property, the compliance picture changes again, with additional corporate filings and possibly MSME-related considerations if the entity is also an operating business. For those cases, bringing in a practitioner who understands both property and corporate compliance is worth the fee.
Should an NRI buy under construction or ready-to-move in Noida?
This is the question I hear most often, and the honest answer is that it depends on your cash flow, your tolerance for delay and your need for immediate rental income. Under-construction units are usually priced lower per square foot and are paid in installments that match construction progress. The risks are delayed possession, which in NCR has been common, and the time before rental income starts. Ready-to-move units start producing rent sooner and let you inspect the actual flat, but they cost more and the price premium has to be justified against the rent you will collect.
A practical rule that many experienced investors use: if you are buying for capital appreciation and can wait three to four years without income, an under-construction unit from a RERA-registered builder with a clean delivery record can make sense. If you need the flat to pay its own way from day one, a ready unit with a proven rental history in the same society is usually the safer bet, even though the entry price is higher.
What are the real risks that could change the numbers?
Beyond the obvious currency and tax risks, there are three that get less attention than they deserve. The first is supply. Noida has a large pipeline of new launches, and if many of them complete in the same window, rents and resale values in comparable societies can soften. The second is the expressway and airport story. Infrastructure timelines have a habit of slipping, and an investment thesis built on a specific date for connectivity should be stress-tested against a two- to three-year delay. The third is liquidity. A flat in a well-located society is saleable, but the buyer pool for a specific unit at a specific price can be thin, and you may need to accept a discount to exit quickly.
Stress-test your model with a 20 percent fall in rent, a one-year extra vacancy, and a flat rupee. If the investment still makes sense as a holding, it is a sound one. If it only works in the best case, reconsider the size of the position rather than the decision to invest at all.
Frequently asked questions
Is rental income from a Noida flat taxable for an NRI?
Yes. Rental income from property in India is taxable in India, and the tenant is generally required to deduct TDS before paying you. The exact tax depends on your residential status, the standard deduction and any interest you claim, so have your CA compute it for your situation.
What is the best rental yield in Noida for an NRI investor?
Gross yields in Noida for furnished apartments typically sit in the low-to-mid single digits, but net yields after maintenance, tax and vacancy are usually lower. The best yield depends on the micro-location, the unit type and how well the property is managed, so compare net figures for specific societies rather than relying on city averages.
Can an NRI buy property in Noida without a home loan?
Yes, NRIs can buy property in India with cash remitted from abroad or from NRE and NRO accounts, subject to FEMA rules. Many NRIs also take Indian home loans, and banks have specific NRI loan products with their own eligibility and documentation requirements.
How long does it take to repatriate sale proceeds from India?
Repatriation of sale proceeds is governed by FEMA limits and the documentation requirements of your bank. The timeline depends on the paperwork being in order, including the sale deed, tax clearance and the TDS certificates. Plan for several weeks rather than assuming it will be immediate.
Is Dubai property better than Noida property for NRIs?
Neither is better in general. Dubai often shows higher gross rental yields and has dollar-linked currency stability, while Noida offers rupee exposure, familiarity and a deeper family and cultural connection. The right choice depends on your home currency, your tax position, your holding horizon and how much currency risk you are willing to carry.
What documents should I check before signing an agreement for a Noida flat?
Check the RERA registration and its validity, the sanctioned layout, the builder-buyer agreement, the title chain for the land, the approvals from the relevant authority, the escrow account arrangement, and the carpet area definition. Ask for copies of each and have a lawyer review the agreement before payment.
How often should an NRI review a Noida property investment?
Review at least annually, and also whenever there is a major change in the rupee, in tax rules, in the local rental market, or in your own residential status. A yearly review should update your net yield, your appreciation assumption, your currency scenarios and your compliance calendar.
Where eDarpan fits into an NRI property decision
If you are weighing a Noida purchase, the most useful next step is usually a structured comparison rather than a sales conversation. The model above is something you can build in a spreadsheet, and eDarpan's IT and business consulting team can help you set up the tracking, document calendar and scenario tools if you prefer a working system over a one-off calculation. For NRIs managing several assets across countries, a shared dashboard for rent collected, TDS certificates and FEMA paperwork is often more valuable than any single number in this article.
For listings and market context, you can browse properties for sale in India, check the rental side on rental properties in India, or explore the wider eDarpan Properties section. If you also need a registered address for an investment vehicle or a company that will hold property, eDarpan's virtual office address for GST and company registration is a practical option. If you want to compare how this decision looks against other markets, our earlier analysis on NRI home buying in Dwarka versus Dubai and the rupee returns after the 2026 rule changes covers the adjacent ground, and our piece on tier-2 cities rising in 2026 and where buyers get better value than NCR is useful if Noida's pricing does not fit your budget. For a broader view of the Dubai side, Dubai's property boom and whether NRIs should buy abroad or in NCR sets out the case in more depth, and Dubai, Dwarka and Gurugram rental yields for 2026 gives you a three-way yield comparison.
If you are ready to put numbers to your own situation, contact eDarpan and tell us your home currency, your target holding period and the budget you have in mind. We will help you build the model, check what needs a CA and what needs a lawyer, and tell you honestly whether a Noida flat fits your goals or whether another option makes more sense. You can also read more about how we work on the eDarpan about page.
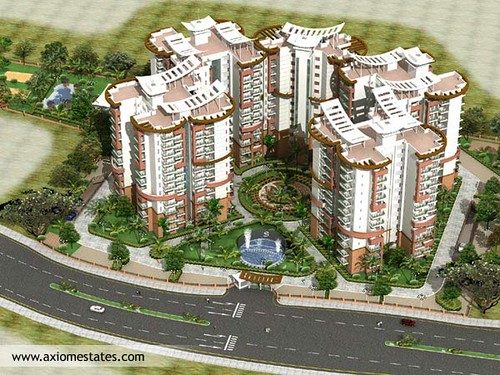
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Home Loan Rates Stuck or Falling? Pick Fixed vs Floating in NCR
Stuck EMI or chasing a lower rate? See how fixed vs floating home loans in India behave in today's RBI environment, and run the break-even math for NCR borrowers.
NRI Home Buying in Dwarka vs Dubai: Rupee Returns After 2026 Rule Changes
Dwarka or Dubai? See how rupee conversion, taxes, repatriation rules and hidden costs reshape NRI rental returns after the 2026 rule changes.
Tier-2 Cities Rising 2026: Where Indian Buyers Get Better Value Than NCR
NCR prices have outrun rental yields. Here's how to compare Indore, Nagpur, Coimbatore and Lucknow on real net returns, not broker hype, before you buy.