NRI Home Buying in Dwarka vs Dubai: Rupee Returns After 2026 Rule Changes
Dwarka or Dubai? See how rupee conversion, taxes, repatriation rules and hidden costs reshape NRI rental returns after the 2026 rule changes.
If you are an NRI or an overseas Indian weighing a property purchase, you have probably run the same spreadsheet many times. On one side sits a flat in Dwarka, a short hop from the IGI airport and the Dwarka Expressway. On the other sits an apartment in Dubai Marina, Business Bay or JVC, with a headline yield that looks better on paper. The question that actually decides the outcome is not the gross yield. It is what lands in your Indian bank account after currency conversion, taxes, management costs, vacancy and the rules that govern how money leaves the country. That is where most NRI property investment India vs Dubai rental returns comparisons quietly fall apart. Two things have changed the calculation recently. NRI buying in Indian metros has picked up noticeably, with more overseas Indians treating Delhi-NCR as a hedge against a rupee they expect to drift weaker over time. At the same time Dubai prices have rebounded from their post-2014 lows, which compresses the yield gap that used to make Dubai look clearly superior. A rebound in one market and a fresh wave of rules in the other means last year's rule of thumb is unreliable. This guide walks through how a practitioner would actually model the decision: rupee-adjusted yields, repatriation mechanics, the tax lines people forget, and a worked example you can adapt to your own numbers.
Key Takeaways
- Compare returns in rupees, after conversion, tax, management fees and realistic vacancy. Gross yield percentages from listing portals are not a basis for decision.
- Dubai's apparent yield advantage often shrinks to a narrow margin once service charges, DLD-related costs, agency fees and the AED-INR exchange path are included.
- Dwarka's value case rests more on capital appreciation tied to metro connectivity and the Expressway than on rent alone, so model a holding period of at least five to seven years.
- Repatriation of sale proceeds from India is governed by NRI rules under FEMA and the Income Tax Act. Keep purchase documentation, the inward remittance trail and your TDS certificates from day one.
- Your funding route (NRE, NRO or foreign remittance) changes both your repatriation rights and your tax position, so decide it before you sign.
How do NRIs compare rental returns in Dwarka and Dubai after rupee conversion?
Start with a single currency. Pick the rupee, because that is the currency you will eventually spend or repatriate in, and convert every cash flow using a conservative exchange assumption rather than today's spot rate. Many NRIs make the mistake of treating AED or USD rent as if it were already rupee income. A rupee that is expected to depreciate against the dirham by two or three percent a year quietly erodes the Dubai advantage over a decade.
The clean way to do this is a net rupee yield calculation, year by year:
- Gross annual rent in local currency, converted to INR at the assumed rate for that year.
- Less vacancy. Use 5 to 8 percent for well-located Dwarka flats with reliable tenant demand near the metro, and 6 to 10 percent for Dubai units where furnished and short-term-let shares are high. Be honest about your own unit's profile.
- Less recurring costs: property management (typically 5 to 10 percent of rent in Dubai, and 8 to 12 percent if you hire a Dwarka manager who handles tenant verification and repairs), society maintenance in India, Dubai service charges (often AED 8 to 20 per square foot annually depending on the building), insurance and agent fees.
- Less taxes on rental income. In India, rental income is taxed as income from house property with a standard 30 percent deduction on net annual value, and TDS applies at 30 percent on rent for NRIs unless a lower certificate is obtained. Dubai imposes no personal income tax on rent, which is a real advantage, but you still need to check tax residency rules in your country of citizenship and residence.
- Then compare the resulting net yield against your cost of capital, including the price you paid in rupees plus transaction costs.
Run this for both properties at the same purchase budget. A realistic example: a 1,100 sq ft three-bedroom in Dwarka Sector 19 near the metro might command a gross rent of around ₹38,000 to ₹45,000 a month depending on the society and finish. A comparable 1,000 sq ft unit in a Dubai mid-market tower might rent for roughly AED 9,000 to 11,000 a year-equivalent per month in some areas, but the same investment rupee amount buys a smaller unit in Dubai than it does in Dwarka. Always normalise to the same capital outlay, not the same unit size, or the comparison is meaningless.
A worked example: ₹1.2 crore across two markets
Consider a Gurugram-based NRI family returning to India in a few years who has ₹1.2 crore to deploy and is choosing between a Dwarka apartment and a Dubai apartment. Assume the Dwarka unit costs ₹1.2 crore all-in with registration and stamp duty, and generates ₹42,000 monthly rent, or ₹5.04 lakh a year gross. Vacancy at 6 percent drops that to about ₹4.74 lakh. Society maintenance and insurance take roughly ₹60,000. Management at 8 percent takes ₹38,000. Net operating income before tax is about ₹3.76 lakh, a net yield of roughly 3.1 percent on the rupee price. After the 30 percent standard deduction and TDS mechanics, the family's effective tax burden depends on their slab, but on a conservative view the post-tax income is in the 2.3 to 2.6 percent range.
Now the Dubai version: the same ₹1.2 crore at an assumed AED-INR path buys a unit that rents for, say, AED 110,000 a year gross. Vacancy at 8 percent brings it to about AED 101,000. Service charges at AED 15 per square foot on 850 sq ft come to roughly AED 12,750. Management at 7 percent takes around AED 7,000. Net operating income is near AED 81,000, which converts to a gross net yield around 6 to 6.5 percent on the same capital. No income tax is payable locally. The headline looks decisively better.
The gap narrows when you add the currency assumption. If you expect the rupee to weaken by 3 percent a year against the dirham, the rupee value of that Dubai income is worth less in each future year, but the capital you paid was also in rupees, so the real comparison is between a rupee-denominated return and a dirham-denominated return that you will convert later. Over a seven-year holding period, the Dubai advantage can compress meaningfully once you include exit costs, the eventual sale in AED and the conversion back. Model both an optimistic and a pessimistic exchange path and treat the spread between them as the risk you are actually taking.
Common Mistake: quoting gross yield from portals
Pro Tip: Most listing portals display gross yield, which is annual rent divided by price. Never use that number to decide. Strip out vacancy, management, service charges, society or maintenance costs and taxes, and then compare net figures. We have seen NRI clients reject a Dwarka unit with a 3 percent gross yield in favour of a Dubai unit showing 7 percent, only to find the net figures were within a point of each other once service charges and a realistic vacancy assumption were applied.
What are the NRI repatriation rules for Indian property sale proceeds in 2026?
Repatriation is where NRI property investment India vs Dubai rental returns analysis becomes a legal question rather than a financial one. Under the Foreign Exchange Management Act and the rules framed under it, an NRI or PIO may repatriate sale proceeds of an Indian property up to a certain limit per financial year, provided the property was acquired through legitimate inward remittance or from NRE, FCNR or NRO funds in the permitted manner. The specific limits and documentation expectations are set by RBI notifications and the bank's operating procedures, so verify the current figures with your bank and, for anything material, with a chartered accountant before committing.
The practical rule is simple: if you cannot prove where the money came from, you will struggle to send it out. Keep these documents from the day you buy:
- The sale deed and registration receipt showing the purchase price.
- Bank records of the inward remittance or NRE/NRO debit used for the purchase, with the FIRC or equivalent where applicable.
- Form 15CA and 15CB, prepared by a chartered accountant, for any outward remittance of income or sale proceeds that attracts them.
- TDS certificates (Form 16A) for rental income, and the Income Tax returns filed for each year.
- For Dubai purchases, the Dubai Land Department transfer documents and the purchase agreement, plus the remittance trail if you later bring proceeds back to India.
Step-by-step: preparing for an eventual sale in India
- Confirm your residency status for the year of sale, since it governs the tax treatment and the account you can credit proceeds into.
- Open or confirm an NRE or NRO account. Sale proceeds generally go into an NRO account, which has its own repatriation limit, so plan the flow in advance.
- Obtain a capital gains computation. Long-term capital gains on immovable property held beyond the threshold are taxed at 12.5 percent without indexation for most sales after the 2024 changes, but confirm the current rate and any grandfathering that applies to your acquisition date.
- Apply for a lower or nil TDS deduction certificate under Section 197 if your total tax liability is lower than the default TDS on the sale. The buyer deducts TDS on the sale consideration, and without a certificate you may be over-withheld.
- File Form 15CA and 15CB before remitting, and have the bank verify the documentation before the outward transfer goes through.
For Dubai, the picture is different. Dubai does not impose capital gains tax on individuals, but if your tax residency is elsewhere, the home country may tax the gain. Indian residents owning foreign property must also report it in Schedule FA of the Income Tax return and, where applicable, comply with the Foreign Assets disclosure regime. Ignoring Schedule FA is one of the most common and expensive compliance errors we see among returning NRIs.
Which costs do NRIs underestimate in each market?
Acquisition costs get attention. Running costs and exit costs usually do not. Here is how the two markets compare on the lines people miss.
| Criterion | Dwarka (Delhi, India) | Dubai (UAE) | Dubai (UAE) with management | Notes |
|---|---|---|---|---|
| Acquisition costs | Stamp duty and registration in Delhi, typically around 6 percent combined, plus brokerage | DLD transfer fee around 4 percent plus agency and admin fees | Same as left | Confirm current percentages with the registrar and your agent before finalising budgets |
| Recurring maintenance | Society maintenance and repairs, usually modest | Service charges per square foot, varies widely by building | Same as left | Dubai service charges can exceed the rent yield on some older towers |
| Rental management | Self-managed or 8 to 12 percent via a local agent | Typically 5 to 10 percent via a licensed property manager | Required for most absentee owners | Dubai managers are regulated through RERA; check licence status |
| Tax on rental income | Taxable in India at slab rates with 30 percent standard deduction | No personal income tax locally | Home-country tax may still apply | Residency status drives the outcome |
| Exit and repatriation | NRO account, TDS and Form 15CA/15CB | Dubai sale proceeds in AED, conversion and remittance | Same as left | Plan the funding route before purchase |
Pro Tip: model vacancy and service charges separately
Many NRI investors model a flat vacancy percentage and forget that Dubai service charges are fixed regardless of occupancy. A unit that sits empty for two months still owes the full service charge. Build your model with vacancy applied to rent only and service charges as a fixed annual cost, then stress-test the case where the unit is empty for three months in a year. The result is often a much tighter margin than the simple percentage model suggests.
Is Dwarka a sound investment for NRIs compared with Dubai?
Dwarka's investment case is less about the current rental yield and more about the infrastructure story. The Delhi Metro's Dwarka corridor, the proximity to IGI Airport, and the Dwarka Expressway all support long-term demand, and areas near the metro stations have historically seen steadier tenant absorption. But rent alone rarely justifies a Dwarka purchase in the short run. You are buying a bet on continued infrastructure build-out and capital appreciation over five to seven years, and that bet can be wrong if a particular sector develops slowly or if the supply of new apartments outpaces demand.
Dubai's case rests on a different foundation: higher gross rents, tax efficiency and a more transparent off-plan and secondary market under RERA regulation. The risks are a supply overhang in some districts, a currency mismatch for Indian-rupee earners, and the reliance on tourism and expat inflows. Neither market is clearly superior. The right choice depends on whether you want rupee-denominated exposure you can easily use in India, or dirham-denominated exposure that diversifies away from the rupee.
For many NRIs we work with, a split strategy makes more sense than an all-in bet. Keep the primary residence and a core investment in India where you will eventually live, and use a smaller Dubai position to diversify currency and tax exposure. The exact split depends on your family plans, your comfort with management complexity, and how much liquidity you need.
What checklist should an NRI follow before buying in either market?
- Define your holding period and the currency you will ultimately spend in.
- Build a net rupee yield model with vacancy, service charges, management and tax, plus a pessimistic exchange rate scenario.
- Confirm your funding route (NRE, NRO or foreign remittance) and the repatriation implications.
- Verify the property's title, RERA registration (for India, the state RERA portal; for Dubai, the Dubai Land Department and RERA records) and any encumbrances.
- Appoint a local property manager with a verifiable licence and references, and obtain the management agreement in writing.
- Consult a chartered accountant on Indian tax and Schedule FA disclosure, and a Dubai-qualified adviser on local transfer costs and any home-country tax implications.
- Set up document storage from day one, including remittance trails and TDS certificates.
If you are running the numbers for Indian property specifically, our eDarpan Properties team can help you shortlist units across Dwarka and wider NCR, and our properties for sale in India listings include the infrastructure details you need to model rent and appreciation. For rental-side modelling, see our rental properties in India section. If you are comparing before committing, the related analysis in Dubai Property Boom Draws Indian NRIs: Should You Buy Abroad or in NCR? goes deeper into the market cycle, and Dubai vs Dwarka vs Gurugram 2026: Where NRIs Get Real Rental Yields sets out the yield comparison across all three markets.
Frequently asked questions
How much tax does an NRI pay on rental income from a Dwarka flat?
Rental income from Indian property is taxed under the head income from house property at your applicable slab rate, after a standard deduction of 30 percent of net annual value and permitted municipal taxes. Tenants or payers typically deduct TDS at 30 percent on rent for NRIs, which you can adjust when you file your return or claim a refund if over-deducted.
Can an NRI send rental income from Dubai to India?
Yes, rental income earned abroad can be remitted to India through normal banking channels, subject to the purpose and documentation requirements of your bank. Keep the tenancy contracts, rent receipts and proof of the source of funds, and check whether any Indian tax on the foreign income applies to your residency status for that year.
What is the NRI repatriation limit for property sale proceeds in India?
Repatriation limits are set under RBI rules and apply to proceeds credited to NRO accounts, with an annual cap per financial year for the sale of immovable property. Confirm the current limit with your authorised dealer bank before the sale, because it can change through RBI notifications.
Do I need an NRE account to buy property in India?
You do not strictly need an NRE account to buy property, since purchases can be funded through foreign remittance or an NRO account. However, the source of funds matters for repatriation later, so an NRE or properly documented inward remittance is usually the cleaner route for money you may want to send back out.
Is Dubai property a good investment for Indian residents?
It can be, particularly for diversification and for buyers who value tax efficiency on rent. The result depends on the specific building's service charges, your vacancy assumption, the exchange-rate path and your residency-based tax obligations. A net yield model beats any headline figure.
What documents do I need to prove source of funds for an NRI property purchase?
Bank statements showing the remittance or account debit, the FIRC or equivalent remittance certificate, a copy of the purchase agreement and sale deed, and the income proof from your country of residence are the core set. Your bank or chartered accountant can tell you exactly what they require for your funding route.
Should I hire a property manager for an NRI-owned flat in Dwarka?
For most NRIs living abroad, yes. A reliable manager handles tenant verification, rent collection, repairs and society dues, which are hard to supervise remotely. Budget 8 to 12 percent of rent and insist on written reporting, a verifiable licence or track record, and clear termination terms.
If you want help building a net rupee yield model for your specific budget, or a second opinion on how your funding route affects repatriation, contact eDarpan. You can also learn more about our team and how we work with overseas clients on our about page. For the wider picture on where value is shifting across Indian cities, our analysis of tier-2 cities rising in 2026 and how metro and redevelopment are changing prices in Goregaon and Dwarka is a useful next read.
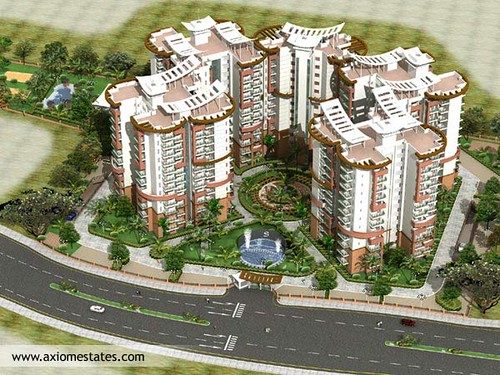
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Home Loan Rates Stuck or Falling? Pick Fixed vs Floating in NCR
Stuck EMI or chasing a lower rate? See how fixed vs floating home loans in India behave in today's RBI environment, and run the break-even math for NCR borrowers.
NRI Property Buying in Dubai vs Noida: Rupee Math for 2026 Investors
Gross rent looks attractive, but net rupee yield tells the real story. See how a Noida flat stacks up against a Dubai apartment for NRI investors in 2026.
Tier-2 Cities Rising 2026: Where Indian Buyers Get Better Value Than NCR
NCR prices have outrun rental yields. Here's how to compare Indore, Nagpur, Coimbatore and Lucknow on real net returns, not broker hype, before you buy.