Dubai Property Boom Draws Indian NRIs: Should You Buy Abroad or in NCR?
Dubai prices are booming, but is buying abroad smarter than NCR for NRIs? We compare net yields, repatriation rules and currency risk to help you decide.
Every year, thousands of Indian families and NRIs sit down with a spreadsheet, a rupee-to-dirham conversion, and a question that sounds simple but is not: should the next property purchase happen in Dubai or back home in Delhi-NCR? Dubai's residential market has been running hot, with prices and transaction volumes at levels not seen in roughly four years, and that headline is pulling attention away from Indian cities that still offer deep rental demand, established infrastructure and a legal framework most Indian investors understand. If you are weighing NRI property investment India vs Dubai 2026, the right answer depends less on which market is "hotter" and more on yield after costs, how you will actually get your money out, and how much currency risk you are willing to carry on a 15-year holding.
This piece works through those trade-offs the way a consultant would walk a client through them: the numbers, the tax and repatriation mechanics, the hidden costs, and the decision framework. Where the answer changes based on your situation (salaried NRI in the Gulf, resident Indian with surplus cash, retiree planning a return), we say so. Nothing here is personal tax or legal advice, so treat the examples as a starting point for a conversation with your CA and an RERA-aware advocate.
Key Takeaways
- Headline Dubai price growth does not translate into Dubai yield. Compare net rental yield after service charges, agency fees and vacancy, not gross yield on the listing page.
- Indian rental yields in NCR are typically lower on paper (often in the 2 to 3.5 percent range for good residential stock) but carry lower entry friction and no foreign-currency exposure on your income stream.
- Repatriating sale proceeds from India is governed by FEMA and the NRI purchase rules; sale proceeds from Dubai flow through a different set of banking and documentation steps. Plan the exit before you buy.
- Rupee-denominated expenses and rental income combined with an AED or USD asset creates a currency mismatch that can swing your effective return by several percentage points in a single year.
- Budget for the full acquisition cost: Dubai DLD transfer fees, Indian stamp duty and registration, and in both cases legal and brokerage costs that routinely add 5 to 10 percent to the sticker price.
- Decide the purpose first (income, capital appreciation, retirement, family use). The right market follows from the purpose, not the other way round.
Is Dubai property still worth it for Indian NRIs, or is the boom priced in?
The honest answer is that Dubai's appreciation over the last few years has been real and broad-based, but it has also pulled prices in premium pockets well ahead of rental income. When a Dubai apartment's price rises faster than the rent it commands, your gross yield compresses even as your paper gain grows. For an investor who needs cash flow, that is a warning sign. For one who plans to sell in five to seven years, it may be exactly the outcome they wanted.
Start with the metric that matters. Gross yield is annual rent divided by purchase price. Net yield subtracts the costs an owner actually bears: service charges (which in many Dubai communities run from roughly AED 8 to AED 25 per square foot per year depending on the building), property management fees (often 5 to 8 percent of rent), agency fees on new tenancies, and an allowance for vacancy. A listing advertising 7 percent gross can easily net 4 to 5 percent once those are subtracted, and in older or off-plan-heavy communities the figure can be lower still.
Indian NCR yields look modest on paper. A decent 2BHK in a established Gurugram or Noida society might rent in the range of ₹25,000 to ₹45,000 a month against a purchase price that puts gross yield somewhere between 2.5 and 3.5 percent, with society maintenance, property tax and occasional repairs taking another chunk. The comparison is not as lopsided as headlines suggest, because Indian rentals are also less volatile in some micro-markets and carry none of the currency mismatch an NRI faces with a dirham asset. For a detailed look at how two NCR markets compare on yield, our analysis of Gurugram vs Noida 2026: Which NCR market gives better rental yields? walks through the numbers by micro-market.
A worked example: AED 1.2 million in Dubai vs ₹1.2 crore-equivalent in NCR
Consider a Gulf-based NRI with roughly ₹1.2 crore in investable capital (we will ignore the exact exchange rate and work in round terms). Option A is a one-bedroom apartment in a mid-tier Dubai community bought at around AED 1.2 million. Option B is a 2BHK in a built-up Greater Noida West or Dwarka-adjacent project priced at roughly the same rupee value. Here is how the first-year cash picture looks in simplified form:
- Dubai: Gross rent of around AED 80,000 a year. Less service charges of about AED 12,000, management at 6 percent (roughly AED 4,800), and a vacancy allowance of one month (about AED 6,700). Net operating income lands near AED 56,500, which is about 4.7 percent on the purchase price. Add the DLD transfer fee (4 percent of price, plus a small registration charge) and agency commission at purchase, and your all-in acquisition cost sits meaningfully above the sticker.
- Greater Noida West: Gross rent of perhaps ₹2.4 to ₹2.8 lakh a year. Less society maintenance, property tax, and an allowance for repairs and vacancy, net yield typically falls in the 2.5 to 3.2 percent range. Stamp duty and registration in Uttar Pradesh add roughly 7 percent or more to the cost at purchase depending on the registration category and buyer profile, so the upfront hit is real.
The Dubai asset produces more income per dirham invested. The NCR asset produces less income but comes with an Indian legal system you know, rupee cash flows that match rupee expenses, and no dependence on a dirham-to-rupee rate. Which you prefer depends on what you are optimizing for.
What taxes and repatriation rules should NRIs check before buying in India or Dubai?
This is where most NRI investment decisions quietly go wrong, because the questions that matter most are not on the property listing. In India, an NRI can generally buy residential and commercial property, but agricultural land, plantation property and farmhouses carry separate restrictions under FEMA. Rental income from Indian property is taxable in India, and the tenant is typically required to deduct TDS at source. Long-term capital gains on sale are taxed in India, and the buyer of an NRI-held property must generally deduct TDS on the sale consideration, which is where timing and documentation become critical.
The repatriation question is separate from taxation. An NRI can typically repatriate sale proceeds of a property acquired through foreign-currency inflows, up to limits, provided the purchase was funded and documented appropriately. Rental income repatriation is subject to its own conditions after tax. The practical rule: keep a clean paper trail of where the purchase money came from, retain the sale deed, the TDS certificates (Form 16A, and the Form 16B or equivalent for property-linked deductions), and your bank records. Missing one document at exit can delay repatriation by months.
Dubai is simpler on the tax side because the UAE levies no personal income tax on rental income or capital gains for individuals at the time of writing, which is a large part of the appeal. But the Indian tax position does not disappear. Rental income earned abroad by a resident Indian is still reportable in India, and you may be able to claim foreign tax credits or rely on the India-UAE double taxation avoidance agreement depending on your residency status. Do not assume zero tax anywhere. Confirm your residential status for the relevant financial year, because it determines what you report.
Pro Tip: Confirm your residential status before you sign anything
The most expensive mistake we see is an NRI who assumed they were still non-resident for tax purposes after extended stays or a return to India, then discovered their Dubai rental income was taxable in India at slab rates they had not budgeted for. The number of days you spend in India in a financial year determines your status, and the thresholds differ by circumstance. Before you purchase, get a written residency determination from your CA for the past two years, not an informal estimate.
How does currency risk change the Dubai vs India decision?
The dirham is pegged to the US dollar, which gives Dubai asset holders a relatively stable anchor against USD but a floating relationship with the rupee. If your income and your expenses are in rupees, buying an AED asset means every year your net return is a function of two things: the property's performance in dirhams and the AED/INR exchange rate. Over multi-year periods, that rate has moved enough to swing a 5 percent dirham return into a noticeably different rupee outcome.
The reverse risk applies to an NRI who earns in AED or USD and later holds a rupee asset. A weakening rupee can boost the rupee value of the Indian property at exit, which may look like a gain on paper while your income in foreign currency is quietly eroding in real terms. Neither direction is inherently safer. The useful question is: where will you spend the money when you need it, and does the asset's currency match that need?
A simple discipline helps. Write down your expected rupee expenses over the holding period (children's education, medical costs, a planned return to India) and match asset currency to those liabilities as closely as possible. If most of your future spending will be in rupees, a rupee asset reduces your exposure. If you plan to remain abroad and spend in dirhams or dollars, the Dubai asset starts to look like a natural hedge rather than a speculative bet.
What are the total acquisition costs in Dubai vs NCR and Indian cities?
Sticker prices are where the comparison usually starts and where it should not end. The table below compares the cost and practicality factors most relevant to a buyer weighing these options, with figures expressed as typical ranges rather than fixed quotes. Verify current rates with the relevant authority before you commit.
| Criteria | Dubai (mid-tier residential) | Delhi-NCR (Gurugram / Greater Noida West) | Dwarka (Delhi) | Mumbai suburbs (e.g., Goregaon) |
|---|---|---|---|---|
| Typical gross rental yield | About 5 to 7 percent, varies widely by community | About 2.5 to 3.5 percent | About 2.5 to 3.5 percent | About 2 to 3 percent |
| Transfer and registration cost | DLD transfer fee around 4 percent of price plus registration charges | Stamp duty and registration in UP or Haryana, often 6 to 8 percent depending on buyer and category | Delhi stamp duty and registration, roughly 6 percent plus registration fee | Stamp duty and registration in Maharashtra, roughly 5 to 6 percent plus fees |
| Currency match for an Indian-earning investor | Low (AED asset) | High (INR asset) | High (INR asset) | High (INR asset) |
| Ongoing costs to model | Service charges, management fee, agency on new tenancy | Society maintenance, property tax, repairs | Society maintenance, property tax, repairs | Society maintenance, property tax, repairs |
| Repatriation complexity at exit | Moderate, depends on banking and documentation | Moderate, FEMA and TDS documentation required | Moderate, FEMA and TDS documentation required | Moderate, FEMA and TDS documentation required |
Treat the stamp duty and registration figures as indicative only, since they change with state notifications, buyer category and property type. The point of the table is structural: Indian acquisition costs are front-loaded and substantial, while Dubai costs are also front-loaded but the ongoing service and management charges need closer modelling. If you are comparing with a property in a specific Indian city, our breakdown of Goregaon vs Dwarka 2026: where redevelopment and metro lift prices shows how infrastructure announcements shift the value of similar-looking assets.
How should an NRI or Indian investor choose between Dubai and an Indian city step by step?
A decision framework is more useful than a verdict. Work through these steps in order and write the answers down.
- Define the purpose. Is this for monthly income, long-term appreciation, a retirement home, or a family asset you may use yourself? Each purpose points toward a different market.
- Map your future liabilities by currency. List expected rupee and foreign-currency expenses over the next 10 years. Match the asset currency to where most of the cash will be spent.
- Model net yield, not gross yield. For each shortlisted property, subtract service charges or maintenance, property tax or equivalent, management fees, vacancy and repairs. Compute the net figure as a percentage of total acquisition cost including transfer fees.
- Confirm the tax position for both countries. Get your residential status determined for the relevant years. Ask your CA specifically about TDS on rental income, capital gains treatment and the foreign tax credit position.
- Plan the exit before the entry. Decide how and when you would sell and repatriate proceeds. Identify the documents you will need and where your purchase funds are traceable from.
- Stress-test the currency. Model the outcome if the dirham or rupee moves 10 to 15 percent against your home currency during the holding period. If the investment only works in the base case, it is a speculation, not an investment.
- Verify the title and the developer. In Dubai, check the property's registration with the Dubai Land Department and, for off-plan purchases, the escrow arrangement. In India, verify RERA registration for the project and the title chain for the specific unit.
Most buyers who complete these steps find that one option clearly fits their purpose and currency profile. Buyers who skip them tend to buy on headlines and discover the cost structure later.
What is the realistic budget and timeline for buying property in each market?
Timelines matter because they interact with exchange rates and with your own schedule. A Dubai purchase through a ready-property transaction can typically close in a few weeks once financing and the NOC from the developer are in place, with off-plan purchases running on the payment schedule of the project. In India, an NRI purchase involves more documentation steps: a power of attorney if you are not present, bank approvals for funds from abroad, stamp duty payment and registration at the sub-registrar office, and mutation in the revenue records. A realistic allowance for a clean Indian transaction is two to four months from agreement to registration, longer if title is complicated.
On budget, add a contingency of 8 to 10 percent above the agreed price for transfer costs, legal fees, brokerage and first-year maintenance. Buyers who budget only the sale price often find themselves short at registration and forced to draw on a second source of funds at the worst moment.
Common Mistake: Buying the rental story instead of the rental data
Brokers in both markets will show you a rent figure per square foot pulled from the best-performing building in a development. Ask for transaction-level data for the specific building and the specific unit type, covering at least the last 12 months of actual leases, and check the vacancy history. A projected rent in a brochure and a signed lease at that rent are different facts, and the gap is where NRI returns often disappear.
Is a Dubai or Indian property better for NRIs in 2026? Final verdict for different profiles
There is no universal winner, but the profiles tend to sort cleanly. A Gulf-based NRI who plans to stay abroad, earns in dirhams, and wants income in the same currency will often find Dubai a natural fit despite the entry costs, provided net yield survives the modelling. An NRI who expects to return to India within a decade, or who has significant rupee liabilities, will usually find an NCR or Dwarka asset reduces currency mismatch and simplifies the exit. A retiree planning to live in India may prefer a city property they can occupy, where emotional and practical value outweighs yield.
For a practical comparison of how Indian options differ within the NCR, our guide to Dwarka vs Greater Noida West 2026: where your home budget goes further and Dwarka flat vs Dwarka plot: which gives better returns in 2026? cover the trade-offs between product types and micro-locations in more depth. If you are also considering commercial exposure, our piece on foreign capital chasing Indian commercial property explains what small investors should check before committing.
If you want help modelling this for your specific situation, eDarpan Properties works with NRI and resident buyers on both residential sale and rental listings across Indian cities. You can browse current inventory on our properties page, see listings specifically for properties for sale in India, or explore rental properties in India if you are weighing a leased rather than purchased home. For the broader technical and digital side of managing a remote property portfolio, including document workflows and client communication, our IT consulting team and service overview cover what we can set up. You can also contact eDarpan to discuss your case, or read more about who we are before you decide.
Frequently asked questions about NRI property investment India vs Dubai 2026
Is it better for an NRI to buy property in Dubai or India in 2026?
It depends on purpose and currency. Dubai offers higher gross yields in many communities and no personal income tax on rent, but it carries AED exposure and higher entry costs. Indian cities offer lower gross yields with rupee-matched income, which suits NRIs with rupee liabilities or plans to return.
Can NRIs buy property in India without restrictions?
NRIs can generally buy residential and commercial property in India, but agricultural land, plantation property and farmhouses are subject to FEMA restrictions. Purchase funds should come through proper banking channels, and documentation matters for later repatriation.
How is rental income from Dubai property taxed for Indian residents?
The UAE does not levy personal income tax on rent, but rental income earned abroad may still be reportable in India if you are a resident Indian for tax purposes. You may be able to claim foreign tax credits under the India-UAE tax treaty. Confirm your residential status and reporting obligations with a CA.
What is the real rental yield on Gurugram or Noida property?
Good residential stock in established NCR micro-markets commonly yields in the range of about 2.5 to 3.5 percent gross, with net yield lower after maintenance, property tax and vacancy. Exact figures depend on the society, unit size and lease history, so ask for actual lease data rather than broker projections.
How much extra should I budget beyond the purchase price?
A prudent contingency is 8 to 10 percent of the agreed price for transfer costs, stamp duty or DLD fees, registration, legal fees, brokerage and early maintenance. Indian stamp duty and registration in particular are substantial and vary by state and buyer category.
Can I repatriate sale proceeds from an Indian property if I move abroad?
Generally yes, subject to FEMA conditions, limits and documentation, including proof that the purchase was funded appropriately and that taxes on the sale have been deducted and reported. Keep your sale deed, TDS certificates and bank records organised from the start.
Should I hedge currency risk when buying an overseas property?
Matching the asset currency to your future liabilities is the most practical hedge. Beyond that, some investors use forward contracts or staged remittances, but these carry their own costs and should be evaluated with a banker or financial adviser before use.
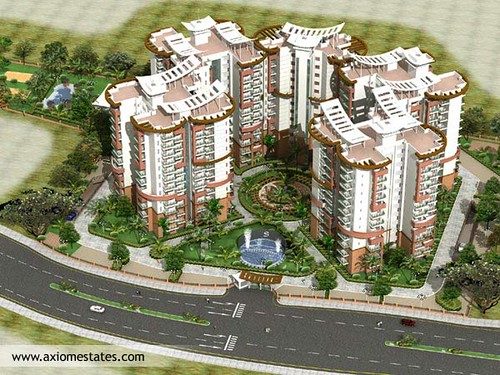
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Goregaon vs Dwarka 2026: Where Redevelopment and Metro Lift Prices
Two 3BHKs near metro stations, a ₹33 lakh gap: is Dwarka a bargain or a trap? A practical framework to judge metro premiums and redevelopment risk.
Foreign Capital Chasing Indian Commercial Property: What Small Investors Should Know
Foreign capital is flooding Indian offices and warehouses. Here's how small investors with ₹25 lakh to ₹2 crore can get exposure through REITs and fractional ownership.
Gurugram vs Noida 2026: Which NCR Market Gives Better Rental Yields?
Gross yields look tempting, but net returns tell the real story. We compare Gurugram and Noida rental yields for 2026, with costs, taxes and a worked example.