Tier-2 Cities Rising 2026: Where Indian Buyers Get Better Value Than NCR
NCR prices have outrun rental yields. Here's how to compare Indore, Nagpur, Coimbatore and Lucknow on real net returns, not broker hype, before you buy.
If you have been watching property listings in Gurugram or Noida lately, you have probably felt the squeeze. A 1,400 sq ft flat in a decent sector that sold for around ₹1.1 crore two years ago now carries a ticket price well north of ₹1.4 crore in many micro-markets, and the monthly EMI on a 20-year home loan at current rates makes that number hard to justify for a first-time buyer earning a typical mid-level salary. Rental yields in much of NCR have not kept pace with capital appreciation, which means the gross yield on a ₹1.4 crore flat often sits in the low single digits once you account for maintenance, property tax and vacancy.
The question many buyers are now asking is whether the same money, or even less of it, could buy them more footprint, better rental returns and comparable long-term growth in a city like Indore, Nagpur, Coimbatore or Lucknow. Demand for tier-2 cities property investment India 2026 has been rising steadily as employers decentralise hiring, IT and GCC (global capability centre) campuses spread beyond the metros, and state governments push infrastructure spending. Some of that momentum is real. Some of it is hype sold by developers who have land to clear. This guide is about telling the two apart.
Over the next sections we will look at how to compare price growth, rental yields and infrastructure across markets, work through a numbers-based case study, lay out a step-by-step due diligence process, and cover the compliance points that small investors routinely get wrong. You will also find a comparison table, a checklist you can take to a broker, and an FAQ for the questions people actually type into search engines.
Key Takeaways
- Compare net rental yield (after property tax, society charges, insurance and realistic vacancy), not the gross figure a broker quotes you.
- Tier-2 price growth is uneven. Judge a micro-market by absorption (how many units actually sell) and by upcoming employment anchors, not by the developer's brochure.
- Infrastructure only adds value when it is funded, approved and has a credible completion date. A metro line on a government PDF is not the same as a metro line with tunnelling underway.
- Budget at least 8 to 10 percent of the purchase price for stamp duty, registration, legal and brokerage, and for furnishing if you plan to rent.
- Check RERA registration on the state portal before you pay any token amount. Unregistered projects in a tier-2 city are the single most common trap we see.
- For a first purchase, keep the EMI at or below roughly 35 to 40 percent of household income so that one bad year does not force a distressed sale.
Why are buyers looking beyond Delhi-NCR for a tier-2 cities property investment India 2026 strategy?
The honest answer is arithmetic. NCR's core appreciation came from a decade of infrastructure, expressways, the Delhi Metro's expansion and a steady stream of corporate tenants. Those gains have already been priced in for many buyers who entered in the early 2020s. What remains is a market where entry prices are high relative to what the average salary can service, and where rental yields do not comfortably cover the cost of capital.
Tier-2 cities have different economics. Land is cheaper, per-square-foot prices are typically a fraction of NCR's, and the gap between what a unit costs and what it can rent for is often wider in a positive direction. But cheaper does not automatically mean better. A property in a city with a shrinking employer base or a stalled road project can sit empty for a year, and that vacancy wipes out the yield advantage quickly.
The useful framing is to ask where the jobs are going, not just where the cheap land is. Hiring by global capability centres in Pune, Hyderabad, Chennai and increasingly Indore, Coimbatore and Kochi has created pockets of rental demand that follow employment, not the other way round.
How do you compare price growth, rental yields and infrastructure without being fooled by brochures?
Start by building a simple scorecard for every micro-market you are considering. Three numbers matter more than anything a sales executive will tell you.
Step 1: Calculate net rental yield properly
Take the annual rent you can realistically achieve, not the best-case figure on a portal. Then deduct:
- Property tax (usually modest, but it varies sharply by municipality)
- Society maintenance, which in many newer tier-2 townships runs ₹2 to ₹5 per sq ft per month
- Insurance, if you take it
- A vacancy allowance, which we suggest at least one month a year for a well-located flat and two or more for a peripheral one
- Any agent commission or property management fee
Divide the net figure by the purchase price. In many tier-2 markets this lands between 3 and 5 percent net, which is not spectacular but compares reasonably with a fixed deposit once you factor in potential capital growth. In over-priced NCR micro-markets it can drop below 2.5 percent.
Step 2: Check absorption, not just price trends
Price indices can mislead. A city can show rising average prices simply because developers launched a few premium projects. What you want to know is how many units are being sold and occupied, and how long inventory sits. Ask builders for their unsold-inventory numbers in a specific project and ask local brokers how many resale listings have been on the market for more than six months. Those two answers tell you more than any index.
Step 3: Map infrastructure to funding status
Every tier-2 city has a list of announced projects: metro lines, ring roads, airport expansions, industrial corridors. Sort them into three buckets:
- Funded and under construction with a published completion date and visible progress.
- Sanctioned or tendered but without a confirmed contractor or financing.
- Announced in a press release or a master plan, with no tender.
Give bucket one full weight, bucket two partial weight, and bucket three almost none. Many buyers pay a premium for bucket three promises and then wait years.
Worked example: a first-time buyer comparing a Gurugram flat with an Indore flat
Consider a hypothetical but realistic case. Priya is a 31-year-old product manager earning ₹26 lakh a year in Gurugram. She has ₹35 lakh saved and wants to buy a 2 BHK for self-use with a plan to rent it out when she relocates. She is comparing two options.
Option A: a 1,250 sq ft flat in a mid-tier Gurugram society at ₹13,500 per sq ft, total about ₹1.69 crore including parking. Her down payment after 20 percent and registration costs would take nearly all her savings, and the loan EMI at around 8.5 percent over 20 years would be roughly ₹1.43 lakh a month. That is more than 60 percent of her take-home pay, which is not workable. The monthly rent for a similar unit is around ₹38,000, giving a gross yield near 2.7 percent, and after society charges and property tax the net yield is closer to 2.2 percent.
Option B: a 1,250 sq ft flat in a well-run township in Indore at ₹4,800 per sq ft, total about ₹60 lakh. Her 20 percent down payment plus costs fits comfortably within her savings with room left for a furnishing budget. The loan EMI on a ₹48 lakh principal is roughly ₹41,000 a month, which is about 19 percent of her take-home. Rent for a similar unit near an IT or GCC cluster is around ₹17,000 to ₹19,000, giving a net yield in the region of 3.5 to 3.8 percent.
Option B is not a free lunch. Indore's resale market is thinner, so exit takes longer. The rental pool is smaller, which means a tenant leaving can cost her two months of vacancy. And her capital growth assumption has to be more conservative than a Gurugram buyer's would have been a few years ago. But her cash-flow position is far healthier, and that is what keeps first-time buyers out of distress.
Priya's decision was not about which city is "better." It was about which set of numbers she could live with for the next decade. For more on how these trade-offs look when set against foreign options, our piece on NRI property investment in India versus Dubai in 2026 walks through a similar framework.
Which tier-2 city fits your budget? A comparison
The table below gives a rough, directional comparison of five markets that come up often in investor conversations. Figures are indicative ranges based on typical listings and should be verified locally before you commit. Treat them as a starting point for your own research, not as quotes.
| City | Typical price band (per sq ft, mid-segment) | Net rental yield (indicative) | Employment anchors | Key watch-out |
|---|---|---|---|---|
| Indore | ₹4,500 to ₹5,500 | 3.5 to 4.2% | IT parks, GCC expansion, education hub | Thinner resale liquidity |
| Coimbatore | ₹4,000 to ₹5,200 | 3.2 to 4.0% | Manufacturing, engineering, textiles | Peripheral sprawl, uneven infrastructure |
| Lucknow | ₹4,200 to ₹5,800 | 3.0 to 3.8% | Government, healthcare, expressway access | Price competition in new townships |
| Nagpur | ₹3,800 to ₹5,000 | 3.4 to 4.1% | Logistics, MIHAN corridor, central location | Project-level quality varies widely |
| Gurugram (for reference) | ₹11,000 to ₹15,000 | 2.0 to 2.8% | Corporate headquarters, finance, consulting | Yield compression, high entry cost |
Notice that the yield gap is not the only thing that differs. Employment concentration, resale depth and project quality vary enormously within each city, so the table is most useful as a reason to dig deeper, not as a verdict.
What is a step-by-step due diligence process before you pay a token amount?
Most costly mistakes happen before the agreement is signed. Here is the sequence we recommend to clients, and which you can hand to your broker or lawyer.
- Confirm RERA registration. Look up the project on your state's RERA portal (Maharashtra, Madhya Pradesh, Uttar Pradesh and others each run their own). Check the registration number, the approved layout, the promised completion date and whether the developer has filed quarterly updates. An unregistered project can still be legal for some older schemes, but for a new purchase you want the protection RERA provides.
- Verify title with a lawyer. Get an independent title search covering at least the last 30 years, including mutation records and any encumbrance certificate. Do not rely on the seller's own papers.
- Check land-use and municipal approvals. Confirm the plot is zoned residential, that building plan sanction exists and that occupancy certificate timelines are realistic.
- Visit at different times. Go on a weekday evening and a weekend morning. Note traffic, water supply, power backup and how far the nearest functioning hospital and school are.
- Speak to existing residents. Ask about maintenance disputes, promised amenities that were never delivered and how the resident association handles conflict.
- Get a construction-linked payment plan reviewed. Compare the stage-wise demands against actual progress. A demand for the next instalment should match visible work on site, not the calendar.
- Price in every cost. Stamp duty and registration vary by state and can run from around 5 to over 7 percent combined. Add brokerage, legal fees and, if you are furnishing for rent, your fit-out budget.
Pro Tip: check the sewage and drainage plan, not just the water supply
Brokers talk about water supply and power backup. Few mention the sewage treatment plant or the stormwater drainage design, which matter far more in cities with heavy monsoon rainfall. We have seen gated townships in tier-2 cities flood their basements twice in one season because the drainage was designed for the sanctioned layout and not for the ground levels actually built. Ask for the drainage drawing and have a civil engineer glance at it. Thirty minutes of checking can save you a lot of pain.
What compliance and tax points should small investors know in 2026?
Several rules catch investors out, especially those buying their first property or buying as part of a small partnership.
- Capital gains on resale. Long-term capital gains on property are generally taxed at 12.5 percent without indexation for transfers on or after 23 July 2024, with the option to choose indexation for properties acquired before that date, subject to the rules in force at transfer. Confirm the current position with a chartered accountant before you plan an exit.
- Section 54 and 54F reinvestment. Gains can be exempted if reinvested in a residential property within the prescribed window. The conditions are specific, so do not assume an exemption until your CA has confirmed it in writing.
- Rental income and GST. Residential rent is generally outside GST for individual landlords, but commercial leasing is not. If you lease a unit to a business tenant or register a commercial space, check whether GST applies and whether the tenant can claim input credit.
- TDS on rent. If monthly rent exceeds the prescribed threshold, the tenant is generally required to deduct TDS and deposit it with the government. Make sure you receive Form 16C or the equivalent so you can claim credit when filing your return.
- Co-ownership and partnerships. If you are buying jointly with a sibling or friend, decide up front on the share of ownership, who pays what, and how a sale or exit is handled. A written co-ownership agreement is cheap insurance against family disputes.
If you plan to operate a small business from a commercial unit, or register a company with a rented address, our virtual office service for GST and company registration can provide a compliant registered address while you decide where to put down a physical base.
What should a first-time tier-2 buyer bring to the broker meeting?
Walking in prepared changes the conversation. Use this checklist:
- A one-page budget showing your maximum all-in outlay, not just the down payment
- Your income proof and the bank's pre-approval letter, if you have one
- A list of three micro-markets you want to compare, with the reasons for each
- Your intended holding period, because it changes whether yield or capital growth matters more
- A clear answer on whether the property is for self-use, rental, or both
- The RERA numbers for every project on your shortlist
- Questions about absorption, resale time and maintenance history, not just the sales pitch
Where does a digital partner fit into a property decision?
Property buying is mostly a paperwork and judgement exercise, but for investors who also run small businesses or manage multiple properties, the digital side matters more than people expect. Keeping tenant communication, rent reminders and maintenance requests in one place is much easier with a proper setup. Our WhatsApp Business API and bulk SMS services are commonly used by landlords and property managers to send rent reminders, collect acknowledgements and notify tenants of maintenance windows, while a voicebot can handle routine enquiries after hours. If you are managing a growing portfolio, a light IT consulting review of your records and tools can prevent a lot of lost time later.
For buyers who want the property search itself handled properly, eDarpan Properties lists homes for sale and rent across India, and you can browse properties for sale in India or rental properties in India depending on your stage. If you are weighing a rental-led strategy specifically, our analysis of rental yields across Dwarka, Gurugram and Dubai shows how the numbers compare when you widen the lens.
Is it better to buy now in NCR or wait for a tier-2 entry point?
There is no universal answer, and anyone who gives you one without seeing your numbers is selling something. What we can say is that the decision is less about the city and more about three personal variables: your income stability, your holding period and your need for liquidity. A buyer with a secure job in Gurugram who plans to stay for ten years may still be right to buy there, provided the EMI is comfortable and they accept modest yields. A buyer who is relocating for work in two years should probably rent in NCR and buy later.
If you are still undecided, our buy-or-rent math guide for Delhi-NCR lays out the full calculation, and the Goregaon versus Dwarka analysis shows how infrastructure announcements translate into price movement, and where they do not. For wider context on institutional money moving into the sector, see our note on what foreign capital in commercial property means for small investors.
Frequently asked questions
Are tier-2 cities property investment India 2026 options actually safer than NCR?
Not automatically. Tier-2 markets carry different risks, mainly thinner resale liquidity and uneven project quality. They can be safer on cash flow because entry prices and EMIs are lower, but a poorly chosen project in a weak micro-market can underperform NCR. Safety comes from due diligence, not from the city name.
What is a realistic rental yield in Indore or Coimbatore?
For well-located mid-segment properties, net yields in the range of roughly 3 to 4 percent are typical in many tier-2 markets, though this varies by micro-location and project. Always calculate net yield after property tax, society charges and a vacancy allowance, and verify rents with local brokers and listing data rather than relying on a single quote.
How do I check whether a project is RERA registered?
Search for the project name or the developer on your state's RERA website and confirm the registration number on the official portal. Compare the approved layout and completion date against what the sales team has told you. Never rely on a registration number that is only printed in a brochure without verification.
Should I buy for self-use or as a rental investment in a tier-2 city?
Buy for self-use if you plan to live there for at least five to seven years and your EMI is comfortable. Consider a rental-led purchase only if you have a clear tenant pool, a realistic yield and enough reserves to cover vacancy and repairs. Mixing the two goals often leads to compromises on both.
What does stamp duty and registration cost add up to?
It varies by state and sometimes by gender of the buyer or by the type of property, but combined stamp duty and registration commonly runs from around 5 to over 7 percent of the property value. Check your state's current rates on the official revenue or registration department website and budget accordingly.
Can I buy property in a tier-2 city if I live in NCR?
Yes. Many buyers purchase remotely using a power of attorney for registration formalities, but this carries risk. Use a lawyer you trust, verify every document independently and consider visiting in person at least once before you sign. A local site visit with a trusted representative is worth the time.
How much should my home loan EMI be relative to income?
A common planning guideline is to keep total EMIs at or below roughly 35 to 40 percent of household take-home income. That leaves room for emergencies and lifestyle costs. Lenders may approve a higher ratio, but approval is not the same as affordability.
If you are ready to take the next step, talk to the eDarpan team about your budget and timeline. We can help you shortlist markets, check digital and compliance readiness for any business use of the property, and point you to the right listings. You can also learn more about eDarpan and how we work with buyers and small investors across India.
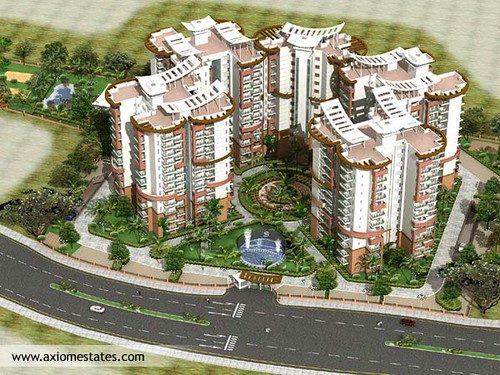
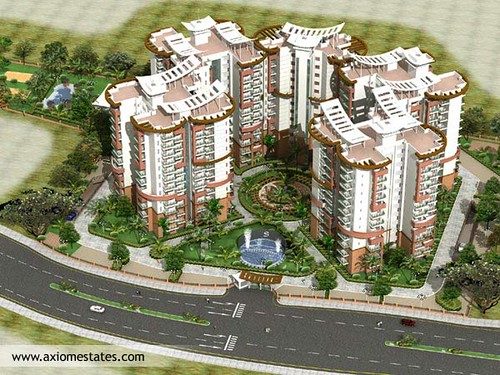
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Dubai vs Dwarka vs Gurugram 2026: Where NRIs Get Real Rental Yields
Gross yields mislead NRIs. We compare net rental yields across Dwarka, Gurugram and Dubai after service charges, TDS, tax and vacancy to show where real returns land.
Delhi-NCR Homes Hit Record Prices: Buy or Rent Now? A Q4 2026 Math Guide
Record prices in Gurugram, Noida and Dwarka have made buy or rent the hardest call yet. Run the break-even math with real loan rates, yields and hidden costs.
Dubai Property Boom Draws Indian NRIs: Should You Buy Abroad or in NCR?
Dubai prices are booming, but is buying abroad smarter than NCR for NRIs? We compare net yields, repatriation rules and currency risk to help you decide.