Home Prices Outpacing Salaries in India 2026: Buy or Wait?
Homes in India cost 7-8x your salary while incomes crawl. Use our city-by-city framework to decide whether to buy now or wait two to three years.
Here's the math that keeps a lot of my clients up at night. A 32-year-old software engineer in Bengaluru earning ₹18 lakh a year looks at a 2BHK in Whitefield priced at ₹1.4 crore. That's roughly 7.8 times his gross annual income. His father bought a comparable house in 1998 for about 3.5 times his salary. The engineer earns more in real terms than his dad ever did, yet the house feels twice as far out of reach. He's not imagining it.
Between 2020 and 2025, residential prices in the top eight Indian cities rose by anywhere from 35% to over 60% depending on the micro-market, while median urban salaries limped along at single-digit annual increments that barely kept pace with inflation. When your asset appreciates faster than your ability to earn the down payment, waiting feels expensive and buying feels reckless. Both can't be true, so which is it for you?
This post is a decision framework, not a cheerleading exercise for either camp. We'll break down the home price to income ratio India 2026 city by city, run an actual buy-versus-rent calculation with real rupee figures, and give you a checklist you can work through this weekend. By the end you'll know whether your specific situation points to buying now or renting for another two to three years.
Key Takeaways
- A price-to-income ratio above 7 signals a stretched market; Mumbai and Delhi NCR sit well above this, while Pune and Hyderabad remain relatively saner at 5–6.
- Your real breakeven isn't the sticker price. Factor in stamp duty, GST on under-construction units, registration, and 1.5–2% annual maintenance before comparing to rent.
- If rental yield in your target area is below 3% and you plan to stay 7+ years, buying usually wins. Below that horizon, renting and investing the difference often beats it.
- Interest rate direction matters more than price direction for affordability. A 100 bps rate cut can improve your EMI capacity by roughly 8–9%.
- Under-construction discounts look attractive but carry GST (5% without ITC) plus completion risk. Ready-to-move avoids GST entirely.
- Don't time the market perfectly. Time your own finances: stable income, 20% down payment saved, and an EMI below 40% of take-home.
Why is the home price to income ratio in India 2026 so stretched?
The price-to-income ratio (PTI) is the cleanest single number for judging affordability. You take the median home price in a city and divide it by the median annual household income. A healthy, affordable market sits around 3 to 4. Anything above 5 starts pinching, and above 7 you're in the territory where a middle-class family cannot reasonably buy without either significant family wealth or a punishing 25-year loan.
India's metros drifted into that stretched zone for a few reasons that compounded over five years. Construction input costs rose sharply after 2021, with cement, steel, and labour all climbing. Developers who survived the RERA shakeout and the NBFC liquidity crunch had less competition, so they held pricing firm. Meanwhile the post-pandemic rush for larger homes drove demand for the exact 3BHK and villa formats that carry the fattest margins.
Salaries, on the other hand, didn't cooperate. IT hiring cooled in 2023-24, startup compensation corrected, and outside of a handful of high-growth sectors, most urban professionals saw 6–9% annual hikes. When your asset inflates at 12% and your income at 7%, the gap widens every single year you wait. That's the trap.
What is the affordability math by city right now?
Let me put real numbers on the table. These figures reflect mid-segment ready-to-move 2BHK units in established residential zones, and median dual-income household earnings for a working couple in their early thirties. Treat them as directional, not gospel, because micro-markets vary wildly within the same city.
| City | Median 2BHK Price | Median Household Income (annual) | Price-to-Income Ratio | Typical Rental Yield |
|---|---|---|---|---|
| Mumbai (suburbs) | ₹1.85 crore | ₹22 lakh | 8.4 | 2.8% |
| Delhi NCR (Gurgaon/Noida) | ₹1.35 crore | ₹20 lakh | 6.7 | 3.0% |
| Bengaluru | ₹1.20 crore | ₹21 lakh | 5.7 | 3.4% |
| Pune | ₹90 lakh | ₹18 lakh | 5.0 | 3.6% |
| Hyderabad | ₹95 lakh | ₹18 lakh | 5.3 | 3.5% |
Notice the inverse relationship between PTI and rental yield. Mumbai's 8.4 ratio and 2.8% yield tell the same story from two directions: the property is expensive relative to both what you earn and what it can fetch in rent. When yields fall this low, you're effectively paying a premium for the hope of capital appreciation, which is a bet, not a certainty.
Pune and Hyderabad look the most balanced. Not cheap, but a PTI of 5 with a 3.5%+ yield means the buy decision doesn't require heroic assumptions about future price growth. If you're location-flexible and buying purely as an investment, that gap is worth noting. Our team at eDarpan Properties tracks these micro-market shifts, and the intra-city spread is often larger than the inter-city one.
Buy or rent: how do you actually run the numbers?
Forget rules of thumb. Run your own case. Here's a worked example using a real client scenario, anonymised.
The case: a Gurgaon couple, ₹20 lakh combined income
Ravi and Sneha, both 31, earn ₹20 lakh combined, take-home about ₹1.35 lakh a month after tax and PF. They're renting a 2BHK in Sector 54 for ₹38,000 a month. They're eyeing a ready-to-move 2BHK in the same corridor priced at ₹1.35 crore. Let's compare.
Buying scenario:
- Property price: ₹1.35 crore
- Stamp duty + registration (Haryana, ~7% for joint ownership with female co-owner): ₹9.45 lakh
- Down payment (20%): ₹27 lakh
- Loan amount: ₹1.08 crore at 8.5% for 20 years
- EMI: approximately ₹93,700 per month
- Annual maintenance + property tax: ~₹1.1 lakh (₹9,200/month)
Total monthly outflow on the home: roughly ₹1.03 lakh. That's 76% of their take-home. Add the ₹36.45 lakh upfront cash they need (down payment plus registration), and this scenario is a stretch that borders on financially dangerous. Their EMI-to-income ratio blows past the 40% ceiling most lenders and advisors treat as the red line.
Renting scenario:
- Rent: ₹38,000/month, escalating ~7% annually
- Cash they'd have kept invested: ₹36.45 lakh (the down payment + stamp duty)
- Monthly savings vs buying: roughly ₹65,000 (EMI + maintenance minus rent)
If Ravi and Sneha invest that ₹36.45 lakh corpus and the ₹65,000 monthly difference into a diversified equity fund returning a conservative 11% over 10 years, they'd accumulate well over ₹2 crore. In the same period, the flat appreciating at a hopeful 7% annually would be worth around ₹2.65 crore, but they'd have paid roughly ₹1.12 crore in EMIs plus the upfront ₹36 lakh to get there.
Pro Tip: The buy-versus-rent decision hinges almost entirely on your holding period and the rental yield gap. In a market where yields are below 3% and you're not certain you'll stay 7+ years, renting and disciplined investing frequently wins. But "disciplined investing" is the catch. Most people who rent instead of buy don't actually invest the difference. They spend it. If you're honest with yourself and know you won't invest that ₹65,000 every month, the forced-savings nature of an EMI makes buying the better behavioural choice, even when the spreadsheet disagrees.
What hidden costs wreck first-time buyer budgets?
The sticker price is the beginning of the conversation, not the end. First-timers routinely under-budget by 12–18% because they anchor on the base price the developer quotes.
- Stamp duty and registration: 5–7% depending on state, and worth registering in a woman's name where states offer a rebate (Delhi, UP, Haryana all do).
- GST on under-construction: 5% on non-affordable housing with no input tax credit passed to you, 1% on affordable units. Ready-to-move with a completion certificate attracts zero GST. This alone can swing a decision by ₹5–7 lakh.
- Parking, club membership, PLC: Preferential location charges, floor rise, and covered parking can add ₹8–15 lakh on a premium unit.
- Interiors and move-in: Even a "ready" flat needs ₹6–12 lakh of woodwork, appliances, and fittings.
- Loan processing and insurance: Processing fees, legal charges, and a home loan protection plan the bank will push hard.
If you're an NRI evaluating a purchase, the cost structure and tax treatment shift further, including TDS on the sale and repatriation limits. Our detailed breakdown on NRI property buying in India in 2026 covers the FEMA rules and repatriation math worth reading before you wire funds.
How much does the interest rate matter versus the price?
Here's something most buyers get backwards. They obsess over shaving ₹3–4 lakh off the price and ignore that a 1% swing in interest rates changes their total repayment by far more.
On a ₹1 crore loan for 20 years, moving from 9% to 8% cuts your EMI from about ₹89,970 to ₹83,640. That's ₹6,330 a month, or over ₹15 lakh across the full tenure. A rate environment that's softening does more for your affordability than a modest price correction ever will.
This is also why an existing borrower shouldn't sit on a legacy loan at an inflated rate. If your current lender is charging you 9.4% while new customers get 8.4%, a balance transfer can recover serious money. We walk through the exact process and break-even math in our guide to home loan balance transfer in India in 2026. Do the switch before you commit to a new purchase so you know your true borrowing capacity.
Should you buy under-construction to save money?
Under-construction units are typically priced 15–25% below ready-to-move in the same project, and the developer often sweetens it with subvention schemes. It's tempting. It's also where first-timers get burned.
The trade-offs are concrete: you pay 5% GST that a ready unit avoids, you pay EMI or pre-EMI while also paying rent on your current home, and you carry completion risk. Even post-RERA, delays of 12–24 months are common. Run the calendar carefully.
- Verify RERA registration on the state authority's portal. No registration number, no conversation.
- Check the developer's delivery track record across their last three projects, not their brochure.
- Insist on a construction-linked payment plan over an upfront-heavy one, so your money is tied to actual progress.
- Model the double outflow of rent plus pre-EMI for the expected construction period, and add a 12-month buffer.
- Confirm the GST rate in writing and whether the price is inclusive.
Common Mistake: Buyers assume a signed rent agreement protects them if they need to move out early during construction delays. It usually doesn't. Read the lock-in and notice clauses before you sign. Our guide on rent agreement registration in India in 2026 explains what tenants and landlords each owe, and why an unregistered agreement gives you almost no legal standing in a dispute.
When does buying now genuinely make sense?
Despite all the caution, buying now is the right call for plenty of people. The framework isn't "prices are high, so wait." It's a set of conditions. Buy now if most of these are true for you:
- You've saved a full 20% down payment plus registration costs without touching your emergency fund.
- Your EMI would stay at or below 40% of take-home income.
- Your income is stable and you expect to hold the property for at least 7 years.
- You've found a ready-to-move unit that avoids GST and completion risk.
- Rental yield in the area is 3.5% or higher, meaning you're not overpaying purely on speculation.
- You value the stability and are prepared to lose flexibility, which has real personal worth beyond the spreadsheet.
Festive quarters can also improve the deal meaningfully, especially in markets carrying unsold inventory where developers push offers to clear stock. We track these cycles in our post on festive season home buying in 2026. And if you're in the NCR belt, upcoming metro and expressway corridors are actively reshaping values; our analysis of infra projects reshaping NCR home prices is worth reading before you lock a location.
A weekend checklist before you decide
Work through this before you talk to a single sales agent.
- Calculate your city's price-to-income ratio using your own household income and your target property's real price.
- Compute the rental yield of your target area: annual rent divided by property price.
- Run the buy-versus-rent comparison over your honest holding period, including all hidden costs.
- Check your EMI-to-income ratio at current interest rates. Keep it under 40%.
- Confirm your down payment and registration cash is separate from your emergency fund.
- Get pre-approved so you know your real borrowing limit before you fall in love with a flat.
- Shortlist ready-to-move over under-construction unless the discount genuinely offsets the GST and delay risk.
If you're weighing options across cities or want a shortlist that matches your budget and yield criteria, browse verified listings for properties for sale in India or explore rental properties to lock a good rent while you keep saving. Our advisors can also help you talk through your specific numbers without pushing a sale.
Frequently Asked Questions
What is a good home price to income ratio in India?
A ratio of 3 to 4 is considered affordable, 5 is manageable for stable dual-income households, and anything above 7 is stretched. Most Indian metros sit between 5 and 8.5 in 2026, with Mumbai and Delhi NCR at the higher end and Pune and Hyderabad more moderate.
Is it better to rent or buy a house in India in 2026?
It depends on your holding period and local rental yield. If you'll stay seven years or more and yields are above 3.5%, buying usually wins. For shorter horizons in low-yield cities like Mumbai, renting and investing the difference often produces a better financial outcome, provided you actually invest that difference.
How much down payment do I need for a home loan in India?
Lenders typically finance up to 80% of the property value, so plan for a 20% down payment plus stamp duty and registration of another 5–7%. On a ₹1 crore property that's roughly ₹25–27 lakh in cash before you even touch loan EMIs.
Do I pay GST when buying a flat in India?
You pay 5% GST on under-construction non-affordable housing and 1% on affordable units, with no input tax credit passed to buyers. Ready-to-move properties that have received a completion certificate attract no GST at all, which can save several lakh rupees.
Will home prices in India fall in 2026?
A sharp nationwide correction is unlikely given firm construction costs and steady demand in established corridors. Individual micro-markets with heavy unsold inventory may see stagnation or modest discounts, especially during festive quarters, but broad price declines are not the base-case expectation.
How does interest rate affect home affordability?
Significantly. A 1% change in the rate on a ₹1 crore, 20-year loan shifts your EMI by roughly ₹6,000 a month and over ₹15 lakh across the full tenure. A softening rate cycle improves affordability more than a small price correction would.
Should I register the property in my spouse's name?
If your state offers a stamp duty rebate for female buyers, registering in a woman's name or as joint owners can save 1–2% of the property value. Delhi, UP, and Haryana all offer such concessions, so check your state's current policy before registration.
The bottom line
The home price to income ratio India 2026 tells you the market is genuinely stretched, but a stretched market doesn't mean you personally should wait, and a moderate one doesn't mean you should rush. The right answer comes from your own numbers: your holding period, your local rental yield, your EMI-to-income ratio, and whether you have the down payment sitting ready without raiding your safety net.
Run the math honestly. Buy when the conditions line up and the property is one you'll actually keep for years. Rent and invest when the yields are thin and your horizon is short, but only if you have the discipline to genuinely invest the difference. Either way, decide from a spreadsheet and a checklist, not from the fear that you're being left behind.
When you're ready to move from analysis to action, eDarpan Properties can help you find and vet the right home, compare buy and rent options, and connect the financing dots. Reach out and we'll run your specific affordability numbers with you before you commit a single rupee.
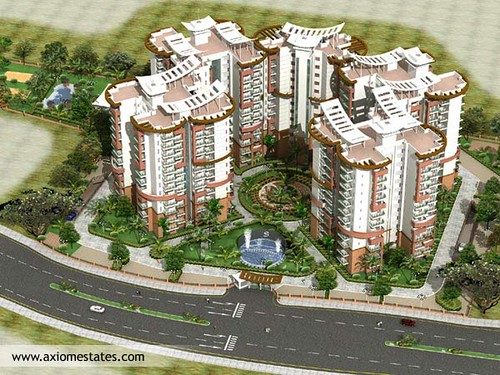
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Capital Gains Tax on Property Sale in India 2026: Save Legally
A retiree saved ₹19 lakh legally by choosing the right method. Learn how capital gains tax on property sale in India works in 2026 and where the real savings hide.
NRI Property Buying in India 2026: Rules, Taxes & Repatriation
NRI property buying in India made clear: FEMA rules, NRE/NRO accounts, TDS math, home loans, and how to repatriate sale proceeds without losing money.
Home Loan Balance Transfer in India 2026: Save Lakhs on EMIs
A 0.75% rate drop on a ₹50 lakh loan saves ₹5.2 lakh. Here's when a home loan balance transfer is worth it, the hidden charges, and the break-even math.