NRI Property Buying in India 2026: Rules, Taxes & Repatriation
NRI property buying in India made clear: FEMA rules, NRE/NRO accounts, TDS math, home loans, and how to repatriate sale proceeds without losing money.
Every few weeks I get the same phone call. It's usually a Friday evening, and on the other end is an NRI in Dubai or New Jersey who just wired ₹80 lakh to a builder in Pune, only to discover their bank flagged the transaction, the TDS wasn't deducted correctly, and now they're panicking about whether they'll ever get their money back out of India if they decide to sell. The property part was easy. The plumbing behind it — FEMA compliance, the right bank account, the TDS math, the repatriation paperwork — is where things fall apart.
Here's a number that surprises most people: the RBI's own rules let you repatriate proceeds from the sale of up to two residential properties, and beyond that you're capped at USD 1 million per financial year under the general permission route. Miss the documentation, and you can be sitting on rupees you literally cannot move abroad. I've seen a family wait 14 months to untangle a botched repatriation because nobody kept the original inward remittance advice from the purchase.
This guide walks through NRI property buying in India the way I'd brief a client: what you're legally allowed to buy, which bank accounts matter, how TDS actually works on both purchase and sale, how home loans function for non-residents, and the exact steps to get your money back home cleanly. No theory. Real numbers, real timelines.
Key Takeaways
- NRIs and OCIs can freely buy residential and commercial property in India, but cannot buy agricultural land, farmhouses, or plantation property without RBI approval.
- All payments must route through your NRE, NRO, or FCNR account — never foreign currency cash, never a resident savings account.
- When you sell, the buyer must deduct TDS at ~20% plus surcharge and cess on long-term gains (effectively up to 23.92%), not the 1% that applies to resident sellers.
- Repatriation of sale proceeds is capped at USD 1 million per financial year from your NRO account, and you'll need Forms 15CA and 15CB signed by a CA.
- Keep every inward remittance certificate (FIRC) from your original purchase — repatriation of principal depends on proving funds came from abroad.
- A lower TDS certificate under Section 197 can save you lakhs in locked-up cash at sale time; apply before the transaction closes.
What can an NRI legally buy in India under FEMA?
Let's clear the biggest confusion first. Under FEMA and RBI's general permission, an NRI or OCI cardholder can buy any number of residential and commercial properties in India. No prior approval, no limit on quantity. You can own a flat in Bengaluru, a shop in Surat, and an office in Gurgaon simultaneously.
What you cannot buy under general permission:
- Agricultural land
- Plantation property
- Farmhouses
These require specific RBI approval, which is rarely granted. You can, however, inherit such property from a resident. A common workaround people ask about — buying agricultural land through a resident relative's name — is a benami transaction and is illegal. Don't do it. The penalties under the Benami Transactions Act include confiscation of the property and prosecution.
Foreign nationals who are not of Indian origin (no OCI, no PIO) generally cannot buy property in India except on a lease of up to five years, so this guide assumes you hold NRI or OCI status.
If you're still deciding on the property itself, browse verified listings for properties for sale in India or explore the full eDarpan Properties platform where we help NRIs shortlist and vet projects before they commit funds.
Which bank account do you need — NRE, NRO or FCNR?
This is where 90% of the mistakes start. The account you pay from determines how easily you can pull money out later. Get this right on day one.
| Feature | NRE Account | NRO Account | FCNR (B) Account |
|---|---|---|---|
| Currency held | Indian Rupees | Indian Rupees | Foreign currency (USD, GBP, etc.) |
| Source of funds | Foreign earnings only | Indian income (rent, dividends) + foreign | Foreign earnings only |
| Repatriable? | Fully repatriable | Up to USD 1M/year with paperwork | Fully repatriable |
| Interest taxable in India? | No | Yes (TDS applies) | No |
| Best for | Buying with foreign funds you'll want back | Rental income, sale proceeds of resident-era property | Parking foreign currency without exchange risk |
The practical rule: if you're bringing money from abroad to buy, route it through your NRE account. Funds that come in through NRE are fully and easily repatriable later. Rental income you collect goes into your NRO account. When you eventually sell, sale proceeds typically land in the NRO account and repatriate from there subject to limits.
Common Mistake: A client in Singapore paid a builder's booking amount directly from his overseas Citibank account to the builder's account. The builder accepted it, but there was no FIRC (Foreign Inward Remittance Certificate) generated in his name in India, because it didn't pass through his own NRE account. Years later, proving that ₹22 lakh came from abroad became a documentation nightmare. Always move foreign funds into your own NRE account first, then pay the builder from there. The paper trail is everything.
How does TDS work when an NRI buys — and sells — property?
People confuse the two directions of TDS, so let's separate them cleanly.
When you buy from a resident seller
If you buy a property worth ₹50 lakh or more from a resident Indian, you (the buyer) must deduct 1% TDS under Section 194-IA and deposit it using Form 26QB. Simple. This is the same rule that applies to resident buyers.
When you buy from another NRI seller
This is the trap. If the seller is an NRI, Section 194-IA does not apply. Instead, Section 195 kicks in, and the buyer must deduct TDS on the capital gains at a much higher rate — effectively up to 23.92% for long-term gains (20% base plus surcharge and 4% cess), and at slab rates for short-term. As the buyer you need a TAN (Tax Deduction Account Number) to do this, and you file Form 27Q, not 26QB.
Before you sign anything, confirm the seller's residential status in writing. Getting this wrong makes you, the buyer, liable for the shortfall plus interest.
When you sell (you're the NRI seller)
Here's the pain most NRIs don't budget for. When you sell, the buyer is legally required to deduct TDS on the full sale consideration at the higher NRI rate — up to 23.92% on the sale value if long-term. On a ₹1 crore sale, that's roughly ₹24 lakh locked up with the tax department until you file your return and claim a refund.
The fix: apply for a Lower/Nil TDS certificate under Section 197 before the sale. The Assessing Officer computes your actual capital gain and issues a certificate directing the buyer to deduct TDS only on the real gain, not the whole sale price. On the same ₹1 crore sale with an actual gain of ₹20 lakh, TDS drops from ~₹24 lakh to under ₹5 lakh. That's the difference between having your money and chasing a refund for 18 months.
Pro Tip: Start the Section 197 application at least 4 to 6 weeks before your expected closing date. The AO can ask for the sale agreement, purchase deed, indexation working, and improvement receipts. If you scramble at the last minute, the buyer deducts the full TDS and you lose the leverage entirely.
Can NRIs get a home loan in India, and what does it cost?
Yes, and the process is more streamlined than most expect. SBI, HDFC, ICICI, Axis, and LIC Housing Finance all run dedicated NRI home loan desks. You can typically finance up to 75–80% of the property value, with the balance funded from your own remittance.
Key differences from a resident loan:
- Tenure is usually shorter — often capped at 20–25 years and tied to your age at retirement.
- EMIs must be paid from your NRE or NRO account, or through inward remittance. You cannot service the loan from a foreign account directly.
- Documentation is heavier — employment contract, work permit/visa, overseas salary slips, and often a Power of Attorney given to a resident relative to handle registration in your absence.
- Interest rates are broadly the same as resident rates, currently in the 8.3% to 9.5% range depending on the lender and your profile.
The repatriation angle matters here too. If you repay the loan from your NRE account (foreign funds), the principal you paid can be repatriated later. If you service it from NRO income, repatriation is subject to the USD 1 million cap.
If you already hold a home loan and rates have moved, it's worth reading our breakdown on home loan balance transfer to save lakhs on EMIs before you refinance — the same principles apply to NRI borrowers.
A worked example: NRI buying and selling in Pune
Let me make this concrete. Rohan is an NRI software engineer in Dublin. In 2019 he bought a 2BHK in Hinjewadi, Pune, for ₹65 lakh. Here's how the money moved and what happened when he sold in early 2026 for ₹1.1 crore.
Purchase (2019):
- Rohan remitted ₹20 lakh from his Irish salary into his NRE account with HDFC. The bank issued an FIRC. He filed this away carefully.
- He took a ₹45 lakh NRI home loan from HDFC at 8.6%, serviced by monthly transfers from Dublin into his NRE account.
- He deducted 1% TDS (₹65,000) via Form 26QB, since the seller was a resident.
- He registered the property using a Power of Attorney given to his brother in Pune, saving a trip home.
Sale (2026):
- The sale price was ₹1.1 crore. Indexed cost of acquisition worked out to roughly ₹82 lakh, giving a long-term capital gain of about ₹28 lakh.
- Without action, the buyer would have deducted TDS on the full ₹1.1 crore at 20%+surcharge+cess — over ₹26 lakh locked up.
- Rohan's CA applied for a Section 197 lower TDS certificate six weeks before closing. The AO certified TDS on the ₹28 lakh gain instead. Effective TDS: about ₹6.7 lakh.
- Sale proceeds landed in his NRO account. To repatriate, his CA filed Form 15CB (a certificate confirming taxes were paid) and Rohan filed Form 15CA online.
- Because his original ₹20 lakh came in through NRE (proven by that saved FIRC), that portion repatriated cleanly. The rest fell within his USD 1 million annual limit.
The single decision that saved Rohan nearly ₹20 lakh in trapped cash was applying for the Section 197 certificate early. The single document that saved him months of hassle was keeping the FIRC from 2019.
How do you actually repatriate the sale proceeds?
This is the step everyone worries about and few understand. Here's the sequence.
- Confirm your limits. Sale proceeds of up to two residential properties are repatriable if bought with foreign funds. Beyond that, and for NRO-sourced money, you're within the USD 1 million per financial year ceiling.
- Pay your capital gains tax (or get the Section 197 certificate) so the funds are tax-cleared.
- Get Form 15CB from a Chartered Accountant. This certifies the nature of the remittance and that applicable taxes have been deducted.
- File Form 15CA on the income tax portal yourself, referencing the 15CB.
- Submit to your bank — 15CA, 15CB, the sale deed, purchase deed, proof of TDS, and your FIRC for the original purchase. The bank processes the outward remittance from your NRO account.
- Repatriate within the FY window. The USD 1 million limit resets each April.
Timeline: once your documents are in order, banks typically process the outward remittance in 3 to 10 working days. The delay is almost never the bank — it's getting the CA certificate and tax clearance sorted.
Where eDarpan fits into NRI property buying in India
Buying from 7,000 km away means you're trusting people you can't physically supervise. That's exactly where we help. eDarpan's real estate platform lets NRIs shortlist vetted properties for sale and even rental properties if you're building a portfolio to earn Indian rental income.
Beyond listings, our IT and advisory consulting team frequently works with NRI clients who need a reliable Indian-side presence — from setting up a virtual office address for GST and company registration if you're structuring property purchases through an entity, to building custom software for those managing multiple rental units remotely. If you want to talk through your specific situation before wiring a single rupee, get in touch with the eDarpan team.
For market context on where to buy, our recent analysis on metro and infra projects reshaping NCR home prices and whether the Greater Noida builder rush is a buy signal are both worth a read.
Frequently Asked Questions
Can an NRI buy property in India without coming to India?
Yes. You can execute the entire purchase through a registered Power of Attorney given to a trusted resident, usually a family member. The PoA must be notarized abroad and adjudicated in India. Most NRIs complete registration this way without ever flying down.
Do NRIs pay higher stamp duty than residents?
No. Stamp duty and registration charges are levied by the state and depend on the property value and location, not your residential status. In Maharashtra it's around 5–6%; in Karnataka roughly 5–5.6%. An NRI pays the same rate as a resident buyer in that state.
How much money can an NRI repatriate from selling property in India?
Sale proceeds of up to two residential properties bought with foreign funds are repatriable. For amounts held in an NRO account or beyond those two properties, the limit is USD 1 million per financial year, subject to tax clearance and Forms 15CA/15CB.
Is rental income earned by an NRI in India taxable?
Yes. Rental income from Indian property is taxable in India regardless of where you live. The tenant or property manager should deduct TDS at 30% (plus surcharge and cess) before paying you, though you claim standard deductions and can file a return to recover any excess.
What is the TDS rate when a buyer purchases property from an NRI?
For long-term capital gains, TDS under Section 195 is effectively up to 23.92% (20% plus surcharge and cess) on the gain, or on the full sale value if no lower deduction certificate is obtained. Short-term gains are taxed at the seller's applicable slab rate. The buyer needs a TAN and files Form 27Q.
Can an NRI use an OCI card to buy agricultural land?
No. Neither NRIs nor OCI cardholders can buy agricultural land, plantation property, or farmhouses under RBI's general permission. They can only acquire such property through inheritance from a resident, or with specific RBI approval which is rarely granted.
Do I need a PAN card to buy property in India as an NRI?
Yes, a PAN is mandatory for property transactions, TDS filings, and to file your income tax return in India. Apply for one before you begin the purchase — it's needed at nearly every step, including the sale and repatriation later.
Final word
NRI property buying in India is far more manageable than the horror stories suggest, but only if you respect the sequence: right bank account first, clean documentation always, and the Section 197 certificate before you sell. The people who get burned are almost never the ones who overthought it — they're the ones who wired money before understanding how they'd get it back.
Keep every FIRC, route foreign funds through your NRE account, budget for the higher NRI TDS at sale, and start your repatriation paperwork early. Do that, and your Indian property becomes a genuine asset rather than a compliance headache. When you're ready to shortlist a property or need someone on the ground to help you vet it, reach out to eDarpan — we've walked this path with enough NRI clients to keep you out of the traps.
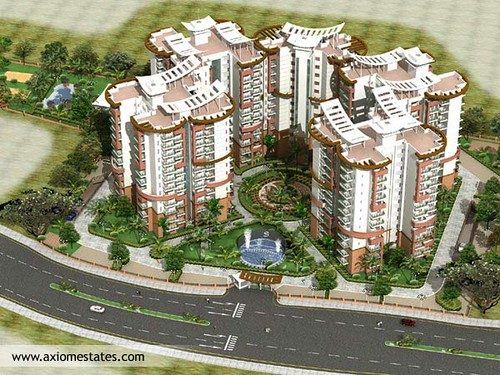
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Home Loan Balance Transfer in India 2026: Save Lakhs on EMIs
A 0.75% rate drop on a ₹50 lakh loan saves ₹5.2 lakh. Here's when a home loan balance transfer is worth it, the hidden charges, and the break-even math.
Rent Agreement Registration in India 2026: A Tenant & Landlord Guide
Confused about the 11-month rule, e-stamping, and registration? Here's a practical tenant and landlord guide to rent agreements in India for 2026.
Festive Season Home Buying 2026: Deals Amid Unsold Inventory
With 10-11 lakh unsold units across metros, festive season home buying 2026 hands buyers real leverage. Here's your negotiation playbook.