Home Loan Balance Transfer in India 2026: Save Lakhs on EMIs
A 0.75% rate drop on a ₹50 lakh loan saves ₹5.2 lakh. Here's when a home loan balance transfer is worth it, the hidden charges, and the break-even math.
Here's a number that should bother anyone paying a home loan EMI right now: on a ₹50 lakh loan running at 9.4% for 20 years, dropping your rate by just 0.75% saves you roughly ₹5.2 lakh over the remaining tenure. Most borrowers never do the math. They set up an ECS mandate, forget about it, and quietly overpay their bank for two decades.
The gap between what old borrowers pay and what new borrowers get offered has widened sharply. Banks compete aggressively for fresh loans, so a customer walking in today might get 8.35% while a loyal three-year customer still sits at 9.5% on the same product. That difference is pure margin the lender keeps because you didn't ask. A home loan balance transfer 2026 is simply the act of moving your outstanding loan to another lender who's willing to charge you less, and when done right it's one of the highest-return financial moves an Indian household can make in a single afternoon of paperwork.
I've helped clients — small business owners, salaried professionals, a few NRIs — run these transfers over the years. Below is the honest version: when it's worth it, when it isn't, the charges nobody tells you about upfront, the break-even math, and a paperwork checklist you can hand to any bank relationship manager.
Key Takeaways
- A balance transfer usually makes sense only if your rate gap is 0.5% or more and you have at least 8-10 years of tenure left.
- The real cost isn't the interest — it's processing fees (0.25%-0.5%), legal/valuation charges, stamp duty on the new mortgage, and CERSAI fees. Add them up before you sign.
- Floating-rate home loans in India carry zero foreclosure/prepayment penalty for individuals per RBI rules. Fixed-rate loans may not.
- Calculate your break-even in months. If you recover switching costs within 18-24 months and plan to hold the loan longer, transfer. Otherwise, renegotiate instead.
- Always ask your current lender for a rate reduction first — many will drop your rate for a small conversion fee rather than lose you.
- Bundle a top-up loan into the transfer only if you actually need funds; don't inflate your principal for a marginally better rate.
What exactly is a home loan balance transfer, and how does it work?
A balance transfer (banks call it BT) means the outstanding principal on your existing home loan is paid off by a new lender, and you start repaying that new lender at a lower interest rate. Your original loan closes. The property's mortgage lien shifts from Bank A to Bank B.
Mechanically it looks like this: the new lender sanctions a loan equal to your current outstanding, issues a cheque or NEFT directly to your old lender, collects your original property documents from the old bank, and re-registers the mortgage in its own favour. You never touch the money. Your EMI simply starts going to a new account.
The catch is that this is effectively a fresh loan application. The new bank runs your CIBIL score again, re-verifies your income, re-values the property, and does fresh legal due diligence on the title. That's why the process takes 15-25 working days and comes with a cluster of one-time charges. Understanding those charges is the whole game.
When is a home loan balance transfer actually worth it in 2026?
Not every rate difference justifies the effort. I use three filters before recommending a transfer to anyone.
1. The rate gap
If the new offer is 0.5% lower or more, it's worth investigating. Below 0.5%, the switching costs usually eat most of your savings. A 1% or larger gap almost always justifies moving.
2. Remaining tenure
Interest savings from a lower rate are front-loaded — the early years of an EMI are mostly interest. If you're in year 17 of a 20-year loan, most of your interest is already paid and a transfer buys you almost nothing. The sweet spot is when you still have 8 years or more left.
3. Outstanding principal size
On a ₹12 lakh outstanding balance, even a 0.75% saving is modest in absolute terms and may not clear the fixed switching costs. On ₹40 lakh plus, the same percentage becomes serious money.
Pro Tip: Before you approach a new bank, call your existing lender's loan department and say plainly: "I have a lower offer from [competitor] at X%. Can you match it?" Most banks and HFCs have a rate conversion or rate reset facility where, for a fee of roughly 0.25% of outstanding (often capped), they'll bring your rate close to the market. This costs a fraction of a full transfer and takes three days instead of three weeks. I've seen HDFC, ICICI and SBI all do this to retain customers. Try this first — always.
The hidden charges nobody puts in the brochure
The advertised rate is the headline. The costs below are the fine print, and they determine whether a transfer actually saves you money.
- Processing fee: 0.25% to 0.50% of the loan amount, plus 18% GST on the fee. On a ₹40 lakh transfer that's ₹10,000-₹20,000 plus GST. Negotiable, and often waived during festive campaigns.
- Legal and technical valuation charges: ₹3,000-₹8,000 for the new lender's lawyer to verify title and their engineer to value the property.
- Stamp duty on the new mortgage deed: varies by state. In Maharashtra it can run 0.2%-0.3% of the loan; in some states it's nominal. This is a real cost people forget.
- CERSAI charges: a small statutory fee (₹50-₹100) for registering the security interest.
- MODT / equitable mortgage registration: Memorandum of Deposit of Title Deeds charges, again state-dependent, sometimes a few thousand rupees.
- Foreclosure charges from your old lender: For floating-rate loans to individuals, RBI mandates zero prepayment/foreclosure penalty. If your old bank tries to charge you, quote the RBI circular. Fixed-rate loans are a different matter.
Common Mistake: Borrowers compare only the interest rate and ignore that the new lender resets the tenure. A bank offering a lower EMI is often just stretching your loan back out to 20 years. Lower EMI, but you pay interest for longer. Always compare on total interest outgo over the same tenure, not on EMI alone. Insist on keeping your remaining tenure the same.
Break-even math: a real worked example
Let me walk through an actual case (details anonymised). A Pune-based couple, both salaried, had a home loan with an HFC. Here were their numbers in early 2026:
- Outstanding principal: ₹42,00,000
- Current rate: 9.55%, remaining tenure 16 years
- Current EMI: approximately ₹39,300
- New offer from a public sector bank: 8.55% (1% lower), same 16-year tenure
At 8.55% on the same ₹42 lakh over 16 years, the new EMI drops to roughly ₹36,850 — a saving of about ₹2,450 per month, or ₹29,400 a year. Over the full remaining 16 years, keeping tenure constant, the total interest saved works out to roughly ₹4.7 lakh.
Now the switching costs:
| Charge | Amount (₹) |
|---|---|
| Processing fee (0.35% + GST) | 17,346 |
| Legal + technical valuation | 6,000 |
| Stamp duty / MODT (Maharashtra) | 10,500 |
| CERSAI + misc | 1,200 |
| Foreclosure penalty (floating rate) | 0 |
| Total one-time cost | 35,046 |
Break-even: ₹35,046 ÷ ₹2,450 monthly saving = about 14.3 months. They recover every rupee of switching cost in just over a year, then bank ₹2,450 a month for the next 15 years. Clear decision. They transferred.
Contrast that with a client in year 15 of a ₹9 lakh outstanding loan chasing a 0.4% drop. His monthly saving was around ₹180 and switching costs were ₹22,000. Break-even: over 10 years. That's a no. We had him renegotiate a rate reset with his existing bank for ₹2,500 instead.
Balance transfer vs rate reset vs top-up: which route fits you?
These three options solve different problems. Choosing wrong wastes money.
| Option | Best when | Typical cost | Time |
|---|---|---|---|
| Rate reset (same bank) | Your bank will match market rates; small gap | 0.25% conversion fee or flat ₹1k-5k | 2-5 days |
| Balance transfer (new bank) | Gap of 0.5%+, long tenure left, own bank won't budge | ₹25k-45k total on a ₹40L loan | 15-25 days |
| BT + top-up loan | You need extra funds (renovation, business) at home-loan rates | BT costs + higher rate on top-up portion | 15-30 days |
| Do nothing / prepay instead | Gap under 0.4%, or under 7 years left | Nil | — |
The top-up angle is worth a note. If you run a business and need working capital, a home loan top-up at 8.5-9% is dramatically cheaper than an unsecured business loan at 14-18%. Many MSME owners use a balance transfer moment to also pull out a top-up for GST-linked cash flow gaps or expansion. If you're setting up a new business entity and need a registered address for that, a compliant virtual office address for GST and company registration can be a cleaner path than committing to commercial rent while your finances are in flux.
Step-by-step: how to execute a home loan balance transfer
Here's the sequence I give clients. Follow it in order and you'll avoid the delays that stretch a three-week process into three months.
- Pull your latest loan statement and outstanding certificate from your current lender. Note the exact outstanding principal, current rate, and remaining tenure.
- Check your CIBIL score. Anything above 750 gets you the best rates. If it's dipped, fix it before applying — a low score means the "lowest advertised rate" won't apply to you.
- Get written offers from 2-3 lenders. Include at least one public sector bank (usually cheapest) and one private/HFC (faster processing). Ask for the sanction rate in writing, not a verbal "around 8.5%".
- Go back to your existing lender with those offers and ask for a rate reset. If they match within 0.2%, stay — it's cheaper.
- Submit the transfer application to your chosen new lender with income proof, KYC, existing loan statement, and property documents (which are with your old bank; the new bank collects them via a foreclosure/list-of-documents letter).
- New lender runs legal and technical verification. Their lawyer checks the title chain; their valuer inspects the property. This is the slowest step — chase it.
- Sanction and disbursement. The new lender issues a demand draft or NEFT to your old lender for the exact outstanding amount.
- Old loan closes; documents transfer. Your original property papers move from the old bank to the new one. Get an acknowledgement of the document list.
- Register the new mortgage (MODT/equitable mortgage) and pay stamp duty. New ECS/NACH mandate goes live for your revised EMI.
- Collect your No Objection Certificate (NOC) and loan closure letter from the old lender. File these. You'll need the closure proof for your records and any future property sale.
Pro Tip: Time your application away from the old bank's rate-reset cycle. If your existing loan is due for a downward reset in the next month (which happens when the repo rate falls and your bank passes it on), wait — you might get a lower rate automatically with zero paperwork. Ask your bank when your next reset date is.
How balance transfers connect to smart property decisions in 2026
A balance transfer isn't just a cost-cutting tactic; it's part of managing property as an asset. If you're refinancing a home you intend to hold, freeing up ₹2,000-₹5,000 a month in EMI is capital you can redirect — into a systematic prepayment, into a second property, or into your business.
Buyers watching the market should also read our take on the festive season home buying deals amid unsold inventory and how metro and infrastructure projects are reshaping NCR home prices — both affect whether refinancing to hold, or selling and rebuying, makes more sense. If you're evaluating fresh purchases, the analysis on whether the Greater Noida builder rush is a buy signal and on construction costs rising 34% and its impact on buyers are worth your time before you commit new EMIs.
If you're actively in the market, browse verified properties for sale across India or rental listings on eDarpan Properties. Landlords sorting out tenancy paperwork alongside their loan should also see our guide to rent agreement registration for tenants and landlords.
Frequently asked questions
Does a home loan balance transfer hurt my CIBIL score?
There's a small, temporary dip when the new lender runs a hard enquiry, and your old loan showing as "closed" can briefly affect the picture. Within a few months of on-time EMIs on the new loan, the score recovers and often improves. It's not a reason to avoid a worthwhile transfer.
Are there prepayment or foreclosure charges when I transfer a floating-rate home loan?
No. RBI rules prohibit banks and HFCs from levying foreclosure or prepayment penalties on floating-rate home loans taken by individual borrowers. If your existing lender tries, cite the RBI directive in writing. Fixed-rate loans can carry charges, so check your loan agreement.
How long does a home loan balance transfer take in India?
Typically 15-25 working days from application to disbursement. The slowest stages are the new lender's legal and technical verification and the physical transfer of your original property documents from the old bank. Chasing both actively can compress this.
Can I get a top-up loan during a balance transfer?
Yes, most lenders offer a top-up over and above your outstanding balance at, or slightly above, the home loan rate. It's a cheap source of funds compared to personal or business loans. Only borrow what you genuinely need — the top-up increases your principal and total interest.
Is it better to transfer my loan or just prepay the principal?
They aren't mutually exclusive. If you have surplus cash, prepaying reduces principal and interest immediately with no switching cost. If your rate is well above market and you plan to hold the loan for years, transfer first, then prepay on the lower rate for maximum effect.
What documents do I need for a home loan balance transfer?
KYC (Aadhaar, PAN), income proof (salary slips and Form 16 for salaried; ITRs and financials for self-employed), last 12 months' bank statements, your existing loan statement and sanction letter, and the property documents (the new lender collects the originals from your old bank). Keep digital copies of everything.
Should I transfer if I only have 6-7 years left on my loan?
Usually not. Interest is front-loaded, so most of the interest on a short remaining tenure is already behind you. The one-time switching costs will likely wipe out the savings. Prepaying or a cheap same-bank rate reset is almost always the better move at that stage.
The bottom line
A home loan balance transfer 2026 is one of the rare financial moves where a single afternoon of effort can put lakhs back in your pocket over the life of a loan. But it only works when the math works: a rate gap of 0.5% or more, enough tenure left, a large enough outstanding balance, and switching costs you recover inside 18-24 months. Do the break-even calculation with real numbers, not the marketing brochure. And always ask your existing bank to match before you leave — the cheapest saving is often the one that needs no paperwork at all.
At eDarpan we work with SMB owners and property buyers on the full picture — from IT and financial process consulting to real estate advisory. If you're weighing a refinance against a property purchase, or need help structuring finances for a growing business, get in touch with our team or explore our full range of services. You can also learn more about how we work. The right advice at the right moment is what turns a good decision into a great one.
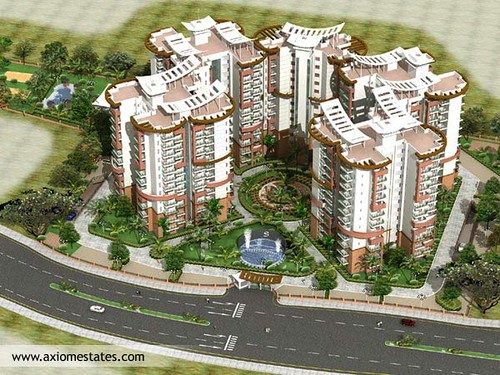
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Rent Agreement Registration in India 2026: A Tenant & Landlord Guide
Confused about the 11-month rule, e-stamping, and registration? Here's a practical tenant and landlord guide to rent agreements in India for 2026.
Festive Season Home Buying 2026: Deals Amid Unsold Inventory
With 10-11 lakh unsold units across metros, festive season home buying 2026 hands buyers real leverage. Here's your negotiation playbook.
Metro & Infra Projects Reshaping NCR Home Prices 2026
Learn how metro corridors, expressways, and Jewar Airport are reshaping NCR home prices in 2026, plus a framework to time your entry for maximum gains.