Capital Gains Tax on Property Sale in India 2026: Save Legally
A retiree saved ₹19 lakh legally by choosing the right method. Learn how capital gains tax on property sale in India works in 2026 and where the real savings hide.
Last November, a retired schoolteacher in Pune sold his ancestral flat in Kothrud for ₹1.85 crore. He'd bought it in 2004 for ₹22 lakh. He walked into my office expecting a modest tax bill, maybe a few lakh. Instead, his first CA had computed a liability north of ₹28 lakh because he'd applied the new flat-rate rules without checking whether the old indexation method was cheaper. We ran both calculations. The correct answer, using the grandfathering option the government left in place, brought his tax down to under ₹9 lakh. That single afternoon saved him nearly ₹19 lakh, legally.
This is the reality of capital gains tax on property sale India in 2026. The July 2024 Budget rewired the entire framework, and most sellers still don't understand what changed, what protections survived, and where the genuine savings sit. The rate dropped from 20% to 12.5%, but indexation was scrapped for most assets. That sounds like a fair trade until you run the numbers on a property held for 20 years, where indexation was doing serious heavy lifting.
In this post I'll walk you through the actual rules for long-term and short-term gains, the indexation grandfathering that protects older properties, and the three exemptions under Sections 54, 54F, and 54EC that let you defer or eliminate tax entirely. Real numbers, real timelines, and the mistakes I see people make every quarter.
Key Takeaways
- LTCG on property (held over 24 months) is now taxed at 12.5% without indexation, but properties bought before 23 July 2024 can choose the old 20% with indexation method — pick whichever gives lower tax.
- STCG (held 24 months or less) is added to your income and taxed at your slab rate, up to 30% plus surcharge and cess.
- Section 54 exempts LTCG if you reinvest in another residential house; Section 54EC exempts up to ₹50 lakh via NHAI/REC bonds within 6 months.
- Missing the reinvestment window means you park funds in a Capital Gains Account Scheme before your ITR filing deadline, or lose the exemption.
- TDS of 1% applies on property sales above ₹50 lakh; for NRI sellers it jumps to 20%+ under Section 195.
- Always compute both indexed and non-indexed liability before signing anything. The gap is often several lakh.
What counts as capital gains on a property sale, and how are they classified?
Capital gains are simply the profit you make when you sell a capital asset for more than you paid for it. For real estate, the asset is your land, flat, plot, or commercial unit. The tax you owe depends on one thing above all: how long you held it.
The holding period rules for property were simplified in 2024. Here's where it stands:
- Short-Term Capital Gain (STCG): You held the property for 24 months or less. The gain is added to your total income and taxed at your applicable slab rate.
- Long-Term Capital Gain (LTCG): You held the property for more than 24 months. This is where the favourable rates and exemptions kick in.
The holding period is counted from the date of acquisition (usually your registered sale deed or allotment date) to the date of transfer. For inherited property, you inherit the previous owner's holding period too, which is a big advantage most people forget.
How the cost of acquisition works
Your gain isn't just sale price minus purchase price. You get to deduct:
- The original purchase cost (or indexed cost, if eligible)
- Cost of improvements (renovation, adding a floor, registered structural work)
- Transfer expenses: brokerage, legal fees, stamp duty on the sale side
Keep every receipt. I've seen ₹6 lakh of legitimate renovation costs disallowed simply because the client paid the contractor in cash with no invoice. If you're planning to sell, digitise your paper trail now.
How is LTCG on property taxed in 2026 after the indexation change?
This is the section everyone gets wrong. Before 23 July 2024, LTCG on property was taxed at 20% with indexation, meaning your purchase cost was inflated using the Cost Inflation Index (CII) to account for rupee depreciation over the years. That indexed cost dramatically reduced your taxable gain.
The 2024 Budget introduced a flat 12.5% rate without indexation. After public pushback, the government added a crucial relief: for land and buildings acquired before 23 July 2024, resident individuals and HUFs can choose whichever computation gives them lower tax:
- Option A: 12.5% flat, no indexation
- Option B: 20% with indexation (old method)
For properties bought after 23 July 2024, only the 12.5% flat rate applies. No choice.
Worked example: which option wins?
Let's take the Pune case I mentioned. Flat bought in FY 2004-05 for ₹22 lakh, sold in FY 2025-26 for ₹1.85 crore.
| Basis | Option A: 12.5% no indexation | Option B: 20% with indexation |
|---|---|---|
| Sale price | ₹1,85,00,000 | ₹1,85,00,000 |
| Cost of acquisition | ₹22,00,000 | Indexed: ~₹65,60,000 |
| Taxable capital gain | ₹1,63,00,000 | ~₹1,19,40,000 |
| Tax rate | 12.5% | 20% |
| Tax payable (before cess) | ₹20,37,500 | ~₹23,88,000 |
In this specific case, the 12.5% option actually wins by roughly ₹3.5 lakh, contrary to the assumption that indexation always helps. The old CA's ₹28 lakh figure was wrong because he'd mishandled the indexation calculation and ignored the exemptions we later applied. The lesson: the winning option depends on your holding period and how much the property appreciated relative to inflation. Properties that appreciated modestly benefit more from indexation; high-growth properties often favour the flat rate.
Common Mistake: Assuming indexation is always better. For properties held 15+ years in low-inflation-adjusted growth areas, indexation wins big. But for flats in cities like Bengaluru or Gurgaon that tripled or quadrupled in value, the flat 12.5% often produces lower tax. Run both. Every time.
How is STCG on property taxed, and why is it so painful?
If you sell within 24 months, there's no favourable rate and no exemption cushion. The entire gain gets bolted onto your income for the year.
Say you're a salaried professional in the 30% bracket who flipped a plot in Noida within 18 months for a ₹40 lakh gain. That ₹40 lakh pushes into your top slab. You could pay 30% plus surcharge plus 4% cess, easily crossing an effective 34-35%. That's ₹13-14 lakh gone, with no Section 54 relief available because those exemptions apply only to long-term gains.
The practical takeaway for property investors: timing your exit past the 24-month mark can save you enormous amounts. If you're a few months short, and there's no distress reason to sell, wait. I've advised clients to delay a sale by 90 days purely to convert STCG into LTCG, cutting their tax bill by more than half.
If you're actively trading property as a business rather than investing, the income may be treated as business income entirely, and you'd want proper structuring. This is exactly the kind of scenario where speaking to a proper IT and business consulting partner who understands compliance workflows pays for itself.
What are Sections 54, 54F, and 54EC, and how do they save tax?
These three exemptions are where legal tax savings actually happen. Understanding the difference matters because they apply in different situations.
Section 54: Sell a house, buy a house
If you sell a residential property (LTCG) and reinvest the gain in another residential property, you can claim exemption. The conditions:
- Buy the new house within 1 year before or 2 years after the sale, or construct within 3 years.
- The exemption is capped at the amount reinvested (or ₹10 crore, whichever is lower — a cap introduced in 2023).
- From FY 2019-20, you can invest in two houses if your gain is up to ₹2 crore, but only once in a lifetime.
Section 54F: Sell any asset, buy a house
This applies when you sell a non-residential long-term asset (a plot, gold, shares) and invest the entire net sale consideration in a residential house. The catch: it's the full sale proceeds, not just the gain, and you can't own more than one other residential house on the sale date.
Section 54EC: Park it in bonds
If you don't want to buy another property, you can invest your LTCG (from land or building) in specified bonds issued by NHAI or REC within 6 months of the sale. Key points:
- Maximum investment: ₹50 lakh per financial year.
- Lock-in period: 5 years.
- Interest rate is modest, around 5-5.25%, but the tax saved makes the effective return attractive.
What is the Capital Gains Account Scheme and when do I need it?
Here's the timing trap that catches thousands of sellers every year. You sold your property in, say, October 2025. Your ITR filing deadline is 31 July 2026. But you haven't found or completed the purchase of your new house yet.
You can't just keep the money in your savings account and claim the exemption later. To preserve your Section 54 or 54F exemption, you must deposit the unutilised gain into a Capital Gains Account Scheme (CGAS) at an authorised bank before your ITR due date.
Here's the practical walkthrough:
- Compute your exact exemption need. Know how much of your gain you're claiming under 54 or 54F.
- Open a CGAS account at a nationalised bank (SBI, PNB, Bank of Baroda offer this). Choose Type A (savings-style, flexible) or Type B (fixed deposit style).
- Deposit the unutilised amount before 31 July (or your extended due date).
- Withdraw only for the specified purpose — buying or constructing the new house — within the 2 or 3-year window.
- File Form C or D for withdrawals. If you don't use the money within the deadline, the balance becomes taxable in that year.
Pro Tip: Open the CGAS account at least two weeks before your filing deadline. Branch staff at many banks are unfamiliar with the scheme and the paperwork routinely gets delayed. I've had clients rush to a branch on 30 July only to be told the officer who handles CGAS is on leave. Don't cut it fine.
What about TDS on property sales and NRI sellers?
Whenever a property sells for ₹50 lakh or more, the buyer must deduct 1% TDS under Section 194-IA and deposit it via Form 26QB within 30 days of the month of payment. As a seller, you'll see this reflected in your Form 26AS and can claim credit against your final tax.
For NRI sellers, the rules are far stricter. TDS under Section 195 is deducted on the capital gain at 12.5% (plus surcharge and cess) for long-term, or at slab rates for short-term. Buyers often over-deduct because they're unsure, so NRIs should apply for a Lower Deduction Certificate (Form 13) from the assessing officer before the sale. We cover this in detail in our guide to NRI property buying and repatriation in India 2026.
If you're an NRI managing this remotely, the paperwork and coordination with the buyer's CA can be exhausting. Having a reliable local point of contact, or even a virtual office address for compliance and correspondence, makes a real difference.
How do I plan my property sale to minimise tax legally?
Let me give you the checklist I actually use when advising a client who's about to sell.
- Confirm the holding period. If you're within a few months of the 24-month LTCG threshold, evaluate whether waiting makes sense.
- Gather your cost documentation. Sale deed, improvement invoices, brokerage receipts. Digitise everything.
- Run both computations (12.5% flat vs 20% indexed) if the property predates 23 July 2024.
- Decide your exemption route. Reinvesting in a house (54/54F), bonds (54EC), or a combination.
- Plan the timeline. Map out the 6-month bond window and the 2-3 year reinvestment window against your ITR deadline.
- Set aside the TDS credit. Ensure Form 26QB is filed correctly by the buyer.
- Combine exemptions. You can use Section 54 for part of the gain and 54EC bonds (up to ₹50 lakh) for the rest — a common strategy for large gains.
If you're selling to fund a new home, it's worth checking whether the market timing works in your favour. Our analysis of home prices outpacing salaries in 2026 and the festive season buying environment amid unsold inventory can help you decide when to redeploy your proceeds.
Where does eDarpan fit into your property and business planning?
eDarpan isn't a tax firm, and I won't pretend otherwise. But a huge part of managing a property transaction well is having your documentation, communication, and compliance infrastructure in order. That's where we genuinely help.
For property investors and developers, we build the digital backbone: custom software to track your portfolio and rental income, mobile apps for tenant management, and WhatsApp Business API integrations so buyers and tenants get instant, verified communication. If you run a brokerage handling dozens of sale transactions, our AI voicebot and bulk SMS services keep clients updated on documentation deadlines automatically.
On the ownership side, if you're looking to reinvest your capital gains into a new home to claim Section 54, browse properties for sale across India or explore rental options through eDarpan Properties. And if your business needs its books and cloud systems tightened up before a big transaction, our cloud migration and managed services team keeps everything audit-ready.
Frequently Asked Questions
Is capital gains tax on property sale India applicable if I reinvest the entire amount?
If you reinvest the long-term gain into another residential property under Section 54 (or the full sale consideration under 54F for non-residential assets) within the prescribed windows, your capital gains tax can be fully exempted up to the reinvested amount, subject to the ₹10 crore cap. You must complete the purchase within 2 years, construction within 3 years, or park funds in a CGAS account before your ITR deadline.
What is the capital gains tax rate on property in India in 2026?
Long-term gains (property held over 24 months) are taxed at 12.5% without indexation. Properties acquired before 23 July 2024 can alternatively choose 20% with indexation, whichever is lower. Short-term gains are added to your income and taxed at your applicable slab rate.
Can I claim both Section 54 and Section 54EC exemptions together?
Yes. If you have a large gain, you can invest part of it in a new residential house under Section 54 and up to ₹50 lakh in NHAI or REC bonds under Section 54EC. This combination is a common and fully legal strategy for high-value property sales.
Do I still get indexation benefit on property bought in 2010?
Yes, if you're a resident individual or HUF and the property was acquired before 23 July 2024, you can choose the 20% with indexation method or the 12.5% flat rate, whichever results in lower tax. Always calculate both before filing.
How much TDS is deducted when I sell property above ₹50 lakh?
The buyer must deduct 1% TDS under Section 194-IA and deposit it using Form 26QB. This TDS is credited against your final tax liability. For NRI sellers, TDS is deducted under Section 195 at 12.5% plus surcharge and cess on long-term gains, often higher unless you obtain a Lower Deduction Certificate.
What happens if I don't reinvest before the ITR filing deadline?
You must deposit the unutilised capital gain in a Capital Gains Account Scheme (CGAS) at an authorised bank before your ITR due date to preserve the exemption. If you neither reinvest nor deposit in CGAS by then, the exemption is lost and the gain becomes fully taxable in that assessment year.
Is capital gains tax applicable on ancestral or inherited property?
Inheritance itself is not taxed. But when you sell inherited property, capital gains apply. You inherit the previous owner's holding period and cost of acquisition, which usually means the sale qualifies as long-term, giving you access to the favourable rates and Section 54 exemptions.
Final word
Managing capital gains tax on property sale India in 2026 isn't about finding loopholes. It's about knowing the rules the government actually gave you: the choice between indexation and the flat rate, the exemption windows under Sections 54 and 54EC, and the CGAS deadline that protects your relief. The difference between doing this right and doing it carelessly is often ten to twenty lakh, as that Pune teacher discovered.
Run both tax computations, keep your documentation airtight, and plan your reinvestment timeline before you sign the sale deed, not after. If you need help getting your business systems, communication, or property portfolio organised around a transaction, talk to the eDarpan team or explore our full range of services. Getting the infrastructure right is the part we're genuinely good at.
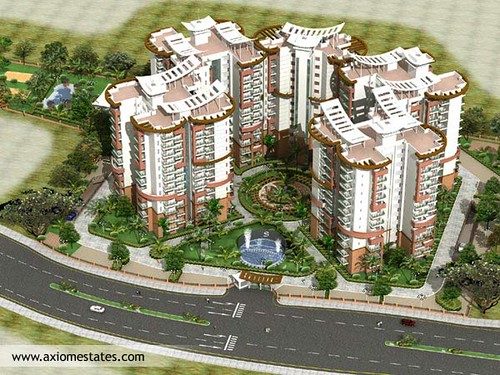
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Home Prices Outpacing Salaries in India 2026: Buy or Wait?
Homes in India cost 7-8x your salary while incomes crawl. Use our city-by-city framework to decide whether to buy now or wait two to three years.
NRI Property Buying in India 2026: Rules, Taxes & Repatriation
NRI property buying in India made clear: FEMA rules, NRE/NRO accounts, TDS math, home loans, and how to repatriate sale proceeds without losing money.
Home Loan Balance Transfer in India 2026: Save Lakhs on EMIs
A 0.75% rate drop on a ₹50 lakh loan saves ₹5.2 lakh. Here's when a home loan balance transfer is worth it, the hidden charges, and the break-even math.