Gurgaon, Noida Demand Dips 8-9%: Should You Buy Now or Wait?
NCR demand dipped 8-9%. Before you negotiate, learn what the slowdown really means for buyers and run the EMI and price-to-rent checks that matter most.
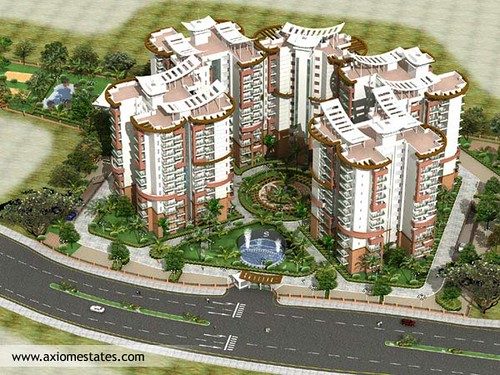
Your cousin just told you prices in Gurgaon have "finally cooled off," and your banker says the opposite. Meanwhile, the listing you liked two months ago is still on the portal, now with a 6% lower asking price and a broker calling every Tuesday. So the question is blunt: should I buy property in Noida or Gurgaon now, or is waiting the smarter move? Recent reporting pointed to an 8-9% dip in NCR housing demand, and that single number is being read in a dozen contradictory ways by people who have never had to sign a loan agreement.
Here is the thing most commentary skips. A demand dip is a signal about the next six to twelve months of negotiating leverage, not a verdict on whether the property you are looking at will still be worth what you paid in 2034. This post walks through what that dip actually tells you, a practical buy-now-or-wait framework you can run on a spreadsheet tonight, and the affordability checks that matter more than any headline. It is written for first-time buyers who need a place to live and for investors who are trying to avoid buying the wrong micro-market at the wrong moment.
Key Takeaways
- An 8-9% demand dip mostly shifts bargaining power toward buyers for 6-12 months. It rarely means prices crash in well-located, infrastructure-backed pockets.
- Separate end-user decisions from investment decisions. Your breakeven horizon and your EMI tolerance are different questions.
- Run the price-to-rent ratio and the EMI-to-income check before you talk to any broker. If either fails, waiting is usually the right answer regardless of market mood.
- Noida and Gurgaon are not one market. Sector-level supply pipelines, metro proximity, and builder delivery track records drive outcomes far more than the city label.
- Budget for the costs people forget: stamp duty, registration, GST on under-construction flats, society maintenance, and the EMI-versus-rent gap in the first five years.
- Negotiate on total landed cost and payment schedule, not just the headline rate per square foot.
What an 8-9% Demand Drop in NCR Actually Means for Buyers
Demand figures usually come from a mix of registrations, site visits, bookings, and sometimes enquiry data pulled from portals and developers. A fall of 8-9% over a quarter tells you that fewer people are committing money than before, relative to whatever baseline the report used. It does not tell you how many of those people were speculators, how many were genuine end users, or how much inventory is sitting unsold.
In practice, a soft patch like this tends to show up in three places first. Developers start offering payment-plan concessions, like a construction-linked plan with a longer first instalment or a small waiver on preferred location charges. Resale sellers who were anchoring at peak asking prices begin accepting offers five to eight percent below their original number. And brokers become noticeably more responsive, which is a useful tell about how the inventory is moving.
What it usually does not do is collapse the price of a flat near a functional Metro station with a decent society and a builder who has delivered on time before. Those assets have buyers even in slow quarters. The pain concentrates in oversupplied pockets, speculative projects with weak builders, and stretches where promised infrastructure has been delayed for years.
So the honest read is this: the dip improves your negotiating position if you are buying, and it raises the cost of being wrong about location. It is a window, not a guarantee.
Should I Buy Property in Noida or Gurgaon Now? A Decision Framework
Start by answering the question that most buyers skip: are you buying a place to live, or an asset to hold? The answer changes everything downstream.
Step 1: Define your holding period and your exit
If you plan to live in the flat for at least seven to ten years, short-term price movements matter much less than your EMI comfort and your commute. If you are buying to rent out and sell in three years, you are making a leveraged bet on appreciation plus rental yield, and a soft market can hurt you badly if you need to exit during it.
Write down your holding period as a number of years. Then write down the specific event that would make you sell. A job transfer to Bengaluru, a child's school admission, or a bank loan you cannot service are all real exit triggers. If you cannot name one, you are probably a long-term holder.
Step 2: Run the price-to-rent check
This is the most useful quick test available, and it is embarrassingly simple. Take the all-in purchase price of a comparable flat. Take the annual rent for an equivalent unit in the same micro-market. Divide price by annual rent. That is your price-to-rent ratio.
A rough guide used by many practitioners: a ratio above roughly 25-30 times annual rent suggests you are paying for expected appreciation more than for the income stream, and renting is often financially competitive. A ratio below around 20 tends to favour buying, assuming you will stay put. These thresholds are rules of thumb, not laws, and they shift with interest rates and local supply. But they force the conversation away from "prices are going up" and toward "what am I actually paying for?"
Step 3: Run the EMI-to-income check
Most lenders will look at a debt-to-income ratio, but you should be stricter with yourself. A workable rule: total monthly EMI, including any existing loans, should stay under roughly 40-45% of take-home income, and you should still have six months of expenses in reserve after your down payment. If you need to stretch to 55% to make the numbers work, the market dip is not your problem. Your budget is.
Then stress-test it. Add two percentage points to the interest rate you are quoted and recalculate. If the EMI becomes uncomfortable, you are relying on rates staying exactly where they are, which is a bet you do not need to make.
Step 4: Check the micro-market, not the city
"Noida" and "Gurgaon" are each a dozen different markets. Sector 150 in Noida and Sector 45 in Gurgaon do not behave alike, and a Golf Course Extension Road project and a Dwarka Expressway project can have completely different supply pipelines.
Look at four things for any specific project. First, how many similar units are unsold or being listed in the same micro-market. Second, the status of promised roads, Metro extensions, and water or sewage connections, checked against official notices rather than sales brochures. Third, the builder's delivery history on previous projects, including whether they have faced litigation or RERA complaints. Fourth, the society's maintenance charges and sinking fund practices, which quietly erode returns.
A Worked Example: Two Flats, Same Budget, Different Answers
Consider a hypothetical but realistic case. A couple earning a combined ₹2.4 lakh per month wants a 2BHK and has ₹60 lakh budgeted for the purchase, with a loan at around 8.5% for 20 years. They are looking at two options in NCR.
Option A is a ready-to-move flat in an established Noida society, 900 metres from a Metro station, priced at ₹58 lakh all-in including registration. Equivalent rent in the area is roughly ₹32,000 per month, so annual rent is about ₹3.84 lakh. Price-to-rent is about 15. The EMI on a ₹46 lakh loan at 8.5% over 20 years comes to roughly ₹40,000 per month. Rent is cheaper than the EMI in year one, but the purchase builds equity and locks in housing cost. Price-to-rent of 15 is comfortably in buy territory for someone staying seven years or more.
Option B is an under-construction flat in a Gurgaon project quoted at ₹62 lakh, with a builder offering a discount to ₹59 lakh if they book this month. The project is 3-4 years from possession, the Metro link is still a proposal, and comparable rents in the area are about ₹35,000 per month. Price-to-rent is around 14 on the discounted figure, which looks attractive. But this couple would pay pre-possession EMI or rent in the interim, face the risk of delay, and carry GST on the under-construction component. Their effective cost of waiting for possession, plus the uncertain infrastructure, makes this a riskier bet than the headline ratio suggests.
The lesson: the ratio is a filter, not a verdict. Option A wins for a couple who want stability. Option B only makes sense if they have a genuine cash buffer for the delay, a builder they trust, and a holding period long enough to absorb the risk.
Buy Now or Wait? A Scenario-Based Checklist
Rather than a single answer, use this checklist to see which way you lean.
- Lean toward buying now if you need housing within 12-18 months, your EMI stays under 45% of income even at a higher interest rate, your price-to-rent ratio is below about 20, and you have found a ready or near-ready flat with a clean title and a builder or resale seller you have verified.
- Lean toward waiting if your price-to-rent ratio is above 28, your current rent is comfortable and not forcing a move, you are buying for speculative appreciation, or the only compelling option is an under-construction project with a distant possession date and an unclear infrastructure timeline.
- Lean toward negotiating aggressively now if you are a serious buyer with cash ready and the dip gives you leverage on payment plans, waived charges, or a lower base price. This is often the best of both worlds: you buy, but on better terms than the peak market would have offered.
The Costs People Forget (And Where Deals Quietly Go Wrong)
Headline prices hide a lot of cash that leaves your account in the first six months. Budget for these before you negotiate anything.
- Stamp duty and registration: Stamp duty in Uttar Pradesh and Haryana varies by gender of the registered owner, location, and property type, and registration charges are separate. Check the current circle rate and the applicable rate in your state rather than relying on a broker's rough figure.
- GST on under-construction property: Under-construction residential flats attract GST, with the effective rate depending on whether the project is affordable or not and on the current rules for that category. Ready-to-move property is generally exempt. Ask for the GST line explicitly in the agreement.
- Preferred location and floor charges: These can add several percent to the base price and are sometimes buried in the payment schedule.
- Society maintenance deposits and corpus: Many societies collect a sizeable one-time deposit plus a monthly maintenance charge that rises annually.
- Loan processing fees and insurance: Processing fees, legal verification charges, and property insurance add up.
Pro Tip: Ask the builder or seller for the total landed cost in writing, covering base price, GST, all charges, registration estimate, and first-year maintenance. Compare offers on that figure only. Many "discounted" deals look cheaper on rate per square foot and end up more expensive once preferred location charges and parking are added back.
Common Mistake: Treating the Dip as a Timing Signal
The most expensive error we see is buyers who wait for the market to bottom out, then discover that the flat they wanted has been sold, the builder has raised prices in the next phase, and the broker they trusted has moved on. Trying to time the exact bottom of a regional market is nearly impossible, even for professionals.
A more reliable approach is to fix your numbers first: budget, EMI tolerance, holding period, and a shortlist of acceptable micro-markets. Then buy when a specific property clears all your checks at a price that passes the price-to-rent and EMI tests. The dip is useful because it improves the price you can get on that property, not because it tells you the perfect date.
Practical Steps to Take This Week
- Write down your holding period in years and the one event that would force a sale.
- Calculate your current take-home income, existing EMIs, and the maximum EMI you would accept, then stress-test it at two percentage points higher interest.
- Pull three comparable rental listings and three comparable sale listings in your target micro-market. Compute the price-to-rent ratio for each.
- Shortlist two or three specific projects or flats. For each, check RERA registration, builder history, infrastructure status from official sources, and society charges.
- Request a written landed-cost breakdown from every seller or builder before you negotiate.
- Get a title verification done by a qualified advocate before paying any token amount, especially for resale property.
If you are running the numbers for a rental-versus-purchase decision in Delhi-NCR, our detailed break-even walkthrough for Dwarka and the wider region goes deeper on the maths: Rent or Buy in Delhi-NCR 2026: Which Option Wins for Your Budget? For a closer look at how price growth has outpaced incomes, Who Really Pays for Indian Home Price Rises? Buyer Math for 2026 is worth reading before you commit.
Investors weighing alternatives beyond residential flats may also want to compare returns and liquidity. Fractional Ownership of Commercial Property in India 2026: Is It Worth It? covers a different risk profile, and Tier-2 Cities Up 63% in 5 Years: Where Should You Invest in 2026? looks at where appreciation may be moving next. If your focus is Dwarka specifically, Home Prices Up, Rents Steady: Dwarka Buyer vs Renter Math for 2026 applies the same framework to that micro-market.
Where a Market Dip Changes What You Can Negotiate
A softer market is not just about price. It changes the terms available to you. Builders facing slower bookings often become willing to offer longer payment plans, a fixed-price guarantee on possession, or waived club membership fees. Resale sellers with a vacant flat and a loan to close may accept shorter timelines or a clean handover of documents. Asking for these concessions in writing, tied to specific dates, is far more effective than general haggling over the headline number.
On the financing side, compare offers from at least three lenders. Ask each for the effective rate including processing fees and mandatory insurance, not just the advertised rate. A quarter-percentage-point difference compounds into a real sum over twenty years.
Frequently Asked Questions
Should I buy property in Noida or Gurgaon now if prices are falling?
Buy if you need housing and the property passes your price-to-rent and EMI checks, since a softer market improves your negotiating leverage. Wait if you are buying purely for appreciation, your rent is comfortable, or the only option is a distant under-construction project with uncertain infrastructure. Prices falling in one pocket does not mean they will fall everywhere.
What is a good price-to-rent ratio for buying a flat in India?
As a rough guide, a ratio below about 20 times annual rent tends to favour buying for someone staying seven or more years, while a ratio above about 28 often favours renting. These are heuristics, not rules, and they vary by city and interest rate. Use them as a filter to decide whether a specific property deserves deeper analysis.
How much should my EMI be as a percentage of income?
Aim for total EMIs, including existing loans, to stay under roughly 40-45% of take-home income. Stress-test at a rate two percentage points higher, and keep at least six months of expenses in reserve after paying your down payment and registration costs.
Is GST payable on under-construction flats in NCR?
Yes, under-construction residential property generally attracts GST, with the applicable rate depending on the project category and current rules. Ready-to-move property is typically exempt. Ask the builder to show the GST component separately in the agreement so you can verify it.
Does RERA registration matter when buying in Gurgaon or Noida?
Yes. A RERA-registered project is legally obligated to disclose approvals, timelines, and certain financial details, and it gives you a formal grievance route if the builder defaults. Check the registration number on the state RERA portal rather than trusting a brochure, and confirm the project's status there.
Should I buy resale or under-construction in a soft market?
Resale property gives you possession sooner, visibility into the actual society, and no GST, but may carry higher registration and negotiation complexity. Under-construction can offer lower entry prices and payment-plan flexibility, but adds possession risk and interim rent. In a soft market, resale often gives better value-for-certainty, while under-construction suits buyers with cash buffers who can absorb delay.
How do I know whether an investment property will generate rental income?
Check current rental listings for comparable units in the same sector and building type, not just the asking rents. Factor in vacancy periods, maintenance, property tax, and the cost of management. Compute net yield after these costs, then compare it against your EMI and the return you could earn elsewhere. A property that looks profitable on gross rent often breaks even or loses money after expenses.
The Bottom Line
An 8-9% dip in NCR demand is a useful negotiating window, not a crystal ball. Use the price-to-rent check, the EMI stress test, and the micro-market checklist to decide whether a specific property is worth buying at its current price. If it passes, the softer market helps you get better terms. If it does not pass, waiting is a perfectly rational choice, and no broker's urgency should change that.
If you want help working through the numbers for a specific flat or building a rent-versus-buy model for your situation, you can explore our eDarpan Properties listings, browse properties for sale in India or rental properties in India, or contact eDarpan to talk through the decision with someone who has seen these deals close and fall apart. You can also learn more about eDarpan and the team behind these resources.
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Who Really Pays for Indian Home Price Rises? Buyer Math for 2026
Are Indian home prices outpacing your salary? We break down affordability ratios, EMI math and a worked example to show whether buying still makes sense in 2026.
Rent or Buy in Delhi-NCR 2026: Which Option Wins for Your Budget?
Rent or buy in Delhi-NCR in 2026? Learn the break-even framework, hidden costs and time horizon that decide whether buying really beats renting for your budget.
Fractional Ownership of Commercial Property in India 2026: Is It Worth It?
Can you own a slice of an Indian office, warehouse or retail unit without a ₹1 crore cheque? We break down the structures, real net returns and legal risks.