Metro Corridors Lifting NCR Home Prices: Buyer Checklist for 2026
Metro corridors lift NCR home prices unevenly. Use this buyer checklist to test connectivity, priced-in uplift, net rental yield and EMI risk before you buy.
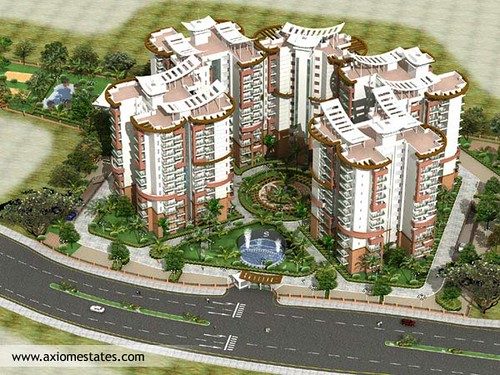
Every few months, someone in a WhatsApp family group forwards a screenshot: "Sector 150 flats up 40% in two years, the Metro is coming, buy now." Some of those calls worked. Many did not. The difference usually came down to whether the buyer checked three things before the news cycle did: how far the connectivity promise was from being real, how much of the uplift was already sitting in the price, and whether the rent a buyer could actually collect justified the EMI. Metro corridors do lift NCR prices, but the lift is uneven, slow to materialise in the places people hype, and easy to overpay for if you arrive late.
This guide is a working checklist for anyone evaluating a metro corridor property price NCR 2026 decision, whether you are a first-time buyer in Noida, a salaried professional eyeing Dwarka Expressway, or an NRI deciding between a Gurugram flat and something back home. It is written from the position of someone who has spent years advising Indian businesses and households on infrastructure-linked decisions and has watched the same mistakes repeat. Where I give numbers, treat them as illustrative ranges to verify against current registered transactions on the IGRS portal of the relevant state, not as quotes.
Key Takeaways
- Price the connectivity, not the announcement. Only count a metro or expressway as priced-in once it has a verified opening date, a running service, and a station within a realistic walk or feeder ride of the project.
- Check how much of the uplift is already in the micro-market. Compare the current per-sq-ft rate against the three-year range in registered sale deeds, not against asking prices on portals.
- Run rental yield on the net figure. After property tax, maintenance, vacancy, and a tax-adjusted view of rental income, many "high yield" flats fall to 2 to 3 percent gross-to-net.
- Separate the metro from the mall. A corridor that stops at a depot or a half-built interchange is a different asset from one with a functioning station and feeder buses.
- Stress-test the EMI against a flat market for five years. If the deal only works when prices keep rising at the pace of the last cycle, it is a speculation, not an investment.
Why metro corridor property prices NCR 2026 are harder to read than the headlines suggest
The NCR is not one market. It is a set of sub-markets sharing a regional name, each with its own supply pipeline, employer base, and infrastructure timeline. A Metro extension that adds a station to Greater Noida West changes the calculus very differently from one that touches a dense, already-connected Gurugram sector. When people ask about metro corridor property prices NCR 2026, the honest answer is that the corridor effect depends on what the corridor connects to, how quickly it is commissioned, and how much new supply lands within its catchment at the same time.
Supply is the variable most buyers ignore. A corridor can announce strong demand and then get swamped by launches from developers who priced their inventory on the metro promise before it arrived. If a station opens and fifteen thousand new units deliver in the same radius within twenty-four months, the scarcity premium you were chasing evaporates. Always check the registered and planned inventory in a 3 to 5 km radius of the station, not just the official route map.
How do I check whether a metro line is genuinely operational or just announced?
This is the first question on the checklist, and it is the one most often answered wrongly. Indian infrastructure timelines slip. Land acquisition, utility shifting, tunnelling through tricky soil, and commissioning trials all add months. A project that was "due in 2024" may still be running trial services in 2026. Build your own timeline rather than trusting the press release.
- Identify the implementing agency and its latest status. For Delhi Metro extensions in NCR, the Delhi Metro Rail Corporation publishes corridor status. For Noida and Greater Noida, check the Noida Metro Rail Corporation. For Gurugram, check Rapid Metro and the state's infrastructure notifications. Look for the most recent dated update, not the most recent news article.
- Distinguish the four stages. Sanctioned, under construction, trial running, and commercial operation are different things. Only the last one should move your price assumption materially. Sanction is a wish; construction is a risk; trial is a promise close to being kept.
- Verify the station is usable. A station with a completed structure but no road access, no feeder bus route, or no pedestrian link is not yet a commuter asset. Visit it on a weekday morning if you can. Count the auto-rickshaws and the feeder buses. Ask a local shopkeeper how long the last trial service took to become a daily habit.
- Confirm the expressway or road link. Many NCR micro-markets are priced on expressway access, not metro access. The Dwarka Expressway, the Eastern and Western Peripheral Expressways, and the Yamuna Expressway each shift the value map. Treat a road that is fully open and tolled very differently from one that is partially built.
- Write down a probability-weighted opening date. Give yourself three dates: optimistic, expected, and late. Price your deal assuming the late date. If the investment only makes sense on the optimistic date, you are not buying the corridor, you are buying a bet on the schedule.
One discipline that has saved clients real money: keep a dated log of every official announcement for the corridor you are considering. After six months, you will see the pattern of slippage. Corridors that have missed three consecutive stated dates deserve a heavier discount in your own model, regardless of how confident the latest press briefing sounds.
A worked example: pricing a station that opened late
Consider a hypothetical buyer, let us call her Meera, a 34-year-old product manager at a Gurugram SaaS firm. In early 2024 she was looking at a 2 BHK in a project roughly 900 metres from a planned station. The developer's brochure showed the station "opening next year." The asking rate was about ₹8,400 per sq ft. Her gut said buy. Her checklist said wait.
She tracked the corridor for eighteen months. The station missed its first stated date, then a second. In the meantime, registered sale deeds for comparable units in the same project hovered around ₹7,600 to ₹7,900 per sq ft, well below the asking rate, which told her the premium was being quoted, not paid. When the station finally began trial running, the registered rate moved up only modestly. The lesson she took away was specific: the gap between asking price and registered price was the market telling her how much of the metro promise was already in the number. A large gap meant the buyer was paying for a future that had not yet arrived.
What is already priced in, and how do I measure it?
Every credible metro announcement moves prices. The question is how far they have moved and how far they still can. The gap between a micro-market's current registered rate and its pre-announcement baseline is the single most useful number you can compute, and it is free to find if you know where to look.
The registered sale value is recorded through stamp duty and registration. In Uttar Pradesh, use the IGRS portal and the circle rate, which is the government floor for stamp duty purposes. In Haryana, use the state's e-registration records. Circle rates lag the market, so do not use them as your price. Use them as a floor, and use actual registered deeds, which reflect what buyers really paid, as your reference.
- Baseline rate. Find registered transactions from twelve to twenty-four months before the corridor was formally announced. Take the median per sq ft.
- Current registered rate. Use the median of the last six months of registered deeds, filtered for comparable unit size and age.
- Asking rate. Pull current listings. Note the gap to registered rate. A 10 to 15 percent gap usually signals negotiating room; a larger gap signals speculative pricing.
- Uplift already captured. Current registered rate divided by baseline, minus one. An uplift above 30 to 35 percent within two years of announcement is a sign that much of the benefit has been absorbed.
There is no universal cutoff, and micro-markets differ, but in practice I have found that buyers who enter after heavy uplift and without a clear commissioning date tend to see flat or single-digit returns for several years. The buyers who did well bought earlier on a credible timeline, or bought with a clear view that the commissioning would be followed by a second wave of demand, such as a new employer cluster.
Pro tip: read the sale deed, not the listing
Here is the non-obvious point that separates experienced buyers from first-timers. Listings reflect what sellers hope to get. Registered deeds reflect what was paid, and they often show the true discount that developers gave to clear inventory. In several NCR projects I have reviewed, the deed price was consistently 8 to 12 percent below the published price list for the same unit type. If you only look at portals, you will overestimate the market and overpay. Ask a registered broker or a property lawyer to pull recent deeds for the specific project and tower, and compare them to the brochure. The difference is your negotiating leverage.
How do I check rental yield realism before I buy for rent?
Rental yield is where many metro-corridor purchases quietly fail. A flat advertised at ₹22,000 per month on an asking price of ₹75 lakh looks like an annual gross yield of about 3.5 percent. That is before anything else. Once you deduct the items that are real costs, the net yield often falls to around 2 to 2.5 percent, which may be lower than the interest you are paying on the loan that financed the purchase.
Build the net yield properly. Start with gross annual rent, then subtract the following:
- Vacancy. Assume at least one month empty per year in a corridor market still settling in. Two months is more prudent for a new micro-market with heavy supply.
- Society maintenance and sinking fund. These vary widely across NCR societies. Get the actual figure from the RWA or the builder's invoice, not an estimate.
- Property tax. Municipal property tax differs by city and by the assessed value of the unit. Confirm with the local municipal body.
- Repairs and tenant turnover. Budget for repainting, minor fittings, and the cost of finding a new tenant when the lease ends.
- Income tax on rent. Rental income is taxable under the head "Income from house property," and you may claim a standard deduction of 30 percent of net annual value plus interest on the home loan, subject to the limits applicable under your tax regime. Model this for your own slab, and do not assume the deduction makes everything work.
After these, compare your net yield to your loan's effective interest rate. If the net yield is lower than the loan rate, you are relying entirely on capital appreciation to justify the purchase. That is a legitimate strategy, but it is a different strategy, and it needs a different risk tolerance.
Worked example: the rental yield that looked good on paper
A small Noida-based consultancy I advised, a 12-person firm that operates as an MSME, had a director who wanted to buy a second flat as a rental for a family member's future use and to generate income. Their first cut showed a 4 percent gross yield at ₹25,000 monthly rent on a ₹75 lakh unit. After vacancy, maintenance of about ₹4,500 per month, property tax, and a realistic turnover budget, the net came to roughly 2.1 percent. Against a home loan at the prevailing floating rate, the monthly cash outflow was negative by about ₹38,000 in the first year. The purchase might still have made sense as a long-term capital bet, but it was not a rental income asset, and the director had been planning around the income. Reframing it as a capital decision changed the entire conversation about how much to pay and whether to wait.
For buyers weighing this trade-off, the loan structure matters as much as the property. If you are deciding between fixed and floating rates for a corridor purchase, the analysis in our guide on fixed vs floating home loan choices in NCR walks through how rate resets interact with rental cash flow.
Which NCR micro-markets are worth comparing, and how do they stack up?
Rather than naming one corridor as a winner, it is more useful to compare the common options on the criteria that matter. The table below is a structured way to score candidates. The ratings are qualitative and should be refreshed with current data before you act on them.
| Criterion | Dwarka Expressway (Gurugram side) | Noida Metro Aqua Line extensions | Greater Noida West corridor | Ghaziabad metro-linked pockets |
|---|---|---|---|---|
| Connectivity maturity | Road strong; metro dependency varies by sector | Operational metro with established feeders | Road and metro improving; feeder density uneven | Mixed; depends on precise station proximity |
| Supply pressure (3 to 5 km) | High, with heavy launch pipeline | Moderate to high in newer sectors | High, large township supply | Moderate, more fragmented |
| Rental demand driver | Corporate and IT-adjacent employment | Corporate, healthcare, and institutional | Mixed residential and student | Residential and commuter |
| Typical gross rental yield (indicative) | Roughly 2.5 to 3.5 percent | Roughly 2.5 to 3.5 percent | Roughly 2.5 to 3.5 percent | Roughly 2.5 to 3.5 percent |
| Risk of delayed uplift | Medium | Low to medium | Medium to high | Medium to high |
Read the yield row carefully. In this illustrative framing, the gross yields look similar across corridors, which is partly the point: the differences that matter come from supply, delivery risk, and how much of the metro effect is already in the price. A buyer who picks the corridor with the highest headline yield without checking those factors is often choosing the market with the most inventory waiting to undercut them.
If you are weighing an NCR purchase against a tier-two city, the comparison changes again. Our piece on tier-2 cities rising in 2026 covers where buyers are getting better value than in the NCR, and it is worth reading before you commit to a high-priced corridor.
Should NRIs buying in NCR apply a different checklist?
Yes, for a few concrete reasons. NRIs face repatriation rules, a different tax residency picture, and often a currency mismatch between their income and their asset. The rupee math shifts with every move in the exchange rate, and a property that looks attractive in dollars or dirhams can look very different after conversion and tax.
If you are an NRI, add these steps to the checklist above. Confirm the legal route for buying: NRIs can generally acquire residential and commercial property in India but not agricultural land or plantation property, and the purchase must be funded through approved channels. Route funds through an NRE or NRO account as appropriate, and keep documentation of the remittance source for future repatriation claims. Model the return in your home currency, including exchange-rate scenarios in both directions. For a deeper comparison of the rupee math against overseas alternatives, see our analysis of NRI property buying in Dubai vs Noida, and for a rental-return lens across Dwarka and Dubai, see NRI home buying in Dwarka vs Dubai.
Common mistake: buying on a power of attorney without checking the chain
This is where I see NRI buyers get hurt, and it is entirely avoidable. Many NRIs sign a power of attorney to a relative or a broker and never see the property or the papers. That is not always fatal, but it removes your ability to verify title, the builder's compliance, and the status of the sanctioned plan. Before any payment, get an independent title search, confirm the project's RERA registration with the state authority, check the occupancy or completion certificate status, and insist on seeing the original sale deed history. A broker who resists this is telling you something.
How do I put the checklist into a decision?
A checklist is only useful if it produces a decision, not a feeling. Here is a sequence that works for most buyers evaluating a metro-corridor purchase in the NCR.
- Set your holding horizon. Decide whether this is a five-year income asset, a ten-year capital asset, or a home you will live in. Each has a different tolerance for delay.
- Verify the connectivity stage. Use the four-stage test. If the station is not in commercial operation, price the delay into your model.
- Compute uplift already captured. Use registered deeds, not listings.
- Build the net rental yield. Deduct every real cost, and compare to the loan rate.
- Stress-test for a flat five years. If prices stay flat and rents stay flat, can you still carry the EMI without distress? If the answer is no, reduce the ticket size or wait.
- Verify legal and RERA status. Title, approvals, RERA registration, and completion status before any substantial payment.
- Decide, and write down why. A written decision memo, even a single page, forces the trade-offs into the open and makes it harder to talk yourself into an expensive mistake.
For businesses buying commercial space or setting up operations in the corridor, the same logic applies to company registration and address requirements. Many MSMEs and startups use a registered virtual office for GST and company registration while they evaluate locations, which avoids committing to a lease before the commissioning picture is clear. eDarpan offers a virtual office address for GST and company registration that can serve as a registered address during that evaluation phase.
Frequently asked questions
Are metro corridor property prices in NCR going to rise in 2026?
Some corridors will, and some will not. Prices rise where a commissioned metro connects a job cluster to a residential area that lacks supply, and they stall where the station is delayed or new launches flood the catchment. Check the commissioning stage, the registered deed trend, and the supply pipeline rather than relying on a general forecast.
Is it better to buy near a metro station or near an expressway?
It depends on your use case. For daily commuters, walking distance to a working station is valuable, provided feeder transport is reliable. For buyers focused on road access and freight or highway travel, expressway proximity can matter more. In the NCR, the strongest micro-markets often have both, but do not assume a station is useful just because it is nearby on a map.
What rental yield should I realistically expect in an NCR metro corridor?
Gross yields in many NCR corridors sit in a broad range that is often cited around 2.5 to 3.5 percent, but net yield after vacancy, maintenance, property tax, and tax is usually lower. Model your own net figure with a specific unit and a specific society rather than relying on a market average.
How do I verify a builder or project for RERA compliance?
Check the project's registration on the state's RERA portal, which is the Haryana RERA for Gurugram and the UP RERA for Noida and Ghaziabad. Confirm the registration number on the builder's documents matches the portal, check the approved completion timeline, and review any complaints or orders filed against the developer.
Does buying a second property in NCR affect my tax position?
Yes. Rental income is taxable, and there are rules on capital gains, interest deduction, and the treatment of multiple properties that depend on your residency and regime. Consult a chartered accountant with your specific holdings in mind before you commit, because the numbers are sensitive to your slab and your loan structure.
Should I wait for the metro to open before buying?
Waiting reduces the risk of paying for an unopened promise but usually means paying a higher price. The right answer depends on how much uplift is already captured and whether the commissioning date is credible. In many cases, a disciplined buyer waits for trial running and a stable commissioning date, then makes the decision with better information.
Where can I find properties in NCR that fit this checklist?
If you are shortlisting options, browse the properties for sale in India on eDarpan Properties, or compare rental stock on the rental properties in India listings. Use the checklist above to test each shortlisted project against registered-deed prices and the commissioning stage before you visit.
Final word and next steps
The question is not whether metro corridors lift NCR prices. They do. The question is whether a particular corridor, at a particular price, on a particular commissioning date, is still a good deal for you. Use the checklist to answer that for each candidate. Verify the connectivity stage, measure the uplift already captured in registered deeds, compute net rental yield honestly, and stress-test for a flat market. Write the decision down.
If you want a second pair of eyes on a shortlist, eDarpan can help you structure the analysis, from pulling registered deed comparisons to building a net-yield model for a specific unit. You can explore our IT and business consulting and get in touch through the contact page or learn more about eDarpan. For the full range of services, see eDarpan services overview.
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Home Loan Rates Stuck or Falling? Pick Fixed vs Floating in NCR
Stuck EMI or chasing a lower rate? See how fixed vs floating home loans in India behave in today's RBI environment, and run the break-even math for NCR borrowers.
NRI Property Buying in Dubai vs Noida: Rupee Math for 2026 Investors
Gross rent looks attractive, but net rupee yield tells the real story. See how a Noida flat stacks up against a Dubai apartment for NRI investors in 2026.
NRI Home Buying in Dwarka vs Dubai: Rupee Returns After 2026 Rule Changes
Dwarka or Dubai? See how rupee conversion, taxes, repatriation rules and hidden costs reshape NRI rental returns after the 2026 rule changes.