Delhi-NCR Home Loan Rates 2026: Fixed vs Floating After RBI Cuts
Repo cuts have made the fixed-vs-floating choice urgent for Delhi-NCR borrowers. Here's how each structure really behaves, with EMI numbers on a Dwarka flat.
If you are about to sign a home loan in Dwarka, Gurgaon, Noida or Greater Noida this year, the rate question is no longer academic. After the RBI's repo rate reductions, many borrowers who locked in a fixed rate are asking whether they overpaid, while others on floating rates are wondering whether the next cut will actually reach their EMI. Plenty of first-time buyers have been told that "floating is always cheaper," and plenty of investors have been told the opposite. Both claims are too simple. The right answer depends on your tenure, your risk tolerance, your prepayment plans and, frankly, how the bank passes on policy changes.
Here is a number worth sitting with. On a ₹60 lakh loan over 20 years, a movement of just 1 percentage point in the interest rate changes the EMI by roughly ₹4,000 to ₹4,500 a month, and the total interest paid by more than ₹10 lakh over the life of the loan. That is the kind of gap that makes the fixed-versus-floating decision worth doing properly. This article walks through how the two structures actually behave in India today, runs EMI numbers on a typical Dwarka flat, and gives you a decision process you can apply to your own case. If you are still deciding whether to buy at all, our analysis of rent vs buy in Dwarka 2026, covering stamp duty, EMIs and real yields, is a sensible place to start before you get to rates.
Key Takeaways
- Floating rates in India are almost universally linked to an external benchmark (EBLR or RLLR) and reset when the RBI moves policy rates, but the pass-through depends on the bank's reset schedule.
- Fixed rates are not truly fixed for the full tenure. Most retail home loans fix for 1 to 5 years, then convert to floating or get reset, so read the clause carefully.
- Check the prepayment penalty: RBI rules bar foreign-currency-free penalties on floating-rate personal and retail loans, but fixed-rate prepayment charges can still apply.
- On a 20-year loan, the choice matters less than your behaviour: a floating borrower who prepays aggressively can beat a fixed borrower who doesn't.
- Model at least three rate scenarios (flat, down 50 bps, up 75 bps) before deciding. A rate you can survive at +1% is worth more than the lowest headline number.
- Ask your lender for the reset dates, spread over benchmark and the processing fee in writing before you sign.
How home loan fixed vs floating rate India 2026 actually works in practice
Start with what changed structurally. Since 2019, RBI has required banks to link new retail floating-rate loans to an external benchmark, either the repo rate or, in many cases, the bank's own external benchmark lending rate (EBLR). Once the benchmark moves, your rate should reset, typically within three months under the RBI framework. That is why a repo cut usually reaches your EMI faster than it did a decade ago. It is not automatic, though. Some lenders reset quarterly on a fixed date, some on the anniversary of disbursal, and spread changes can offset benchmark cuts. A 0.25% benchmark cut that comes with a spread increase may leave your effective rate unchanged.
Fixed-rate loans work differently. The rate is set for an initial period, commonly one to five years, and the lender agrees not to change it during that window. After that, the loan typically converts to a floating rate or is re-priced at the then-current rate. So a "fixed" 8.9% loan for three years is really a three-year hedge, not a 20-year guarantee. Read the conversion clause before you treat it as protection.
What the fixed premium really buys you
Fixed rates in India usually sit higher than the floating rate on the same lender's book at the time of sanction, because the bank is charging you for taking on rate risk. Whether that premium is worth paying depends on where you think rates are going and how much certainty you need. A salaried professional in Noida with a stable income and a tight budget may value a fixed EMI for the first few years at almost any price. A self-employed contractor in Gurgaon with lumpy receivables may prefer floating, because the EMI falls when rates fall and the prepayment flexibility is cheaper.
Worked example: a typical Dwarka flat loan
Let us take a common case. A two-BHK flat in Dwarka Sector 23 priced at ₹85 lakh, with a 20% down payment of ₹17 lakh, leaves a loan of ₹68 lakh over 20 years. We will compare three rate scenarios. These numbers are illustrative and use standard EMI arithmetic; check your own lender's sanction letter for exact figures.
| Scenario | Interest rate | Monthly EMI | Total interest over 20 years | Total payable |
|---|---|---|---|---|
| Floating, current benchmark | 8.50% | ₹58,000 (approx.) | ₹1.23 crore (approx.) | ₹2.31 crore (approx.) |
| Floating, after 50 bps cut | 8.00% | ₹55,600 (approx.) | ₹1.13 crore (approx.) | ₹2.21 crore (approx.) |
| Floating, after 75 bps rise | 9.25% | ₹62,800 (approx.) | ₹1.38 crore (approx.) | ₹2.46 crore (approx.) |
| Fixed for 3 years at 9.00%, then floating | 9.00% fixed, then reset | ₹60,900 (approx.) | Depends on post-year-3 reset | Depends on reset |
Two things stand out. First, the swing from a 75 bps rise to a 50 bps cut is about ₹7,000 a month, which is a meaningful share of a typical household's surplus. Second, the fixed option at 9% costs roughly ₹2,900 more per month than the current floating rate on day one. You are paying that premium for three years of certainty, and whether that is a good trade depends on your conviction about the rate path, which nobody can reliably forecast.
Now apply the same numbers to a 15-year tenure. The EMI rises, but total interest drops by a large margin, and the sensitivity to rate moves per rupee borrowed is somewhat lower because the balance declines faster. Shorter tenures make the fixed-versus-floating choice less consequential; long tenures make it more consequential.
Which should you choose: a decision framework for NCR borrowers
Rather than picking based on a headline rate, run through a short sequence of questions. Each one narrows the decision.
- How stable is your income over the next three years? If your EMI at a +75 bps scenario would take more than 50% of your take-home pay, or leave you with less than six months of expenses, lean toward fixed for a sensible initial period.
- Do you plan to prepay? If you expect bonuses, a business exit, or the sale of another property, floating with zero prepayment penalty is usually the better tool, because you can cut principal without paying a fee.
- What is the spread on each option? Ask for the effective rate after the spread, not just the benchmark. A fixed rate 0.4% above the floating equivalent costs real money over 20 years.
- What happens at the conversion date? If the fixed loan converts to a floating rate with a higher spread, your protection is shorter than it looks.
- Do you have a rate-cut thesis? Investors who believe the RBI will cut further may prefer floating. Anyone who needs to sleep well should not bet the household budget on that thesis.
A pro tip most borrowers miss
Here is the non-obvious point we raise with clients. Many borrowers compare the rate they are offered today, but the more important number is the rate that will apply in year five, when the loan is being serviced under real pressure. Ask the lender to show you the EMI under a +100 bps path sustained for the whole loan, not just the next reset. If the EMI still fits your budget, the floating option is low-risk regardless of what the RBI does next. If it does not, a fixed-rate tranche or a shorter tenure is the safer route, even at a higher headline cost.
Common mistakes borrowers make with fixed and floating loans
The most frequent error is treating the processing fee and spread as minor. On a ₹68 lakh loan, a 0.5% processing fee is ₹34,000 before GST, and a spread difference of 0.2% can add over ₹1.5 lakh of interest across 20 years. Ask for the full cost of each offer in one sheet.
The second mistake is ignoring the insurance and cross-sell clauses. Some banks tie the lower rate to a mandatory insurance product or a credit card. Strip those out and compare the bare rate; then decide whether the bundled product is worth its cost to you separately.
The third is assuming that a lower repo rate automatically lowers your EMI. Check whether your lender uses a repo-linked rate (RLLR) or its own EBLR, and whether the reset is contractually fixed. If your reset is quarterly and the benchmark cut came in the last week of the quarter, you may wait months before the EMI changes.
Step-by-step: how to compare loan offers before you sign
- Collect at least three offers from banks, housing finance companies and, where relevant, your employer's preferred lender. Include public sector banks and private banks.
- Request, in writing, the benchmark, spread, reset frequency, reset date, processing fee (including GST), prepayment charges, and the fixed-rate period if applicable.
- Build a simple sheet with columns for EMI, total interest and total cost at the current rate, at −50 bps and at +100 bps.
- Calculate what share of your monthly take-home the EMI represents in each scenario. Set a personal ceiling, for example 40% at the stress case.
- Check the title documents and the RERA registration of the project before you finalise the loan, because the lender's sanction is tied to a clean title and an approved project.
- Ask the lender to confirm the disbursement timeline, since delays in the developer's construction-linked payments can affect your interest outgo.
- Once you are satisfied, get the sanction letter, read every clause, and keep a copy of the rate reset schedule with your property file.
If you are sorting out the property side in parallel, our team at eDarpan Properties can help you shortlist flats in Dwarka and across NCR, including properties for sale in India, so that your loan decision is made against a realistic price and a confirmed unit rather than an estimate.
Should NCR investors use floating rates for rental properties?
For investors, the case for floating is often stronger, because rental income and rate movements are both variable and the prepayment option has real value. If you plan to sell or refinance within five to seven years, a fixed rate with a long lock-in or a high prepayment penalty can eat into your returns. Investors buying for rent should model the loan alongside the rental yield in the same sheet, using the same stress scenarios. A flat in Dwarka yielding 2.5% gross against an 8.5% loan is negatively leveraged on the current numbers, and it only works if capital appreciation carries the difference. Our analysis of whether HNIs and NRIs should buy luxury homes in NCR now covers the appreciation side in more depth. Investors who want to rent out the unit should also look at the rental property market in India for realistic tenant demand before committing.
Does timing your purchase around rate cuts make sense?
Rate cuts are real, but the property market moves on its own cycle. Developers and sellers adjust prices around festive seasons and inventory levels, and a discount on the unit can outweigh a 25 bps rate difference. The question is not whether the RBI will cut next quarter, but whether the total cost of buying now, including the possibility of a better price later, is lower than waiting. For a more structured view on timing, see our breakdown of festive season home buying in 2026 and whether developer discounts beat waiting, and our note on negotiating harder on unsold NCR homes. If you are weighing corridor choices, the NCR metro expansion corridors piece will help you judge where appreciation is likely to come from.
Frequently asked questions
Is a fixed or floating home loan better in India in 2026?
Neither is better in every case. Floating loans usually have lower starting rates and no prepayment penalty on retail borrowings, which suits borrowers with variable income or plans to prepay. Fixed loans give payment certainty for the initial period at a premium, which suits borrowers whose budget would be stressed by a rate rise.
How much does a 1% change in home loan rate change my EMI?
On a ₹68 lakh loan over 20 years, a 1 percentage point change moves the EMI by roughly ₹4,000 to ₹4,500 per month. The effect is smaller on shorter tenures and larger on longer ones. Run the numbers on your own loan amount before deciding.
Do banks charge a prepayment penalty on floating-rate home loans?
For individual borrowers on floating-rate retail loans, RBI rules generally prohibit prepayment penalties. Fixed-rate loans can carry charges during the fixed period, and the rules for non-individual borrowers differ. Confirm the exact charge in the sanction letter.
What happens to my fixed rate after the fixed period ends?
Most fixed-rate home loans convert to a floating rate linked to the bank's benchmark, or are re-priced at the lender's then-current rate. The new spread may differ from the one you were quoted, so ask for the conversion terms in writing before signing.
How often does a floating-rate home loan reset?
It depends on the lender and the benchmark. Repo-linked loans typically reset within three months of a policy change, while some EBLR-linked loans reset on a fixed quarterly or annual schedule. Get the reset frequency and next reset date from your bank.
Should I switch from fixed to floating, or floating to fixed, mid-loan?
Many lenders allow a rate-type switch, sometimes for a fee or a small conversion charge. Weigh the fee against the expected savings over the remaining tenure. A switch that saves less than the fee within a year or two is rarely worth doing.
Can I get a home loan at a lower rate if I have a strong credit score?
Yes. A higher credit score and a lower loan-to-value ratio usually earn a better spread. Improving your score before applying, and bringing a larger down payment, can meaningfully lower the rate you are offered, sometimes by more than a policy cut would.
If you are at the stage of comparing lenders, properties and timing all at once, eDarpan can help you put a single plan together, from shortlisting flats to modelling EMIs under different rate paths. You can reach the team through our contact page, and you can read more about how we work on the about page. For businesses that want wider advisory across property, technology and compliance, our IT and business consulting team handles the planning side as well.
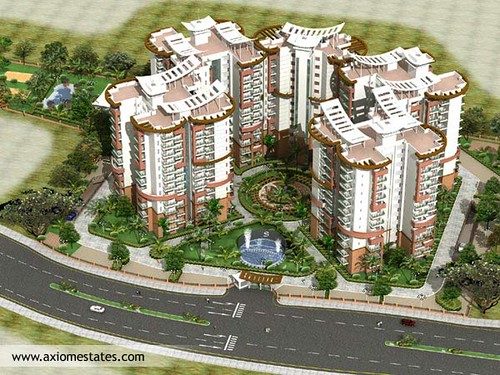
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Premium Housing Sales Up 2026: Is Buying a Luxury Flat in NCR Smart?
Premium homes are carrying Delhi-NCR's sales value in 2026. Here's a practical framework to test whether a luxury flat makes financial sense for you.
Home Loan Prepayment vs Investing SIP in Delhi-NCR 2026: Math Guide
Should extra cash prepay your home loan or fund an equity SIP? Break-even maths, tax notes and a checklist for Delhi-NCR borrowers in 2026.
Rent vs Buy in Dwarka 2026: Stamp Duty, Loan EMIs & Real Yields Compared
Is renting or buying in Dwarka smarter in 2026? We compare stamp duty, loan EMIs and real rental yields to show which path fits your holding period.