How Rising Delhi NCR Home Prices Impact Your Budget & Options
Delhi NCR's 12% property price surge is derailing budgets. Learn strategic fixes, affordable alternatives, and whether to buy now.
You’ve run the numbers. You’ve saved diligently, perhaps even secured a pre-approval from your bank. The dream of owning a home in Delhi NCR, a tangible asset and a foundation for your family, feels within reach. Then you open the latest property report or speak to a few brokers, and the reality hits: the goalposts have moved. Again. A sustained 12% year-on-year surge in Delhi NCR property prices isn't just a headline; it's a direct blow to your carefully planned budget, forcing a complete re-evaluation of what's possible.
For the middle-income professional, entrepreneur, or investor, this isn't abstract economics. It's a practical crisis. The 3BHK in your preferred Gurgaon sector that was quoted at ₹1.8 crore last quarter is now pushing ₹2.1 crore. The monthly EMI you calculated has jumped by ₹15,000-20,000. This price shockwave, fueled by infrastructure pushes, premium project launches, and raw material cost inflation, demands more than just disappointment. It demands a strategic recalibration.
This guide is written from the trenches, not the ivory tower. We’ll dissect this price surge and move straight to actionable strategies. We’ll explore how to reallocate your budget beyond just cutting square footage, identify genuine affordable alternatives within commuting distance, and provide a clear-eyed analysis on whether to buy now, wait, or invest differently. This is about navigating the new reality of Delhi NCR property prices 2026 with your financial sanity intact.
Key Takeaways:
- The 12% price surge primarily impacts ready-to-move and premium under-construction inventory; secondary markets and older societies may offer relative value.
- Budget reallocation is critical: consider redirecting funds from discretionary business tech upgrades or luxury expenses towards a higher down payment to keep EMIs manageable.
- Affordability isn't just about cheaper locations, but about smarter locations: emerging corridors like Dwarka Expressway (New Gurgaon), Noida Extension, and parts of Greater Noida West offer better value-per-square-foot.
- Timing the market is less important than timing your finances. If you have the necessary capital and stable income, delaying for a potential minor correction could backfire if prices rise further.
- Co-investment or fractional ownership models are becoming viable for middle-income buyers, especially for commercial or larger residential plots.
- Your primary residence is a lifestyle asset first; pure investment properties should be evaluated under different criteria, potentially in high-growth tier-2 cities.
Decoding the 12% Surge: What's Really Driving Prices Higher?
Let's be specific. This isn't a uniform 12% increase across the board. A luxury high-rise in Golf Course Road Gurgaon or a builder-floor in South Delhi's prime colonies will see a much steeper climb than a 10-year-old apartment in a well-maintained society in Ghaziabad's Indirapuram. The surge is concentrated in:
- New Launch Premiums: Developers are pricing new projects based on future infrastructure promises (like the upcoming Noida Airport or Metro expansions) and increased compliance costs (RERA, GST, environmental clearances).
- Input Cost Inflation: Cement, steel, and labour costs haven't softened. A builder completing a project today is working with a 15-20% higher construction cost than one who locked in rates two years ago.
- Consolidated Developer Demand: The market is increasingly favoring large, financially stable branded developers. Their projects command a 10-15% premium over smaller players, pulling the average price up.
- The "Ready-to-Move" Premium: In an environment of project delays, a completed, RERA-registered property with immediate possession can be 8-12% more expensive than a comparable under-construction option.
The implication is clear: your search criteria directly determine your exposure to this surge. Insisting on a specific, high-demand micro-market will hurt. Being flexible on project stage, builder profile, and even the age of the property can reveal pockets of relative value.
Case Study: The Ghaziabad Business Owner's Pivot
Consider Ajay (name changed), who runs a 40-employee MSME manufacturing unit in Ghaziabad. In late 2024, he planned to buy a ₹2.4 crore builder-floor in a prime West Delhi location, with a ₹60 lakh down payment. The 12% price increase pushed that same property to nearly ₹2.7 crore, increasing his required loan amount and pushing his EMI beyond his comfort zone, especially with business cycles being unpredictable.
Instead of abandoning his plan, Ajay worked with a consultant to re-strategize. He realized a significant portion of his business's operational budget was tied up in inefficient, legacy systems. An outdated on-premise server for his ERP and inventory, costing ₹35,000 monthly in maintenance and power, and a manual telephony system for customer support were bleeding resources.
The Pivot: Ajay opted for a strategic budget reallocation. He invested a lump sum of ₹3 lakh into a cloud migration for his core systems and implemented an AI-powered voicebot for handling customer inquiries and order tracking. This reduced his monthly IT overhead from over ₹50,000 to under ₹20,000, freeing up ₹30,000 in steady monthly cash flow. He combined this saving with a decision to shift his search to a well-connected, newer sector in Greater Noida West, where a comparable property was available for ₹2.15 crore. The result? A lower overall loan burden, an EMI close to his original projection, and a more efficient business. The takeaway: sometimes, the capital for your home can be found by optimizing your business operations.
Practical Budget Reallocation: Finding the Extra 20 Lakh
When faced with a price jump, the instinct is to reduce the budget. A smarter approach is to reallocate it. Here’s a numbered walkthrough for a middle-income family or business owner.
- Audit Discretionary Business Expenses: Scrutinize software subscriptions, marketing budgets, and administrative costs. Can you switch from a premium CRM to a more affordable custom-built solution? Could bulk SMS campaigns be more effective than certain digital ads? Redirect annual savings to your down payment corpus.
- Revisit Personal Finance Leakage: High-interest personal loans or credit card debt? Consolidate and pay them off. The interest saved is direct capital for your home. Consider deferring a luxury car upgrade or an international vacation for a year.
- Liquidate Non-Performing Assets: That old commercial plot bought years ago that's not appreciating? The small stock portfolio that's stagnant? Consult a financial advisor. Consolidating assets into a primary residential property is often a sound move.
- Optimize Existing Property Equity: If you already own a smaller home or a parental property, explore if a top-up loan on that asset can bolster your down payment for the new one, reducing the loan-to-value ratio on the new purchase.
- Formalize Co-Investment: With siblings or a trusted partner? Consider a formal co-ownership agreement. Pooling resources can help you access a better property class or location than going solo.
Pro Tip: The Hidden Cost of "Waiting for a Correction"
Many buyers decide to pause their search, hoping for a market correction. While prudent in some cycles, the current Delhi NCR market is driven by tangible infrastructure growth and supply-side cost push. If your ready capital is sitting in a savings account earning 4-6% while property prices are rising at 10-12%, you are effectively losing purchasing power each month. The calculus should be: "Can I secure a price today that I can live with, even if the market dips 5% next year?" If yes, waiting is often more expensive.
Affordable Alternatives: Where to Look When Your Prime Locale is Out of Reach
Shifting geography is the most direct way to combat high prices. "Affordable" doesn't mean compromising on connectivity or amenities; it means identifying the next growth corridor.
| Location Alternative | Average Price (₹/sq. ft) | Key Connectivity & Infrastructure | Ideal For | Compromise vs Prime Areas |
|---|---|---|---|---|
| Dwarka Expressway (New Gurgaon) | 10,000 - 14,000 | Direct access to IGI Airport, Dwarka, upcoming Diplomatic Enclave, Metro alignment. | Young professionals, airport employees, those working in Cyber City but priced out of Sectors 50+. | Longer commute to South Gurgaon/Cyber Hub until expressway fully operational; ongoing construction. |
| Noida Extension (Greater Noida West) | 6,500 - 9,500 | Noida-Greater Noida Expressway link, Proposed Metro Blue Line extension, proximity to upcoming Jewar Airport. | First-time buyers, investors with a 5-7 year horizon, Noida-based professionals. | Peripheral location, lower density of high-end social infrastructure currently. |
| Bhiwadi & Neemrana (Rajasthan border) | 4,500 - 7,000 | NH-8, Delhi-Mumbai Industrial Corridor (DMIC) node, industrial and logistics hub. | Industrialists, investors seeking rental yield from industrial workforce, those with ultra-budget constraints. | Significant commute to Delhi/Noida core (60-90 mins), not ideal as a primary family home for city workers. |
| Yamuna Expressway Belt | 5,500 - 8,500 | Yamuna Expressway, F1 Track, proposed Film City, planned educational institutes. | Long-term investors, buyers seeking large plots, those attracted to mega-project announcements. | Farthest from Delhi core; social infrastructure is in nascent stages; higher reliance on private transport. |
Don't limit your search to residential plots. For business owners, using a virtual office address for GST registration and company formalities can allow you to base your operations affordably in a business park in one of these emerging areas, while living elsewhere. This decouples your business location from your home location, expanding your options.
Investment Timing in a Volatile Market: Buy, Wait, or Look Elsewhere?
Is Delhi NCR still a good investment at these prices? The answer depends entirely on your goal.
- For a Primary Residence (5+ year horizon): If you find a property that meets 80% of your needs at a price you can sustain, buy it. The emotional and financial security of owning your home outweighs short-term market fluctuations. Use a 10-15 year lens, not a 2-year lens.
- For a Pure Investment (Seeking Appreciation): The entry point is now high. The annualized returns may be lower than in previous cycles. Consider diversifying. Look at high-growth tier-2 cities with stronger fundamentals. We've analyzed some of these in our post on Top Tier-2 Cities for Property Investment 2026. Also, explore fractional ownership of commercial property, which offers exposure to prime commercial real estate with a lower ticket size.
- For a Hybrid (Future Office + Investment): With RTO mandates stabilizing office demand, buying a small commercial space in an emerging corridor for your own business use can be shrewd. It builds business asset equity while potentially offering rental income later.
Action Plan: Your 8-Week Checklist to Secure a Home
- Weeks 1-2: Financial Deep Dive & Reallocation. Finalize your revised budget using the reallocation strategies above. Get a fresh, written loan pre-approval from your bank factoring in the new price realities.
- Weeks 3-4: Zone Expansion & Shortlisting. Physically visit 2-3 alternative locations from the table above. Shortlist 5-7 projects/societies, mixing ready and under-construction options.
- Week 5: Due Diligence. Verify RERA registration numbers. Check builder track record for delays. For older resale properties, scrutinize society maintenance, pending litigation, and ownership history. This is where professional consulting can save you from costly mistakes.
- Week 6: Negotiation & Closure. In a high-price market, everything is negotiable: the parking slot, the club membership, the modular kitchen fittings. Offer a quick closure to leverage a 1-3% discount. Ensure all tax implications (Stamp Duty, GST) are clearly calculated.
- Weeks 7-8: Documentation & Transition. Work with a legal advisor to review the Agreement for Sale. Initiate loan disbursement procedures. If you're selling an old property to fund this, coordinate the timelines tightly.
Frequently Asked Questions (FAQ)
Are Delhi NCR property prices expected to fall in 2026?
A significant, widespread fall is unlikely due to entrenched cost-push factors and sustained demand in core sectors. However, a period of consolidation or a minor correction (2-5%) in over-heated micro-markets is possible. Don't base your primary home purchase on betting on a crash.
Should I buy a ready-to-move or under-construction property now?
Ready-to-move offers certainty and immediate EMI start, but at a premium. Under-construction offers a lower entry price but carries project delay risk. If you have stable current accommodation, a reputed builder's under-construction project can be a value buy. Always cross-check stage-wise payment plans with RERA mandates.
How does GST impact residential property purchases?
For ready properties, no GST applies (only stamp duty). For under-construction properties, GST is levied at 5% (without ITC) for non-affordable housing and 1% for affordable housing. Ensure the builder's quoted price explicitly states whether GST is included or extra.
Is it better to rent and invest the difference?
In the long run (10+ years), ownership usually builds more equity in India. However, if the rent-vs-buy differential is extreme (e.g., rent ₹25,000 vs EMI ₹80,000 for a similar property), and you can discipline yourself to invest the ₹55,000 monthly difference wisely, renting can be a viable financial strategy, offering liquidity.
What are the best resources for checking property prices and trends?
Use a combination of reputable online portals for initial trends, but rely on direct engagement with local, registered brokers for on-ground prices. RERA websites for project details and banking sector's internal valuation reports (through your loan officer) are excellent, unbiased sources.
Can my business help finance my home purchase?
Indirectly, yes. A profitable, well-structured business improves your loan eligibility. Some business owners take a loan against business assets or investments for the down payment. However, mixing personal and business finances requires careful planning and professional advice to avoid compliance or cash flow issues.
Where can I find genuine listings for affordable properties?
Beyond portals, explore dedicated listings from niche brokers operating in your chosen alternative location. Platforms like eDarpan Properties curate options focusing on value and verified listings, which can be a good starting point for your search in both residential and commercial segments.
Conclusion: Regaining Control in a Shifting Market
The narrative of relentless price growth in Delhi NCR can make you feel powerless. The key is to shift from a passive buyer reacting to quotes, to an active strategist shaping your own outcome. By reallocating your budget intelligently—often by optimizing the very business that funds your purchase—and being pragmatic about location, you can still secure a valuable asset. Remember, the market for Delhi NCR property prices 2026 is not a monolith. It is a mosaic of sub-markets, each with its own dynamics. Your mission is to find the segment where your financial readiness intersects with genuine value. Start with a clear audit of your resources, expand your geographical horizon, and move with decisive purpose. The home is out there; you just need a sharper map and a tougher negotiator at the table—your future self will thank you for the diligence.
If navigating this complex landscape feels overwhelming, remember that strategic planning is what we do. From optimizing your business operations to free up capital, to leveraging technology like WhatsApp Business API for better customer engagement on the go while you house-hunt, to simply needing a sounding board for your investment strategy, our team at eDarpan is here to provide the grounded, practical advice that comes from having built and deployed real solutions in the Indian SMB context.
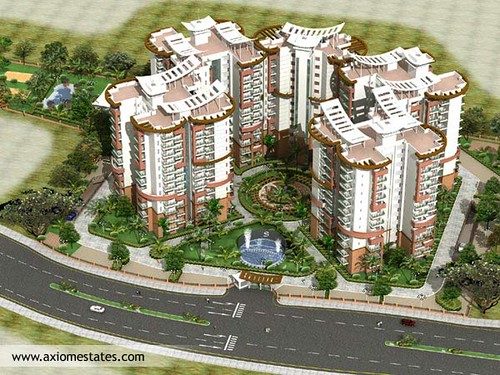
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Goa, Bhopal, Lucknow: Top Tier-2 Cities for Property Investment 2026
Move beyond expensive metros. Discover why Goa, Bhopal & Lucknow are the top tier-2 cities for high-yield property investment in 2026, backed by data & infrastructure growth.
How AI Infrastructure Growth is Reshaping Delhi NCR Office Demand
AI infrastructure growth is reshaping office demand in Delhi NCR, making power and connectivity as crucial as location for future-proof investments.
Branded Residences in India 2026: Luxury Living or Smart Investment?
Is the premium for branded homes in India justified by returns? We analyze rental yields, capital appreciation, and tax pitfalls for the savvy investor.