Housing Sales Fall in 7 Cities: Should You Buy, Rent or Wait in 2026?
Housing sales are softening across seven Indian cities. Here's how to read the slowdown, weigh total ownership cost, and decide whether to buy, rent, or wait.
Your landlord just sent a renewal notice with a 9% hike. Your cousin in Pune says prices are finally cooling and you should wait. A property portal ad promises "limited-period offers" on a 2BHK in a township you have never visited. Meanwhile, the EMI calculator says you could own for less than you pay in rent, if only you knew whether the numbers hold up. If you have been stuck on the question should I buy or rent property India 2026, you are not alone, and the answer depends far more on your specific numbers than on any headline.
Reports of softer housing sales across seven major Indian cities have made the decision feel urgent in both directions. Some buyers are reading the dip as a window to negotiate. Others are reading it as a warning sign. Both readings can be wrong for you. A market slowdown lowers the price of a specific asset in a specific micro-market; it does not tell you whether owning beats renting for your life, your income, and your next five years. In this post I will walk through how to interpret the slowdown, what unsold inventory actually does to your bargaining position, a worked example with real rupee figures, and a practical framework you can run on your own numbers this week.
Key Takeaways
- A dip in sales volume is not the same as a fall in prices. Read the inventory and price-per-square-foot data for your micro-market before deciding anything.
- Unsold inventory improves your negotiating power, but only if you are a serious buyer with financing ready. Developers give concessions to buyers who can close, not to browsers.
- Run the rent-versus-buy comparison on total cost of ownership, including stamp duty, registration, maintenance, property tax, and the opportunity cost of your down payment, not just the EMI versus rent.
- A home loan's interest deduction under Section 24(b) and principal under Section 80C can change the math, but only if you are in the old tax regime and have enough taxable income to use them.
- Waiting has a real cost. If prices rise 5% a year and you wait two years while rent rises too, you may simply pay more for the same asset.
- Your job stability, emergency fund, and time horizon matter more than the market mood. Buy only if you can hold the property through a downturn without selling in panic.
What the Sales Dip in Seven Cities Actually Tells You
When analysts say housing sales fell, they usually mean the number of units registered or transacted in a period dropped compared with the previous period. That is a statement about volume, and volume and price move for different reasons. A market can see fewer sales because buyers are waiting for lower prices, because interest rates rose, because the mix of new launches shifted toward expensive projects, or because developers are holding back supply. Each of these has a different implication for you.
Start with three numbers you can actually find. First, the unsold inventory: the count of completed or under-construction units that have been launched but not sold. Rising unsold inventory usually means developers are under pressure and will negotiate. Second, the realised price per square foot in your target locality, not the asking price on portals. Asking prices are often sticky for months while actual transactions quietly move lower. Third, the absorption rate, roughly how quickly new supply is being sold. If a project with 400 units is selling 20 a quarter, that is a very different signal from one selling 120 a quarter.
The common mistake here is treating a city-level headline as if it applies to every project. Gurgaon's New Gurgaon belt and Noida's Sector 150 area can have entirely different supply dynamics even though both sit under the NCR umbrella. A city-wide dip can coexist with a tight market in a well-located, infrastructure-rich pocket. Always look one level below the city.
How unsold inventory changes your bargaining power
High unsold inventory gives buyers leverage, but the leverage is conditional. Developers in a slow market typically offer some combination of a direct discount on the base price, waived or reduced preferred location charges, free parking or a club membership, a payment plan with a lower initial outflow, or a waiver on the delayed possession charge clause. The discount you can extract depends on whether you are a real buyer.
Here is the practical sequence. Get your home loan pre-approval before you negotiate, because a builder knows that a buyer with sanctioned finance can close in thirty days. Ask for the all-inclusive price in writing, meaning base price, GST applicable on the under-construction property, stamp duty and registration estimates, maintenance deposit, and any other charges. Compare two or three projects in the same micro-market on this same all-inclusive basis. Only then ask for a concession, and ask for it on the total, not on the base price alone, because a builder can cut base price while adding charges elsewhere.
Remember the GST treatment. For under-construction residential property, GST on the affordable and mid-segment category is applied at a reduced effective rate on the value, and this is often built into the quoted price. Confirm with the builder exactly what percentage they are charging and whether the input tax credit rules have altered the figure, because a clean written breakup protects you later.
Should I Buy or Rent Property India 2026: The Framework
The honest answer to the question people keep asking is that renting versus buying is a financial comparison plus a lifestyle decision. The financial part is calculable. The lifestyle part is yours. Below is a framework that works for most salaried or self-employed Indian households.
Step 1: Calculate the true annual cost of owning
Most people compare the EMI with the rent. That is incomplete. The true annual cost of owning includes the interest component of your EMI in the early years, property tax, society maintenance, repair and renovation provisions, and the opportunity cost of the down payment you could otherwise have invested. The principal repayment is not a cost in the same sense, because it builds equity, so keep it separate and count it as savings.
The opportunity cost is the most underestimated line. If you put ₹20 lakh of down payment and stamp duty into a debt instrument or equity that returns 7 to 9 percent after tax, that foregone return is a real cost of owning. Ignoring it is how many people convince themselves that buying is cheaper than it is.
Step 2: Add the one-time transaction costs
In most states, stamp duty and registration together typically run into the range of around 6 to 8 percent of the property value, though the exact rate varies by state, by gender of the buyer in some states where women get a concession, and by whether the property is new or resale. Add brokerage if you are buying a resale property, typically around one to two percent, and legal and documentation charges. On a ₹1 crore property, transaction costs alone can reach ₹7 to ₹10 lakh. Renting has its own one-time costs too, mainly the security deposit, which you get back, and brokerage for a rental, which you do not.
Step 3: Compare the rent-equivalent yield
A simple test is the rent-to-price ratio. Divide the annual rent for a comparable property by its purchase price. In many Indian localities this ratio sits well below what the home loan interest rate would imply, which is why renting can be financially rational even when owning feels emotionally right. If the gross rental yield on a comparable property is far below your loan rate and you do not expect strong appreciation, renting and investing the difference is often the stronger financial path. If the yield is close to or above your effective cost, buying becomes more attractive.
Step 4: Model two scenarios over your actual horizon
Your time horizon is the single biggest variable. Real estate transactions carry heavy entry and exit costs, so a short stay is usually a losing proposition. A useful rule: if you expect to stay less than five to seven years, renting usually wins. Model a base case, a bull case where prices rise faster, and a bear case where they stagnate or fall for two years. If owning only makes sense in the bull case, you are speculating, not buying a home.
Step 5: Test your cash flow and resilience
Run your EMI at a higher interest rate than you have been quoted, say two percentage points higher, to see if it still fits. Keep at least six months of expenses as an emergency fund after the down payment, not before it. The most common way buyers get hurt is not by a falling price but by losing income while carrying a large EMI and having to sell at a bad time.
Worked Example: A Pune Family Deciding Between Buy and Rent
Consider a hypothetical but representative case. A two-earner household in Pune, combined take-home income of ₹2.4 lakh a month, is weighing a ₹85 lakh 2BHK in a developing corridor against renting a comparable flat for ₹38,000 a month. They have ₹22 lakh saved and could take a loan of ₹70 lakh for 20 years at roughly 8.6 percent.
The monthly EMI on ₹70 lakh at 8.6 percent over 20 years works out to roughly ₹60,000. Add society maintenance of about ₹4,000 a month and property tax of about ₹1,500 a month averaged over the year, and the ownership outflow is around ₹65,500 a month. Against rent of ₹38,000, that looks like a ₹27,500 monthly gap in favour of renting.
But the full comparison adds the principal repayment as savings, roughly ₹11,000 a month in year one rising over time, which reduces the effective gap to about ₹16,500. The down payment of ₹15 lakh plus about ₹6 lakh in stamp duty and registration is cash that cannot earn a return. If that ₹21 lakh were invested at 8 percent, it would generate roughly ₹14,000 a month in notional returns at the outset, which is a significant opportunity cost. Once you count that, the gap narrows to a few thousand rupees a month and is sensitive to appreciation assumptions.
The family's decision then turned on horizon. They planned to stay at least ten years and expected modest appreciation of around 5 to 6 percent a year in the locality. Over ten years at that rate, the property would roughly reach ₹1.4 to ₹1.5 crore, which comfortably covers their total cost and transaction charges. They chose to buy, but only after making sure the EMI stayed under 35 percent of take-home income even at a rate two points higher, and after keeping a seven-month emergency fund. The lesson is not that buying was right for them. It is that the decision became clear only once every line was on paper.
Buy, Rent, or Wait: A Comparison of Your Options
Waiting is not a neutral choice. It is a bet that prices or rates will move in your favour, and it has costs of its own. The table below compares three paths on criteria that matter most to a typical Indian household.
| Criteria | Buy Now | Keep Renting and Invest the Difference | Wait 12 to 24 Months |
|---|---|---|---|
| One-time entry cost | High: down payment plus roughly 6 to 8% stamp and registration | Low: deposit and brokerage, mostly recoverable | Low now, but rent and prices may rise while you wait |
| Monthly cash outflow | Usually higher than rent in early years | Lower, with surplus invested | Same as renting, but the cost of waiting accumulates |
| Equity building | Yes, through principal repayment and appreciation | Only through investment returns | None until you buy |
| Flexibility to move | Low: exit costs are high | High | High, until you commit |
| Best suited for | Stable income, 7+ year horizon, emotional need for ownership | Uncertain job or city plans, shorter horizon, disciplined investors | Buyers with a firm target price who can afford to walk away |
When waiting makes sense
Waiting is defensible when you have a specific, measurable target, such as a particular price per square foot or an EMI ceiling, and you are prepared to walk away. It is also reasonable if a specific infrastructure milestone in your locality, a metro line opening or a road project, is likely to re-rate prices, though be sceptical of timelines because infrastructure projects in India routinely slip. Waiting without a target is just drift.
Pro Tip: Read the Possession Clause Before the Price
Here is a non-obvious point experienced buyers learn the hard way. In a slow market, buyers focus on price discounts and forget to check the possession timeline and the delay compensation clause. Under RERA, a registered project must specify a possession date, and buyers are generally entitled to delay compensation if the builder misses it, but the rate and mechanics vary by state and by agreement. A project that promises possession in 24 months and delivers in 48 can cost you two years of double rent plus interest on your loan. Before you sign, confirm the project's RERA registration number on the state RERA portal, read the agreement's delay clause, and ask what the compensation rate is. A smaller discount on a project with a credible, RERA-registered delivery record is often worth more than a bigger discount on a project with a weak track record.
A Step-by-Step Checklist Before You Commit
- Pull the realised transaction price per square foot for your target locality from recent registrations, not just listing portals.
- Check the project's RERA registration and its stated possession date on the state RERA portal.
- Get the all-inclusive price in writing, with GST, stamp duty and registration estimates, maintenance deposit, and every other charge itemised.
- Obtain home loan pre-approval and confirm the EMI at a rate two percentage points above your quoted rate.
- Run the rent-versus-buy model on your actual horizon with a base, bull, and bear case.
- Check your tax position: home loan interest deduction under Section 24(b) applies up to prescribed limits for self-occupied property, and principal under Section 80C is available in the old regime, so confirm which regime suits you.
- Confirm your emergency fund covers at least six months of expenses after the down payment is paid.
- Have a property lawyer verify title, approvals, and encumbrances before you pay the token amount.
How eDarpan Can Help
If you are weighing a purchase, browse properties for sale in India on eDarpan Properties, or if renting is the better fit for now, explore rental properties in India. Both listings let you compare localities side by side before you commit. If you are a business owner or an investor evaluating property as part of a company's assets, our IT and business consulting team can help you structure the financial model and track the numbers, and reach out to eDarpan if you want a second pair of eyes on your analysis. Learn more about who we are on our about page.
For deeper dives on specific markets, you may find these useful: Rent vs Buy in Delhi-NCR 2026: A Break-Even Calculator Guide walks through the break-even mechanics in detail, and Delhi-NCR Price Surge: Is It Better to Rent or Buy Now? looks at the same trade-off during a rising market. If you are considering newer launches, UP Model Building Rules 2026: Impact on Noida and Greater Noida Properties covers how regulation affects supply in that corridor. For a view across asset classes, India's Real Estate Market Splits: What It Means for Investors is a useful companion, and Hyderabad and Bengaluru Lead Sales Surge: What It Means for Buyers shows how sales momentum differs across southern markets.
Frequently Asked Questions
Is it a good time to buy property in India in 2026?
It depends on your micro-market and your own finances rather than the national mood. A sales dip can improve your negotiating position in a project with high unsold inventory, but it does not guarantee lower prices in every locality. Buy if the all-inclusive price is fair against recent transactions and the EMI fits your income with room to spare.
Should I buy or rent property India 2026 if I plan to move cities in five years?
For a horizon of five years or less, renting usually wins because transaction costs on both buying and selling eat into any appreciation. Renting and investing the down payment preserves flexibility. Buying makes sense only if you are confident the time horizon is longer or if the rent-to-price ratio in your target area is strongly in favour of ownership.
How much down payment do I need to buy a house in India?
Banks typically finance up to around 75 to 90 percent of the property value depending on the loan amount and your profile, so the down payment is commonly 10 to 25 percent. You also need to budget for stamp duty, registration, and other charges, which can add roughly 6 to 8 percent of the property value in many states. Check your state's exact rates before finalising.
Does a home loan really save tax in India?
It can, but only under specific conditions. Interest on a home loan for self-occupied property can be deducted under Section 24(b) up to the prescribed limit, and principal repayment can qualify under Section 80C within its overall cap, both available in the old tax regime. If you have opted for the new regime, these deductions are generally not available, so the tax benefit should not drive your decision on its own.
What is RERA and why does it matter when I buy?
RERA, the Real Estate (Regulation and Development) Act, requires registered projects to disclose key details and gives buyers a grievance route and delay compensation rights. Before paying, check the project's registration on your state's RERA portal. An unregistered project carries significantly higher risk of delay or dispute.
Can I negotiate a property price in a slow market?
Yes, but the leverage is strongest for serious buyers with pre-approved finance who negotiate on the all-inclusive total. Ask for waived charges, a better payment plan, or a direct discount, and get any agreed concession in writing before you pay the booking amount.
Is renting always cheaper than buying in India?
No. Renting is often cheaper on monthly outflow, but ownership can win over a long horizon in many localities, especially if appreciation is steady and the rent-to-price ratio is favourable. The right answer depends on the specific numbers in your city and neighbourhood, which is why running the full comparison matters more than any rule of thumb.
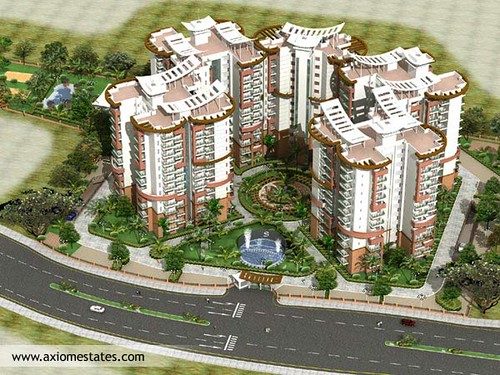
Image credit: Bangalore Properties - Real Estate India - Shriram Symphony by nancyarora2020 via flickr (BY-SA 2.0), sourced through Openverse.
Written by
Rajesh Tiwari
Real estate analyst covering property markets across Delhi NCR, Mumbai, and Bangalore. Rajesh tracks pricing trends, RERA compliance, and investment opportunities for residential and commercial buyers.
Looking for a technology partner?
From IT consulting to virtual office to custom software — eDarpan can help.
Continue reading
Rent vs Buy in Delhi-NCR 2026: A Break-Even Calculator Guide
Renting or buying in Delhi-NCR? Use this break-even framework, with a worked example, to decide with numbers instead of gut feel before 2026.
UP Model Building Rules 2026: Impact on Noida & Greater Noida Properties
UP's new 2026 building rules will reshape Noida & Greater Noida real estate, with major impacts on FAR, costs, and project approvals.
India's Real Estate Market Splits: What It Means for Investors
India's real estate market is splitting. Learn why commercial assets now offer stable cash flow, while residential success depends on hyper-local, end-user demand.